AI ambitions collide with finance’s data reality check
The gist
Finance’s AI revolution is running headfirst into a data reality check—ambition’s easy, but trust and results are stuck in the spreadsheet era.
What to know
- Banks’ post-2008 data reforms like BCBS 239 haven’t solved fragmentation, and late-2026 AI pilots are exposing 100% error risks in manual, disconnected workflows.
- By September 2026, only 14% of CFOs reported real AI value while 86% blamed legacy systems, and leaders like Bank of America’s Matthew Davies warn that fragmented data means wasted AI investment.
- Two-thirds of finance teams already use AI, but just 39% of CFOs trust it to act alone, with 99% of private equity firms seeing a gap between AI ambition and operational reality.
BCBS 239: Crisis Catalyst
Global banking’s post-2008 data reforms were born from regulatory panic, not technical ambition, recasting fragmented data as a systemic risk rather than a mere operational nuisance.
The origin of modern bank data discipline was not theoretical; it was a direct response to failure in the 2007–2008 financial crisis, when systemically important banks could not quickly or accurately aggregate risk exposures across entities and business lines. That breakdown made clear that fragmented systems and inconsistent reporting structures were not back-office inconveniences but supervisory and stability problems, prompting supervisors and the Basel Committee to develop new principles specifically aimed at risk-data aggregation and internal risk reporting.
That post-crisis response culminated on 31 January 2013, when the Basel Committee on Banking Supervision published BCBS 239, “Principles for effective risk data aggregation and risk reporting,” establishing 14 principles covering governance, risk-data aggregation, risk reporting, and supervisory review. BCBS 239 was explicitly framed as a governance-and-supervision standard for globally systemically important banks, linking enterprise risk-data aggregation and reporting to supervisory review expectations rather than treating data quality as a narrow technical issue.
AI Magnifies Data Weakness
Layering AI onto fragmented finance data accelerates errors and exposes costly inefficiencies, turning manual workarounds into enterprise-wide vulnerabilities.
AI is proving less a repair tool than a stress test for finance operations. Cpapracticeadvisor News argued there is “a 100 percent chance of error when you rely on manual spreadsheet work at an enterprise scale,” and that when advanced AI is layered onto fragmented, inconsistent data, companies get “faster, more confident mistakes,” not better decisions; the same underlying fragmentation shows up operationally when “nearly 30% of a human agent’s time each day is spent on ‘swivel-chairing’ among systems or on data re-entry across multiple, disconnected tools versus directly assisting customers.” AI CFO Office made the same point from the market side, criticizing how “for two years the vendors sold you the tip of the iceberg… The pithy insights, the pretty dashboards, the auto-generated board narrative,” while skipping the slow foundation work.
The operational consequence is that AI cannot deliver measurable transformation until data is unified, structured and governed across workflows. Tech Times warned that “forcing unconstrained algorithms into existing workflows without adapting data infrastructure yields severely detrimental outcomes” and cited “a 95% failure rate in demonstrating P&L impact,” while requiring “strict adherence to regulatory frameworks such as the EU AI Act, NIST AI RMF, and ISO 42001” plus explicit general-ledger mapping; that governance gap is reinforced by the finding that only “15% of the respondents had gone through the process of getting individual departments to bring their knowledge, documents, rules, PDFs, etc., into an enterprise knowledge layer which the agentic system can access.” Wealth Management added that isolated AI agents deliver only modest gains, whereas coordinated workflow redesign can exceed 10% growth only with a unified, governed data model.
Rushed AI Hits a Wall
Finance leaders now warn that skipping foundational data work in the AI race leads to stalled projects, wasted investment, and unreliable results.
By August 2026, finance leaders were saying publicly that the problem was no longer whether to invest in AI, but whether rushed deployment was producing anything measurable. In Tearsheet News, Bank of America’s Matthew Davies warned that “the biggest risk and challenge is misinvestment rather than underinvestment,” tying that risk to fragmented data across ERP systems, treasury platforms, bank portals, and acquired businesses; his sequencing was explicit: standardize data first, automate repetitive work next, and only then pursue larger AI initiatives, because skipping that order leaves value stalled in reconciliation errors and unreliable outputs.
By September, the stall had become quantifiable. Forbes cited RGP’s December 2025 survey of 200 U.S. CFOs showing that 66% expected significant AI ROI within two years, but only 14% reported meaningful value today; the same survey found just 10% fully trust their enterprise data and 86% said legacy systems were actively limiting AI readiness, while Gartner’s April 2026 research said organizations with successful AI initiatives invest up to four times more in data quality, governance, and AI-ready foundations than peers with poor outcomes. Late-2026 conclusions were reinforced by firms such as JPMorgan, which first modernized analytical data in the cloud and then credited that groundwork for doubling its AI solutions in production in 2025.
CFOs Become AI Gatekeepers
As AI moves from experimentation to accountability, CFOs are pressured to enforce audit-grade standards and prove that automation delivers measurable, controlled value.
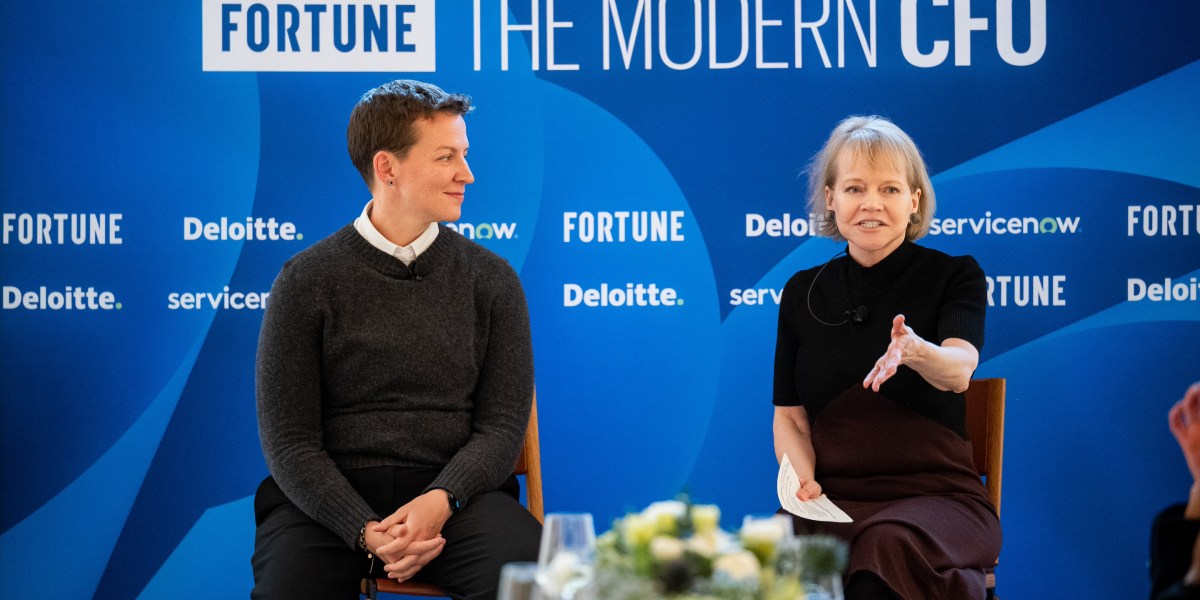
By late 2026, the CFO was emerging as the executive expected to own AI value capture because the job had become less about experimentation than about disciplined capital allocation and measurement. At Fortune’s Modern CFO dinner, Melissa Valentine said generative AI was moving “out of its experimental phase and into something CFOs know well: systematic measurement,” while Laks Srinivasan argued CFOs are “uniquely positioned to define, evaluate, fund, and measure AI initiatives”; notably, a Harvard Business Review survey found only 2% of C-suite respondents assigned CFOs that role, yet when they did, 76% reported substantial value.
That expectation hardened because AI in finance increasingly had to meet the same audit, control, and governance standards as any other material operating system. Research commissioned by iplicit found 83% of finance teams were already using AI but only 53% had a formal framework for safe, compliant use; at the 2026 FutureCFO Conferences in the Philippines and Malaysia, AI governance and ethics were cited by 72% and 69% of attendees, while BlackLine pointed to ISO/IEC 42001 certification as proof that scalable finance AI requires transparency, ethics, and accountability built into the operating model.
Budget pressure then made CFO control unavoidable, because the executive who approves spend is also the one demanding proof that autonomy is safe and worth scaling. Esker said finance leaders are wired to ask “what could go wrong, what the return will be, and what controls need to be in place before making an investment,” adding that CFOs “aren’t rejecting greater AI autonomy” so much as insisting on guardrails; with 72% saying AI spending exceeded plans, the Office of the CFO became the natural checkpoint for ROI, human oversight, and operating boundaries.
Adoption Outpaces Confidence
Despite widespread AI rollout, finance teams and investors remain wary—manual checks persist as trust in autonomous systems lags far behind ambition.
The problem is not a lack of experimentation; it is the scale of adoption colliding with weak real-world confidence. Rillion’s 2026 AI in Finance Report, surveying 250 U.S. CFOs and finance leaders, found 68% of finance teams already use AI, yet only 39% of CFOs are comfortable letting it act independently without human review; nearly nine in ten report shortcomings in invoice capture and data extraction, and 45% still require human review after invoices are processed, underscoring Daniel de Sousa’s warning that adoption alone does not equal transformation.
The same pattern appears beyond corporate finance teams: in private credit, Kevin Hsu said 60% of the funds Lumonic speaks with are still in spreadsheets even as many trial AI for underwriting and diligence, while post-investment work remains stuck in manual workflows. Vistra’s Private Equity Report found every respondent was exploring or implementing at least one AI use case, but 99% still saw a meaningful gap between ambition and operational reality; manual processes consume 33% of capacity on average, 45% cite valuation and reporting complexity, and 89% claim operational progress that underlying automation has not fully delivered.