AI data centers hit gridlock as transformer waits hit 5 years
The gist
America’s AI data center boom has slammed into a five-year transformer shortage, threatening to sideline up to half of new projects as grid hardware becomes the weakest link.
What to know
- Transformer wait times have exploded from under a year pre-2020 to as long as five years, with U.S. supply running 15% short.
- AI campuses can be built in 1–3 years, but grid hardware and interconnection delays now regularly exceed 45 months—outpacing construction.
- By 2026, 30–50% of planned U.S. AI data centers face delay or cancellation, as import bans and industry bottlenecks choke critical power equipment.
When Utility Planning Was Easy
Before 2020, transformer procurement was so reliable that utilities never saw equipment delays as a threat to project timelines.
Before the COVID-era disruption, large transformer procurement was not a critical schedule risk because lead times were typically under one year. As the background record puts it, “Before the COVID-era disruption, utilities could order large transformers with lead times of less than one year, enabling routine replacement and expansion of substations without transformer manufacture becoming a critical schedule risk,” a baseline that frames pre-2020 utility planning as operationally manageable rather than dominated by fears of equipment scarcity or a need to redesign projects around unusually long waits for core grid hardware.
That older procurement environment remained in place through 2019, not because utilities had adopted some new nationwide specification regime, but because they were still working through familiar, incremental standards. The record says “This procurement regime was documented as intact until 2019 and was displaced during 2020–2024 as delivery times extended to 36 months or more,” while Austin Energy’s documented specifications for distribution transformers and switchgear—including “a 34.5-kV metal-clad switchgear spec from 2016 and 15-kV pad-mounted transformer specs from 2018 and 2019”—show continuing incremental utility standardization rather than a new national specification.
Grid Gear Now the Real Bottleneck
Soaring AI electricity demand has flipped the script—transformers, not chips or buildings, now set the pace for new data center launches.
The why-now turn was the market’s recognition that AI demand was no longer mainly constrained by chips or buildings, but by the hardware needed to deliver electricity to them. OilPrice.com said “AI-driven data center growth is creating severe shortages of transformers, substations, gas turbines and cooling equipment as electricity demand surges,” with major manufacturers carrying multi-year backlogs; it added that transformers “have been in increasingly short supply for at least two years,” that U.S. transformer supply is running about 15% short, and that data centers alone could absorb 40% of U.S. power-equipment supply.
That shortage became a true deployment bottleneck because electricity demand is rising faster than grid hardware can be added, so power delivery timelines now exceed data-center construction timelines. Trendforce projected global data-center power demand at 161 GW in 2026, up 31% year over year, while data centers can be built in 1 to 3 years even as ultra-high-voltage grid buildouts take far longer; by 2030, demand is projected at 490.7GW against only 222.6GW of maximum grid supply, a 268GW gap that makes transformer and related equipment scarcity the immediate blocker.
Finished Data Centers Left Powerless
AI-ready server halls are sitting idle for years, waiting on century-old grid hardware that can’t keep up with modern deployment speeds.
What slows AI data center expansion is increasingly not the server hall but the electrical path that makes it usable. Metatrends captured the mechanism plainly: “there’s a two-and-a-half-year wait on power transformers and a three-year wait on step-up transformers,” which is why it framed “the bottleneck in AI” as “boring, century-old electrical hardware” — the specialized equipment required to take a completed facility and actually energize new compute load.
The same logic shows up in grid connection timelines: the delay is in getting power delivered to the site, not merely in planning generation. As one August analysis put it, “We talk about the interconnection queue… how long does it take… before you are hooked up to the grid… That’s gone from 15 months 20 years ago to now coming up on 45,” while SemiAnalysis noted that generation equipment is “useless if the campus waits for transformers, medium-voltage switchgear or the e-houses” needed to make the plant operational.

Global Choke Points and Trade Risks
Transformer supply is squeezed by slow, specialized manufacturing and new import bans, leaving U.S. projects hostage to overseas suppliers and legacy production.
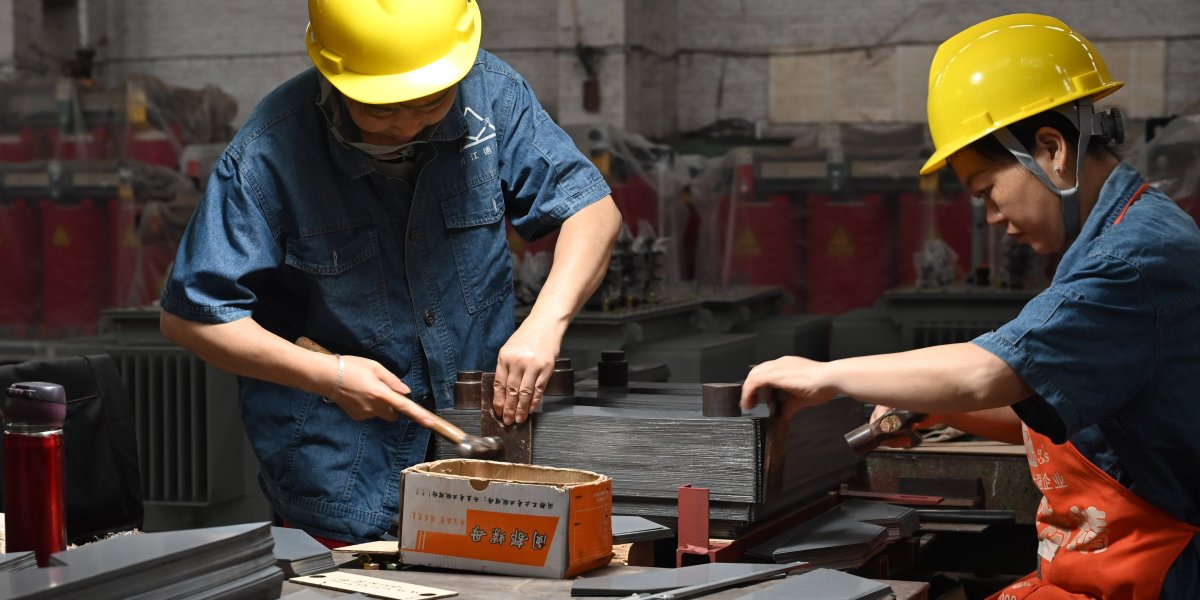
The supply problem is hard to brute-force because transformer production sits inside a narrow, technically specialized manufacturing chain rather than a flexible industrial base. As Shanaka Anslem Perera wrote, “The rate-limiting variable is a 128-week lead time on a metal box wound in copper, whose magnetic core depends on a small, technically concentrated global production base that cannot be expanded quickly even when capital is abundant,” while Fortune describes large power transformers as “giant metal structures” weighing “as much as 400 tons” and notes they are “made largely in the same way they were when they were invented 150 years ago,” implying slow, legacy production methods. That helps explain why, between “2019 and 2025,” demand for “generator step-up transformers” “nearly tripled,” demand for transformers “to work as off-ramps” “more than doubled,” and “costs increasing 80%.”
That fragility is compounded by import dependence for critical components and by demand outrunning a supplier base concentrated overseas. On 26 August, Trump issued an emergency executive order banning the import of “inverters, transformers and other power equipment” from 24 sanctioned countries (China most significant), with transactions prohibited for equipment “initiated” after 26 August 2026; PV Tech Research’s Q2 Battery StorageTech Bankability Ratings Report says “Chinese suppliers dominate the global market,” with “the top five players controlling 39% of market share,” and Primary Transformers CEO Eric Hobby warned on 10 September that “The only new high-voltage bushings available before late summer 2028 are made in China,” adding that banning a single component like bushings would “halt new 345kV+ power transformer purchases in the US for years.”
Long Delays Kill AI Ambitions
Transformer backlogs have become so severe that up to half of planned U.S. AI data centers may never get built, despite massive import surges.
By spring 2026, the transformer shortage had moved from procurement nuisance to commercial filter on AI buildouts. Reid Hoffman said “analysts estimate though that somewhere between 30 and 50% of these AI data centers that are planned for in the US will be delayed or canceled,” and tied that directly to electrical components; he also noted that across 140 projects representing at least 16 gigawatts slated to come online, only around 5 gigawatts were actually under construction, a gap too large to dismiss as routine scheduling slippage.
The timing data show why the impact is so severe: Reid Hoffman said “lead times for high-power transformers used to be around 24 to 30 months before 2020 but now that timeline has stretched out in some cases to 5 years,” while Macro Notes wrote that “Pre-2020, lead times on a US high-voltage power transformer were 24 to 30 months” but the industry had normalized to four to five years, with power transformers averaging 128 weeks. Even heavy import volumes did not clear the market; US utilities imported more than 8,000 high-power transformers from China in 2025, up from fewer than 1,500 in 2022.