Europe’s AI sovereignty dream hits cloudy skies as regulatory divide and US tech dominance persist
The gist
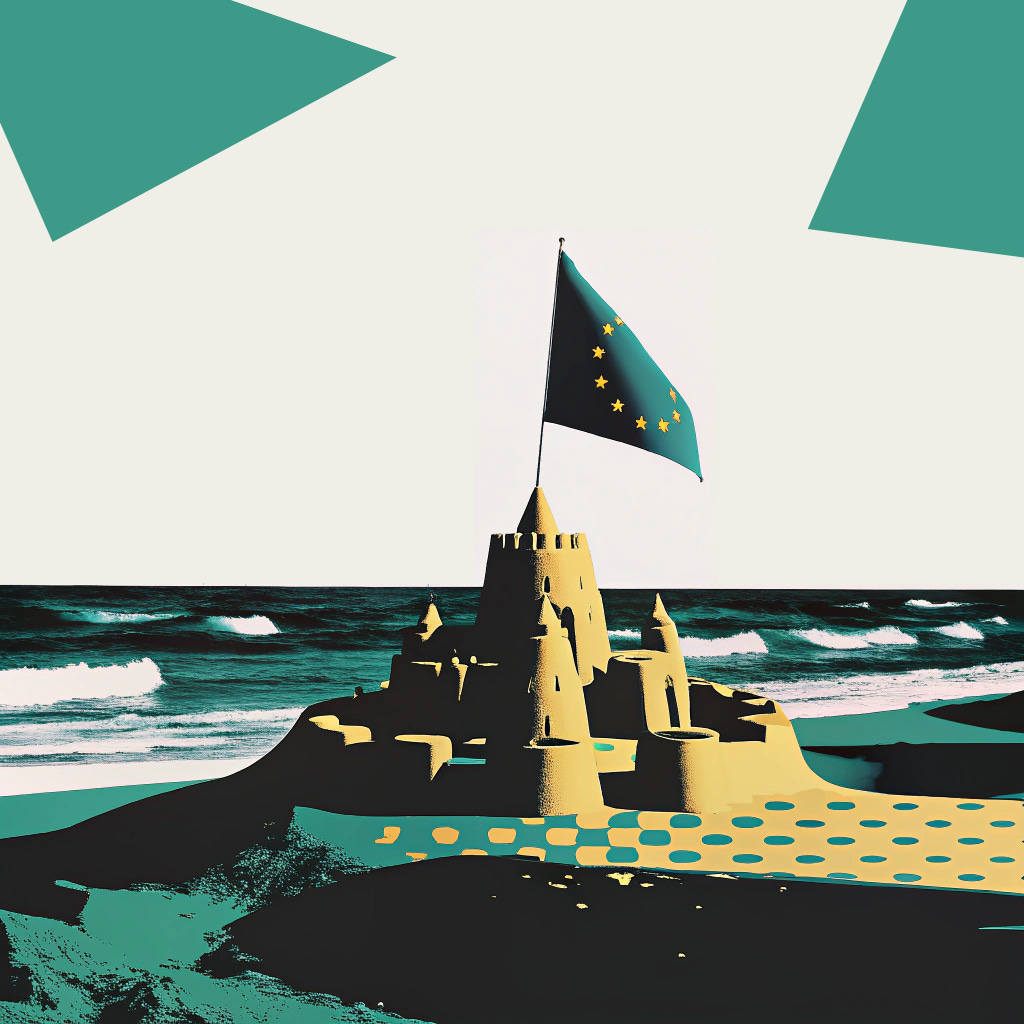
Europe’s AI sovereignty ambitions are colliding with regulatory fragmentation and overwhelming US tech dominance, forcing a high-stakes recalibration of the continent’s digital future.
What to know
- By 2026, the EU’s tough AI Act and the UK’s flexible regime create a compliance maze for firms straddling both markets.
- US cloud giants control 83% of Europe’s cloud market, prompting the EU to invest €180 million in sovereign clouds and roll out strict new sovereignty rules.
- Europe is embracing a two-tier AI ecosystem—native models like Mistral for sensitive sectors and 'tamed' global models on segregated US infrastructure—while scaling back public AI data center ambitions in favor of private investment.
Compliance Maze Deepens
Dueling AI regimes in the EU and UK force companies into costly, fragmented compliance strategies, with the EU’s extraterritorial rules threatening to dilute global harmonization and drive up operational costs.
By early 2026, the EU and UK had adopted markedly divergent regulatory frameworks for AI, creating a complex compliance landscape for companies operating across both jurisdictions. The EU AI Act imposes a prescriptive, high-risk classification system on AI applications in critical sectors like employment, healthcare, and credit scoring, with stringent requirements on data governance, transparency, and human oversight, backed by the European AI Office's extraterritorial enforcement powers. In contrast, the UK favors a lighter, principles-based approach that leverages multiple sector-specific regulators such as the FCA and ICO, emphasizing flexibility and innovation but shifting significant compliance burdens onto firms navigating overlapping and sometimes misaligned regulatory expectations.
The EU AI Act’s extraterritorial reach, often described as the 'Brussels effect,' compels UK companies to juggle dual compliance regimes, as many large firms prefer to align with the EU’s rigorous standards to maintain access to its 450 million consumers. However, unlike GDPR’s infrastructure-wide impact, AI compliance can be maintained as separate layers per market, allowing providers to offer EU-grade documentation solely to European customers while applying minimal disclosures elsewhere. This bifurcation, coupled with delays in enforcement clarity and potential postponements of high-risk obligations until late 2027, threatens to dilute the EU Act’s global influence and complicates the adoption of a unified compliance baseline.
As the EU AI Act’s full enforcement deadline for high-risk AI systems loomed in August 2026, companies faced mounting compliance challenges, including substantial costs—estimated at around €52,000 annually per high-risk system and up to $1 million for large enterprises—and operational hurdles like the widespread absence of comprehensive AI system inventories needed for risk classification. Early integration of compliance measures proved critical, offering auditability and competitive advantages, while delayed efforts incurred 20-40% cost premiums and deployment delays of three to six months. These pressures underscore the Act’s transformative potential to set a global compliance floor, mirroring GDPR’s legacy, even as UK firms grapple with reconciling this with their domestic principles-based framework.
While the UK eschews a standalone AI Act, it has embraced international frameworks such as the OECD AI Principles and the Council of Europe's Framework Convention on AI, signaling a commitment to embedding human rights, democracy, and accountability into its AI governance. However, these commitments remain non-binding and have yet to be fully transposed into UK law, leaving regulatory certainty in flux. This international alignment contrasts with the EU’s inward-looking focus on protecting European citizens from harmful AI, even as many of the most powerful AI systems deployed in Europe originate from outside the bloc, complicating enforcement and compliance dynamics.
Sovereignty Versus Cloud Giants
Europe’s push for digital autonomy collides with US tech dominance and legal conflicts, as new EU rules and massive investments aim to wrest control from American cloud providers but highlight the near-impossibility of true AI independence.
By mid-2026, Europe’s quest for AI sovereignty has been significantly complicated by the dominance of US-based cloud providers, who control 83% of the continent’s cloud infrastructure market, and the extraterritorial reach of the US CLOUD Act, which mandates American companies comply with US government data requests regardless of where data is stored. This legal conflict with GDPR has heightened European concerns over data sovereignty and market access, prompting calls for greater regulatory alignment and streamlined cross-border data governance to enable scaling of AI and cloud services within the EU without inconsistent national rules undermining economic viability.
In response to these geopolitical pressures and regulatory fragmentation, the European Commission has taken concrete steps to bolster AI sovereignty, notably awarding a €180 million tender to four European cloud providers to supply sovereign cloud services to EU institutions. Complementing this, the EU’s Cloud and AI Development Act (COM(2026) 502) introduces a nuanced four-level assurance framework that rigorously assesses sovereignty risks based on data location, personnel, infrastructure, and exposure to non-EU jurisdictions. Particularly, Level 2 imposes legal and technical barriers to prevent third-country data access, directly countering US extraterritorial laws, while Level 3 effectively excludes US-incorporated companies acting alone, pushing them toward joint ventures with EU partners to comply.
The intensifying US-China tech rivalry under the second Trump administration has further amplified European and broader global anxieties about dependence on foreign technology ecosystems. Countries like the EU, India, and Japan find themselves in a precarious balancing act—striving to advance AI capabilities without deepening reliance on either US or Chinese tech stacks, with India notably adopting stricter restrictions on Chinese technology than even the US. Yet, as experts caution, complete AI sovereignty remains a fantasy given the globalized nature of supply chains, exemplified by the US’s reliance on Taiwanese chip imports, underscoring the complexity of achieving full technological independence.
European efforts to assert data sovereignty have also manifested in regulatory pushback against US corporate maneuvers, exemplified by the Dutch government’s blocking of Kyndryl’s acquisition of Solvinity over CLOUD Act concerns. Meanwhile, the EU’s broader tech sovereignty package aims to restrict US hyperscalers from providing sensitive cloud and AI services to European governments, although key decisions have faced delays. The urgency of these measures was underscored when, just nine days after unveiling the Cloud and AI Development Act, a leading US AI model was abruptly suspended, starkly illustrating Europe’s dependency on American technology and galvanizing political momentum behind the sovereignty agenda.
Europe’s Infrastructure Balancing Act
Massive public investments, strict sovereignty frameworks, and market dominance by US tech giants force Europe to weigh digital self-reliance against higher costs and slower AI adoption.
By mid-2026, Europe has embarked on an ambitious strategic push to establish sovereign AI infrastructure, exemplified by landmark investments like the €75 million EURO-3C project and the €200 billion InvestAI initiative aimed at creating a federated AI network and native model development. Central to this effort is the European Commission’s Tech Sovereignty package, which consolidates critical legislative and industrial measures—including the Cloud and AI Development Act (CADA) and Chips Act 2.0—to triple data center capacity within 5 to 7 years and foster a competitive, secure, and sustainable AI ecosystem that reduces reliance on foreign providers while balancing the pragmatic need for American cloud platforms and chips for less sensitive workloads.
The EU’s Cloud and AI Development Act marks a pivotal shift from voluntary digital sovereignty aspirations to binding procurement rules, introducing a rigorous four-level Sovereignty Effectiveness Assurance Levels (SEAL) framework that assesses providers on 48 criteria spanning legal, operational, technological, and supply chain controls. This framework, already applied in a €180 million sovereign cloud contract awarded to European providers like OVHcloud and Scaleway, aims to ensure that sensitive public-sector workloads meet stringent autonomy and sustainability standards, though debates continue over the strictness of ‘effective control’ criteria, with France and industry leaders advocating for tighter restrictions to exclude providers vulnerable to extraterritorial laws such as the US CLOUD Act.
Despite Europe’s robust network infrastructure and ambitious plans to triple data center capacity, the continent faces structural challenges: US cloud giants—Amazon, Microsoft, and Google—dominate roughly 70-83% of the European cloud market, exposing Europe to data sovereignty risks under conflicting laws like the US CLOUD Act. Recent US restrictions on overseas AI model access have intensified calls from European leaders, including French Prime Minister Sebastien Lecornu, for stronger sovereign AI tools, yet critics warn that prioritizing European self-reliance may slow adoption and inflate costs by up to 40%, underscoring the difficult trade-offs in Europe’s quest for digital autonomy amid a globalized tech landscape.
Europe’s approach to scaling AI infrastructure is evolving, with a recent pivot toward attracting private investment to accelerate data center construction rather than relying solely on public sector-led projects. However, even with these efforts, Europe’s AI computing capacity remains a modest 5% of the global total compared to the US’s 80%, highlighting the steep climb ahead. Emerging European AI companies like Mistral show promise but still lag significantly behind US counterparts such as OpenAI in valuation and scale, reflecting the broader competitive gap that Europe’s Tech Sovereignty package and associated initiatives aim to bridge over the coming decade.
AI Copyright Gridlock
Regulatory uncertainty and geopolitical maneuvering stall progress on unified AI content licensing, leaving publishers—especially in Latin America—at a severe disadvantage in the global AI economy.
By mid-2026, the regulatory landscape for AI content licensing remains a patchwork quilt of divergent policies, with the UK halting a controversial copyright opt-out that would have allowed AI firms to train on published works unless rightsholders objected, while the EU postponed its comprehensive AI and copyright review until 2027. This regulatory limbo exacerbates uncertainty for publishers and AI developers alike, complicating efforts to establish clear licensing frameworks across borders.
Compounding these regulatory delays, geopolitical dynamics—most notably the assertive trade leverage wielded by the second Trump administration—have effectively constrained the international community’s ability to harmonize AI content licensing rules. This strategic use of trade policy to blunt global AI regulation underscores how geopolitical tensions are entangling what might otherwise be a straightforward path toward unified standards.
Meanwhile, publishers in Latin America find themselves particularly disadvantaged amid this fragmented environment, lacking any comprehensive AI agreements across 19 countries and a combined Spanish-speaking audience exceeding 600 million. With advertising markets thinner than those in Europe or the US and referral traffic dwindling, individual publishers face a stark erosion of bargaining power, highlighting how regional disparities in market size and regulatory cohesion deepen the challenges of navigating AI content licensing.
Two-Tier AI Reality Emerges
Europe’s AI landscape splits into sovereign, locally governed models for sensitive sectors and regulated global models for commercial use, with Chinese AI effectively shut out of critical applications.
By mid-2026, Europe is crystallizing a pragmatic two-tier AI ecosystem that balances sovereignty with innovation. The sovereign tier is anchored by native AI models such as Mistral and Alf Alpha, running exclusively on EU-hosted cloud infrastructure—like Germany’s native platforms—to ensure strict governmental control over critical AI applications. Meanwhile, the commercial tier pragmatically leverages legally compliant, 'tamed' versions of global AI models, including Anthropic’s offerings and open AR models, hosted on segregated AWS or Azure infrastructure within Europe. This bifurcation reflects a strategic compromise acknowledging that total AI self-sufficiency is unattainable, yet sovereignty remains paramount for sensitive sectors.
This emerging dual-track model also signals a significant regulatory and geopolitical filtering of AI technologies within Europe. Despite earlier expectations that Chinese open-source AI models might become integral to the European AI stack, by 2026 it became clear these models face insurmountable regulatory hurdles in sectors handling sensitive data such as healthcare. The stringent EU regulatory environment effectively excludes Chinese AI solutions from regulated spaces, underscoring a shift towards prioritizing trusted, locally governed AI infrastructures over broader global openness in critical applications.
Scaling Back Sovereignty Ambitions
The EU’s retreat from bold public AI infrastructure targets in favor of private investment exposes sovereignty shortfalls and cost challenges, with only a fraction of cloud contracts meeting strict European criteria.
By mid-2026, the EU significantly scaled back its ambitious AI data centre procurement plan, shifting from an initial target of deploying 100,000 advanced chips across 5 centres to a more modest build-out of 7 data centres with specified GPU and processor counts. Despite this adjustment, Europe’s AI computing capacity remains a fraction of global leaders, holding only about 5% compared to the US’s dominant 80%, underscoring the steep challenge the continent faces in closing the infrastructure gap.
This recalibration reflects a strategic pivot from public sector-led expansion toward leveraging private investment to accelerate AI infrastructure development. The EU’s approach now emphasizes attracting private capital rather than relying on government-driven projects, signaling a pragmatic response to market realities and fiscal constraints in scaling AI capabilities.
However, this scaling back and reliance on market forces have sparked criticism regarding the robustness of Europe’s AI sovereignty ambitions. Experts like Cristina Caffarra have labeled the commission’s procurement standards as 'very weak,' with only about 10% of cloud contracts meeting strong European sovereignty criteria. Meanwhile, industry leaders such as Siemens CEO Roland Busch caution that an overemphasis on building indigenous infrastructure could hamper technology adoption, especially given that European cloud alternatives may cost up to 40% more than their U.S. counterparts, as noted by Capgemini COO Karin Brune.