Export bans surge as nations clamp down on raw mineral trade
The gist
Countries from Zimbabwe to Southeast Asia are slamming the door on raw mineral exports, betting big on homegrown processing to seize more of the critical-minerals value chain.
What to know
- Zimbabwe kicked off a wave of export bans in February 2026, with African and Southeast Asian governments following suit to mandate local processing and capture more value.
- Major incentives are flowing, such as a $400 million loan to Sunrise Energy Metals for a US scandium refinery and a $96 million deal with Lynas featuring price floors and royalty relief.
- Governments are raising royalties, pulling permits, and requiring at-home refining, aiming to break China’s 90%-plus grip on mineral processing and reshape global supply chains.
Policy Shift Redefines Value Chains
A coordinated wave of export bans and local-processing mandates across Africa and Southeast Asia is forcing a fundamental reset in how mineral wealth is captured, shifting profits and power away from traditional importers.
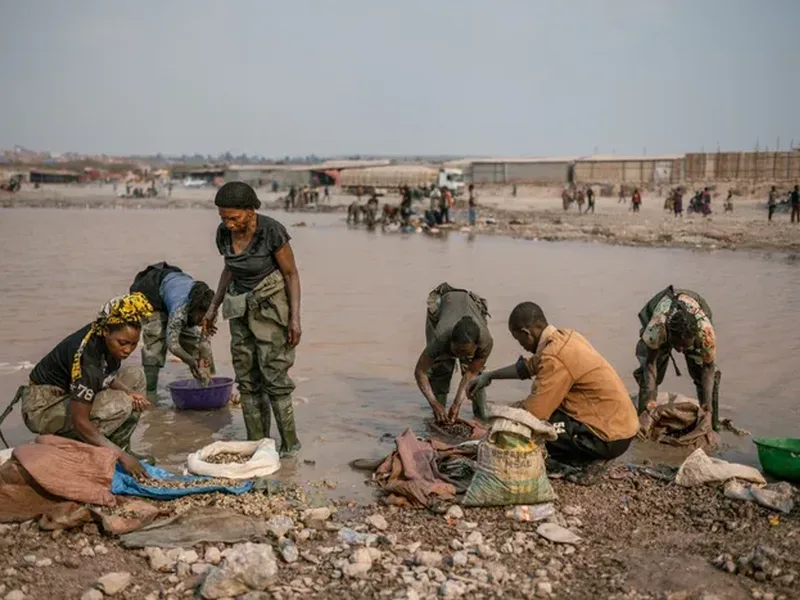
By late Q3 2026, the processing turn had become visible as a policy pattern rather than an isolated intervention. Sustainable Stories Africa tied late-2026 export-ban action to a broader push for local processing and value capture, noting that “Zimbabwe’s February 2026 ban on raw mineral and lithium concentrate exports reflected this new assertiveness,” while an OECD regional note showed why governments were tightening rules: 24% of African critical mineral exports are raw and 72% are only semi-processed, largely ores and concentrates, leaving the higher-value stages elsewhere.
The same late-Q3 direction was emerging beyond Africa, with Southeast Asian producer states tightening “resource sovereignty” through raw-ore export bans and local-processing mandates to capture more value at home. That urgency was sharpened by China’s own controls: “Beijing’s April and October 2025 export controls further raise the strategic value of the region’s heavy rare-earth supply,” and after China “put export controls on seven of the heavy rare earths,” exports dried up and automakers lost magnet access, while one speaker said China has “about 30 things they’re doing this on,” including pressure on battery suppliers and acquisitions across strategic inputs.
Financial Muscle Drives Processing Home
Governments are using targeted loans, price guarantees, and royalty hikes to force midstream processing out of China’s grip and into domestic hands, triggering a global race to control the most lucrative steps in mineral supply.
Governments are no longer relying on rhetoric. They are using finance, pricing tools, and fiscal relief to push processing capacity onto home soil, including a conditional loan of $400 million to Sunrise Energy Metals for a scandium metal refining facility in the US, a $96 million deal with Lynas that used price floors to shield it from potential price crashes, and an offer from the NSW government to defer royalties for five years.
The pattern reflects how concentrated and exposed the midstream has become. China’s control in processing is over 90%, and for heavy rare earths it is close to 95%, 99%, while the sector is described as unhealthy because 95 or 96, 98% is controlled by one party; McKinsey counted about 50 mining-policy announcements globally in 2005 to 2009, roughly 240 in 2020 to 2024, and about 150 already in 2025 and 2026, including Mali lifting royalties to 10% and adding a 10% free carry, Ghana moving gold royalties to 5-12% and requiring domestic refining, and Guinea revoking permits.
Mining Forum Live says processing concentration remains the signal exposure. In twelve of the fourteen commodities McKinsey assessed, China is the largest processor, with 83% of rare-earth processing, and advocacy groups say trade agreements still leave governance and ESG gaps even as governments demand local refining and manufacturing to build sovereign industrial capacity and reduce dependency on dominant foreign processors.