Global shipping hits breaking point as shadow fleets surge
The gist
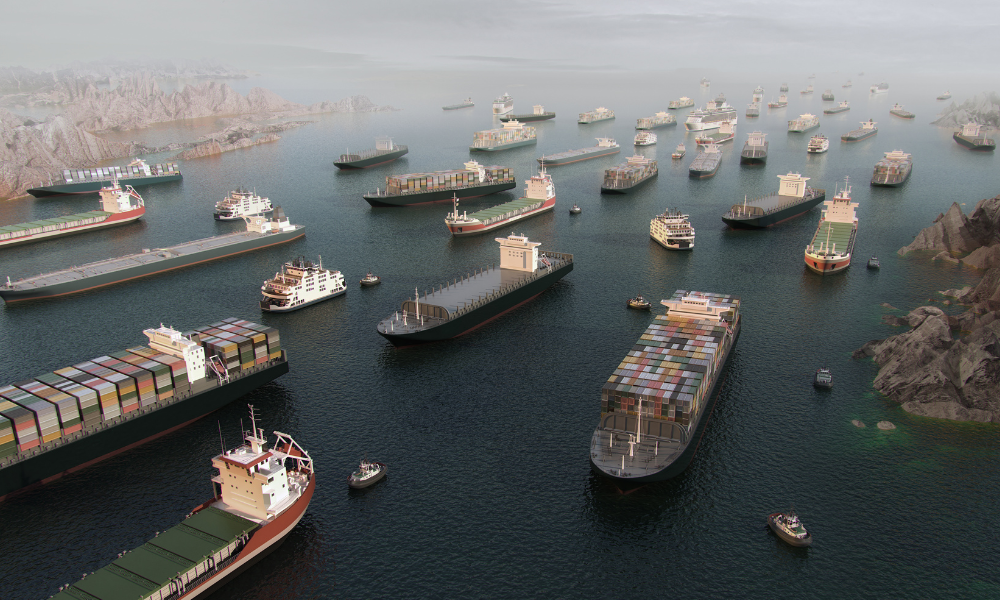
Global shipping is splintering under the pressure of chokepoints, shadow fleets, and surging costs—turning one-off disruptions into a full-blown system-wide stress test.
What to know
- The Consultative Shipping Group has issued a rare warning to 18 nations as chokepoint crises and shadow fleets threaten to fracture maritime trade.
- Spot container rates have rocketed above $7,000 for a 40-foot box, while war-risk insurance is adding up to $8 per barrel of crude.
- A prolonged Hormuz closure could send Brent crude toward $200 per barrel and drag U.S. GDP growth below 1%.
Chokepoints Become the New Normal
Global shipping is now shaped by overlapping crises, with strategic bottlenecks and conflict zones turning once-exceptional disruptions into a constant stress test for maritime routes.
The CSG warning lands differently because it follows a sequence of chokepoint shocks that have made maritime disruption feel continuous rather than exceptional. The Business Standard describes a world where wars, security threats and contested passages now translate directly into freight spikes, delays and volatility, and the latest Hormuz crisis sharpened that pattern: “The United States-Israeli war on Iran erupted on 28 February, 2026,” after which “Tehran… effectively close[d] the strait to almost all tankers,” triggering “severe disruptions, particularly penalising Asian energy importers.” The wider point is that this pressure is no longer confined to one route: Turkey regulates military passage under the “1936 Montreux Convention,” “a power actively invoked following Russia's 2022 invasion of Ukraine,” while the “narrow Danish Straits” are described as the “primary, highly” constrained outlet from the Baltic, underscoring how strategic control and physical bottlenecks now overlap across multiple corridors.
That is why the CSG’s intervention signals a threshold moment, not just another alarm. “This is the first time in its six year history that the association has made a public intervention,” and it comes after “Recent Houthi missile strikes… have turned this transit into an active combat zone,” forcing “over 70% of Suez Canal traffic to detour,” while the diversion via “South Africa's Cape of Good Hope” adds “4,000 nautical miles” and “inflicts a heavy economic toll, costing global trade $10.7 billion annually in delays and $3.4 billion in elevated freight costs.” At the same time, the Strait of Malacca “handles over 94,000 ship crossings annually,” carries “60% of global maritime trade,” and is “nearing its capacity limits,” with the corridor expected to “exceed safe operational” thresholds, reinforcing the sense that maritime disruption is becoming a system-wide stress test rather than a series of isolated shocks.
Shadow Fleets Divide the Seas
Sanctions and rising risks have split maritime trade into transparent and shadow lanes, fueling a two-tier system where compliance drives up costs and opacity enables continued movement.
The sorting mechanism is visible in the warning itself: CNBC’s headline, “CSG Warns 18 Nations: Shadow Fleet Fuels ‘Two‑Tier’ Shipping Threat Amid Hormuz Blockade Crisis,” describes a market in which risk and compliance no longer apply evenly. In that warning, 18 major maritime nations issued a joint declaration via the Danish maritime authority warning that wars and tensions are structural, not temporary, reinforcing the idea that this is a durable sorting process rather than a passing shock. As routes become, in Javier Morodo’s phrase, “instrumentos de influencia y de riesgo,” ships that need recognized insurance, reporting, and legal cover are pushed toward a transparent regulated lane, while vessels willing to operate through sanctions exposure and weaker scrutiny migrate into a shadow lane built on opacity.
That split hardens when oversight is uneven, because the shadow side can keep moving outside normal safeguards while the compliant side absorbs the cost of staying visible. Javier Morodo describes “cientos de barcos” operating “fuera de los marcos de seguros, seguridad y transparencia,” and notes that “La tarifa al contado de un contenedor de 40 pies ya superó los $7,000 dólares, su nivel más alto desde 2024, y eso ocurre con el sistema todavía en pie,” a sign that the two tiers are functioning simultaneously rather than as a brief dislocation.

Rerouting Is Now Standard Practice
Years of war and pandemic have conditioned the shipping industry to treat long detours and fractured routes as routine, embedding inefficiency and volatility into the global supply chain.
The shift toward fragmented maritime trade predates Hormuz because the operating environment had already been remade by successive shocks that taught carriers, traders, and states to live with detours and exceptions. YWR: Your Weekend Reading says flatly, “Current situation started in 2022,” when “The Russia-Ukraine War and sanctions on Russia increased energy ton-miles by 7%,” and that adaptation hardened as routes stretched: “It used to be a 6,000km route to send oil to to Asia, now using the Egypt Sidi Kerir route around Africa it is a 12,000 km route.”
Red Sea violence then deepened habits that were already forming, turning rerouting from an emergency response into a repeated feature of trade. The John Batchelor Show describes the Houthis closing Bab el-Mandeb and forcing Saudi flows toward Suez and around Africa, while attacks also hit the east-west pipeline and Yanbu line; in that setting, it claims that “only about half of the petroleum…is now down by half,” with “every day about 11 or 12 million barrels aren’t getting out,” which “is building up and building up in the world market.”

Oil and Freight Face Systemic Shock
Hormuz disruptions are driving up oil prices and insurance costs, while critical flows of refined products and crude are being rerouted, straining supply chains and threatening economic growth.
The effect is plainly large enough to move benchmark prices, not just shipping schedules. Investment News notes that the Strait of Hormuz “carries approximately one-fifth of the world's daily oil supply,” while Wood Mackenzie estimates a “prolonged closure of the strait could push Brent crude toward $200 per barrel by year-end 2026” and cut U.S. GDP growth to below 1 percent; even before any full closure, David Osler, cited by Lloyd’s List via Insurance Business, says “war risk insurance is adding as much as $8 to the price of a barrel of crude oil amid the Iran conflict.”
The supply-chain hit is similarly material because the chokepoint carries refined products that feed transport and industry, not just crude. In FreightWaves, a speaker described “upwards of 20 million barrels a day of crude oil and refined products transiting through that waterway,” including “Jet fuel exports… had been about 600,000 barrels a day, while… diesel exports had been 1.2 million barrels a day,” and said restrictions had already forced diversions through pipelines—evidence that disruption raises freight and energy costs while undermining availability, reliability, and broader growth planning.