J&j’s ottava topples intuitive’s robotic surgery monopoly
The gist
Johnson & Johnson’s Ottava has shattered Intuitive Surgical’s two-decade reign, igniting a fierce new era in robotic surgery—and investors are feeling the shockwaves.
What to know
- The FDA granted de novo clearance to J&J’s Ottava system, ending Intuitive’s 20+ year monopoly and setting a new regulatory benchmark for future rivals.
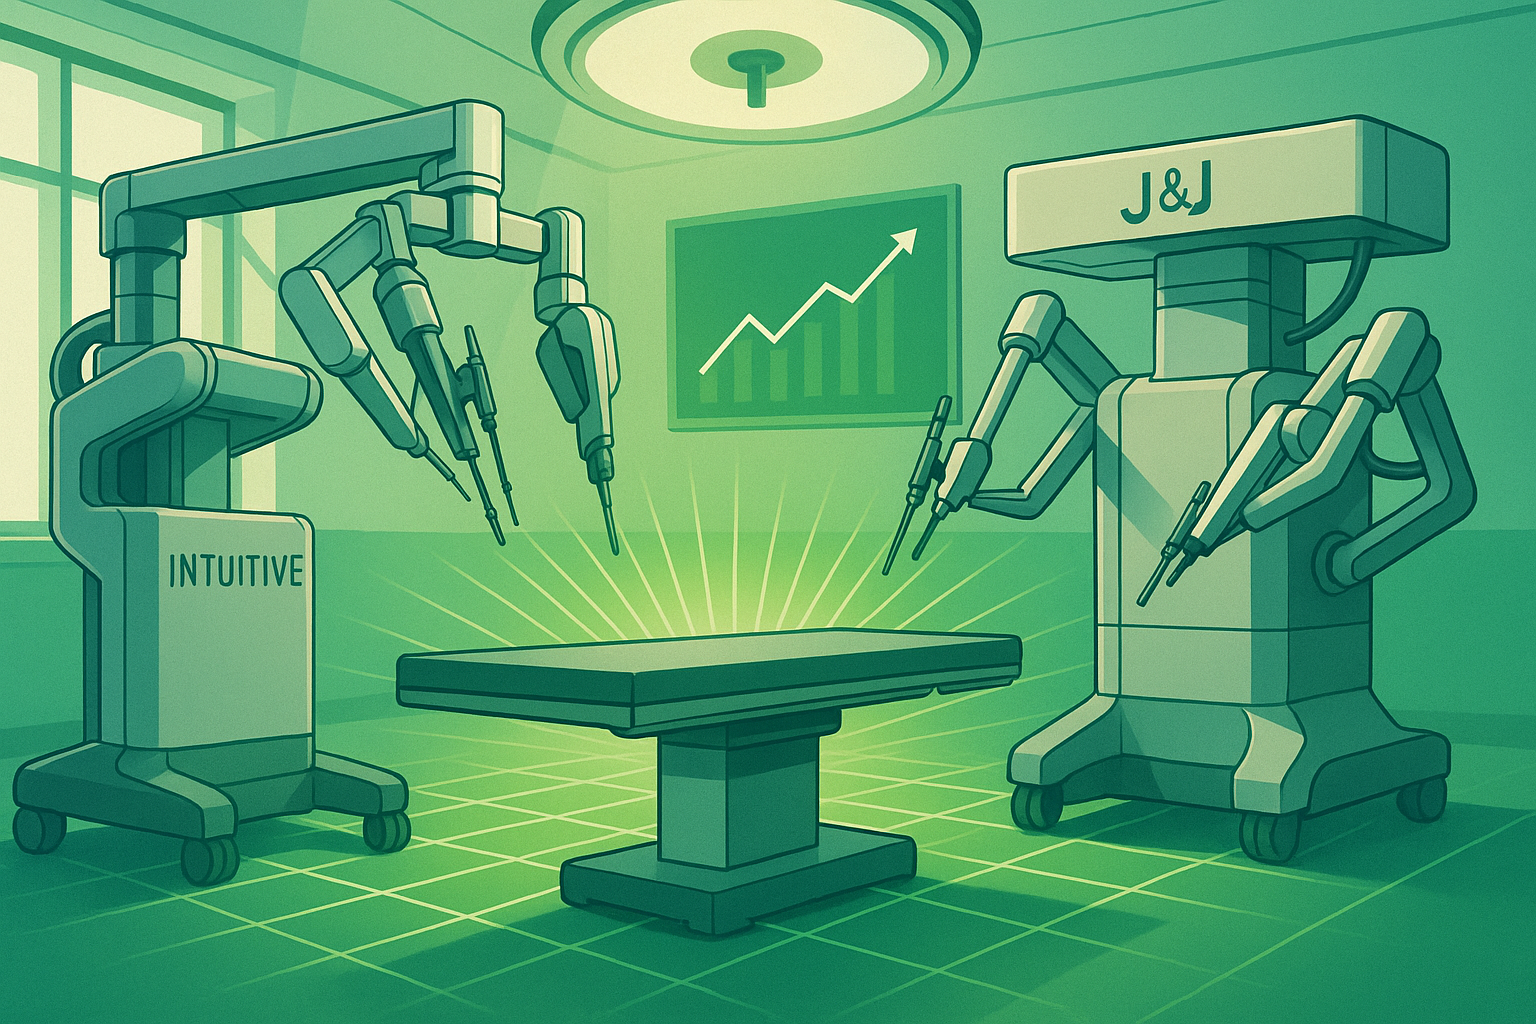
- Ottava’s sleek, table-integrated robot cuts the OR footprint by up to 50%, directly challenging Intuitive’s bulky da Vinci systems and targeting high-volume benign procedures.
- Intuitive’s stock has nosedived 40-45% on fears of market share loss, slower growth, and product recalls, with major analysts slashing price targets despite its massive installed base.
Ottava Sets New Surgical Standard
J&J’s Ottava not only breaks Intuitive’s monopoly but also redefines the entire robotic surgery category with its table-integrated design, forcing future rivals to measure up to a new regulatory and technological benchmark.
Johnson & Johnson's Ottava system achieved a landmark regulatory breakthrough by receiving FDA de novo authorization, effectively ending Intuitive Surgical's more than two-decade monopoly in soft-tissue robotic surgery. This de novo clearance not only approves Ottava for multiple upper-abdominal general surgery procedures—such as gastric bypass and cholecystectomy—but also establishes a new device classification, setting a precedent that future competitors must follow by demonstrating substantial equivalence to Ottava's design under the 510(k) pathway. As J&J's Global Head of Robotics & Digital R&D Neda Cvijetic emphasized, 'There is no precedent here,' underscoring the system's category-defining status.
Ottava's innovative design integrates four fully motorized robotic arms directly into a standard surgical table, a structural departure from the bulky cart- or boom-mounted systems typified by Intuitive's da Vinci. This table-integrated architecture reduces the operating room footprint by 30 to 50 percent, enabling Ottava to fit into virtually any OR worldwide and offering greater flexibility and efficiency. Cvijetic highlighted that the arms can 'fully stow under the table while maintaining full clinical reach,' a technological advancement that not only streamlines workflows but also lays the groundwork for continuous digital and software innovation through advanced sensors and spatial awareness.
Beyond its mechanical innovations, Ottava leverages Johnson & Johnson’s extensive surgical instrumentation expertise and digital ecosystem, Polyphonic, to enhance surgical outcomes and learning. This positions Ottava not merely as a robotic system but as a platform for ongoing innovation and multi-specialty applications, signaling J&J’s strategic intent to challenge Intuitive Surgical’s dominance with a comprehensive, integrated approach that blends hardware, software, and clinical science.
The Battle for OR Supremacy
Intuitive’s entrenched da Vinci network faces its first true challenger as hospitals weigh Ottava’s compact, flexible system against legacy dominance, signaling a dramatic shift in how surgical robots will be adopted and evaluated.
Johnson & Johnson's Ottava system has decisively disrupted Intuitive Surgical's longstanding dominance in soft-tissue robotic surgery by targeting high-volume, cost-sensitive benign procedures such as cholecystectomy and hernia repair—areas where Intuitive has recently focused its lower-priced XiR system strategy. Ottava’s innovative table-integrated design, occupying 30% to 50% less space than traditional cart-based systems, offers hospitals a compelling alternative that challenges the sprawling footprint of Intuitive’s da Vinci platform, signaling a strategic pivot in market dynamics and competitive positioning.
Despite this intensified competition, Intuitive Surgical retains formidable advantages through its entrenched installed base of over 11,700 da Vinci systems worldwide and a robust surgeon training network cultivated over 25 years, which JPMorgan analyst Robbie Marcus highlights as a key factor sustaining physician preference. However, as hospitals refresh equipment and incentivize surgeons to train on competing platforms, the durability of Intuitive’s moat is increasingly questioned, prompting the company to proactively defend its turf by expanding XiR placements—reaching approximately 130 systems including 20 in ambulatory surgery centers last quarter—and extending instrument lifespans to reduce procedural costs.
The competitive landscape has shifted from speculative threats to tangible rivalry with well-capitalized entrants like J&J and Medtronic holding FDA clearances, forcing Intuitive Surgical to temper its growth outlook to 13–15 percent for 2026 amid decelerating US procedure growth and industry headwinds. While Intuitive’s razor-and-razor-blade model continues to generate steady disposable instrument revenue, analysts caution that this alone may not justify the company’s historically high valuation multiples, reflecting a market recalibration as investors price in the gradual rollout of Ottava and the evolving pace of hospital adoption.
Intuitive’s Moat Under Fire
Investors are slashing Intuitive’s valuation as Ottava’s arrival and slowing procedure growth threaten the company’s historic premium and expose cracks in its once-unassailable market position.
Investor sentiment toward Intuitive Surgical has soured markedly following Johnson & Johnson's FDA De Novo clearance of the Ottava system, which ended Intuitive's two-decade quasi-monopoly in soft-tissue robotic surgery. This regulatory breakthrough, coupled with Intuitive's conservative growth guidance and decelerating U.S. procedure volumes, has precipitated a sharp 40-45% decline in its share price from recent highs, reflecting heightened concerns over market share erosion and a more contested growth outlook.
Despite Intuitive Surgical's strong quarterly earnings beats, investor confidence remains tempered by valuation challenges and mixed analyst reactions. Price targets have been slashed—JPMorgan lowered its target from $550 to $450, Wells Fargo from $654 to $487—and while 71% of analysts still maintain Buy ratings, firms like HSBC have downgraded to Hold citing near-term growth uncertainties. This divergence underscores the market's struggle to reconcile Intuitive's entrenched installed base with the emerging competitive threats posed by J&J's Ottava and Medtronic's Hugo systems.
Intuitive Surgical's premium valuation, trading at 30-40 times earnings, is increasingly questioned as investors weigh its 15% compound annual growth rate against intensifying competition and slowing procedure growth. The once-assumed durability of its competitive moat is under scrutiny, given hospitals' equipment refresh cycles and surgeons’ willingness to train on rival platforms if incentivized. While the razor-and-razor-blade model provides steady consumable revenue, it no longer guarantees high growth, prompting concerns about potential valuation compression if growth disappoints.
Compounding these valuation and competitive pressures are operational and governance risks that have unsettled investors. The ongoing Class II recall of da Vinci SP Instrument Arm Drapes affecting over 11,000 units, alongside recent bylaw amendments limiting shareholder influence, have introduced fresh concerns about product quality and corporate governance. These developments may disrupt surgical workflows and procedure volumes, reinforcing cautious analyst forecasts and adding complexity to Intuitive’s risk profile amid an already volatile market environment marked by nearly 58% annualized stock volatility.