Mortgage rate spike turns homeownership into a money pit
The gist
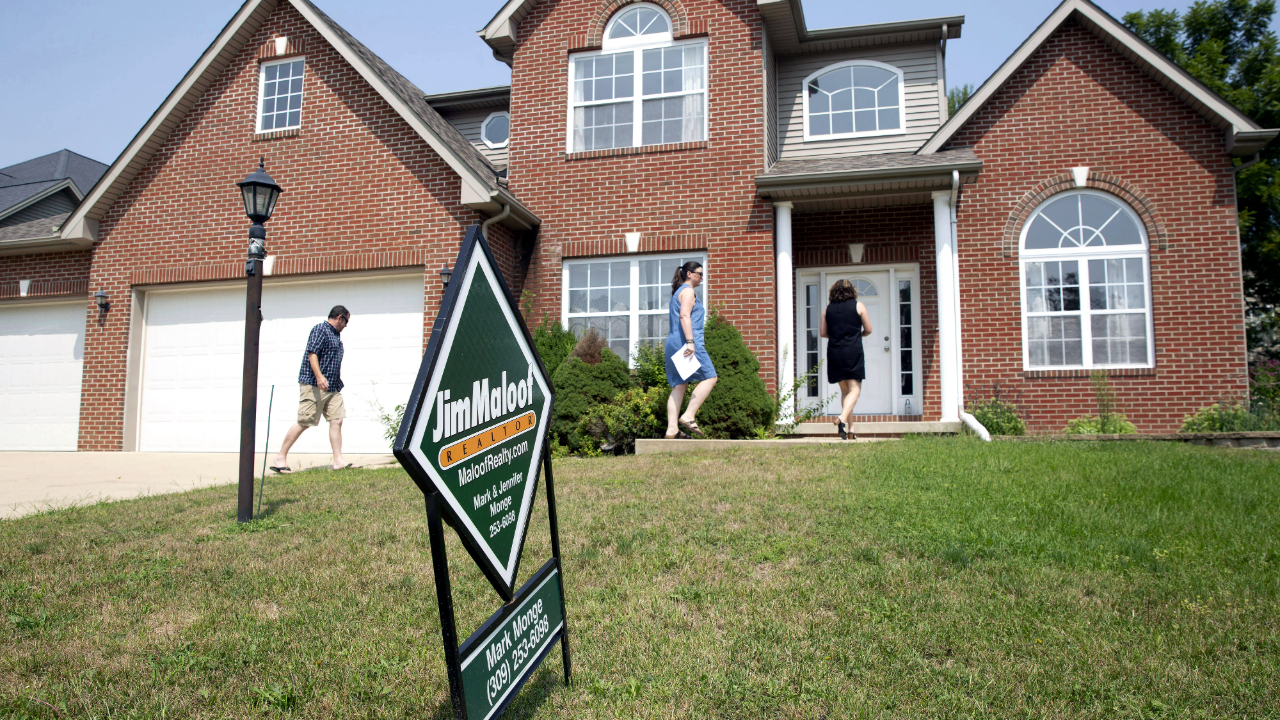
With mortgage rates above 7%, buying a home has doubled in cost since 2021—turning the American Dream into a financial minefield.
What to know
- The Fed’s pandemic-era support for mortgage-backed securities kept rates low until tapering began in November 2021, unleashing a spike to 7%+ by 2026.
- Median monthly mortgage payments now top $2,000—plus soaring taxes, insurance, and maintenance that push real costs much higher than advertised.
- In 41 of the 50 largest metros, renting is now cheaper than owning, and buyer demand has plunged 19% as high rates and hidden costs drive buyers to the sidelines.
Fed's Mortgage Lifeline Ends
The Federal Reserve's massive pandemic-era buying spree in mortgage-backed securities kept rates artificially low—until it abruptly reversed course in late 2021, setting the stage for today's affordability crisis.
The pandemic-era mortgage backdrop began with direct Federal Reserve intervention in agency mortgage-backed securities, aimed not at housing demand broadly but at keeping mortgage finance functioning during the COVID-19 shock. On March 15, 2020, the Federal Open Market Committee announced it would purchase “at least $200 billion of agency mortgage-backed securities to stabilize the market and support credit flows during the COVID-19 financial shock,” and the stated effect was to restore market functioning and lower mortgage funding costs, a channel that helped suppress mortgage rates during the emergency period.
That support did not remain static: the intervention “expanded through April 2020 with approximately $580 billion of MBS purchased,” showing how aggressively the Fed scaled up its backstop before later reversing course. The turn came in November 2021, when the Federal Reserve began tapering its agency mortgage-backed securities purchases; on November 3, 2021, it said it would “reduce asset purchases by $15 billion per month, including $5 billion in agency MBS,” which formally started the withdrawal of pandemic-era monetary support that had been suppressing mortgage rates.
Hidden Costs Crush Buyers
Monthly payments have doubled in five years, but taxes, insurance, and repairs push real homeownership costs even higher—pricing millions out and freezing sellers with low-rate mortgages.
By fall 2026, the affordability math had turned brutal: Graham’s Newsletter estimated that “for every 1% increase in housing rates, home affordability goes down by 10%,” and that each 0.25-point rise prices out another 1.4 million buyers almost instantly. Morgan Stanley’s Sarah Wolfe described a “higher-cost, tighter-supply environment” where “small changes in rates have outsized effects on affordability,” and Morgan Stanley Research put the result plainly: a median-priced buyer now faces a monthly payment of about $2,000, “roughly double the carrying cost from five years ago.”
That financing shock is only the starting point, because the monthly bill buyers must actually carry runs well beyond principal and interest. Graham’s Newsletter calculated that on a $398,000 home with 20 percent down, the mortgage payment is $1,954 a month, but “once you add in taxes, insurance, and repairs, you are looking at nearly $2,700 a month”; qualifying requires $106,000 in annual income, while “the average American family is currently $23,000 short,” a gap that helps explain why Wolfe says owners are “reluctant to sell and take on a new mortgage with a higher interest rate.” Wolfe added that “The jump in financing costs is also freezing sellers,” noting that “about 70% have mortgage” rates below current levels.
True Cost Exceeds the Mortgage
Skyrocketing utility bills, insurance hikes, and relentless maintenance make homeownership far pricier than most buyers realize, with expenses climbing much faster than incomes.
Affordability is breaking down because buyers are underwriting the whole monthly burden, not just the loan payment. On Power House, a speaker contrasted “actual affordability versus perceived affordability,” arguing that even if someone “can get into a home right now at a 6% rate and they could afford the note,” the real test is the “total cost of ownership” — commuting, energy bills, reserves for upgrades on an older home, and other recurring costs that sit outside principal and interest but still determine whether a household can carry the home. It points in particular to “property taxes and insurance costs and the insurance crisis,” and adds that “utility costs which are going up on average 18% to 70%,” arguing these increases worsen affordability.
That broader burden is no longer theoretical: The Compound relayed a buyer’s June 2024 verdict — “holy [__] is this home a money pit” — before listing a $2,500 water heater, a $12,000 roof, and later major HVAC and renovation bills. Other analyses show why these shocks now hit harder: the “5% rule” folds in property taxes, maintenance, and the cost of capital by taking home price times 5% and dividing by 12; meanwhile, Chrisman Commentary reported homeowner’s insurance up 24%, property taxes up 30% between 2020 and 2024, and renovation costs up 50% post-pandemic.



Renting Wins in Big Cities
Incomes can't keep up as home payments swallow a third of paychecks, making renting the clear financial winner in 41 of America's 50 largest metro areas.
For many households, the rent-versus-buy decision is no longer close: as one speaker on Trends put it, “when you think about affordability, the the high price of the homes, uh mortgage rates back towards 7%,” “the math certainly does favor renting over owning.” That shift is showing up in market behavior, not just sentiment, with Briefs Finance noting, “We are officially in a buyer's market in 41 out of the 50 largest metro areas in the United States,” as buyers keep stepping back from ownership math that no longer works on monthly cash flow.
The reason renting now wins in so many metros is that ownership costs have outrun incomes: Briefs Finance says, “The same median house costs 27% more than it did in 2021 while the monthly payment costs 90% more.” In 2021, median household income was around $70,000 a year, and homeownership ate about 20% of the monthly paycheck; today median income is around $80,000, but that same median house now takes about 33% of monthly income, helping explain why Realtor.com could report, “Realtor.com Finds Austin Renters Save $1,917 Monthly, Biggest Gap in Nation.”
Refinance or Bust Mindset
Most recent buyers admit their mortgages are only sustainable if rates fall—leaving the market fragile and purchase demand in a tailspin above 7%.
The demand pullback is showing up not just in market data but in buyer psychology. Truework’s survey of 1,000 recent U.S. homebuyers found that “73 percent of recent buyers planned to refinance,” while “Eight-five percent now say refinancing within three years matters to their financial health, up sharply from 56 percent a year ago,” and half say their mortgage becomes unsustainable without a lower rate; Truework calls this “Conditional Affordability,” “A mortgage that works today, but only as long as something else goes right,” with “88 percent” saying a common setback could put payments at risk and first-time buyers especially exposed. First-time buyers report the highest strain, with 87 percent saying they’ll need to take financial action if they can’t refinance.
That fragility is already translating into weaker purchase activity as rates move into the 7% range. HousingWire said “the housing market's facing headwinds because uh rates are over 7%” and that “New listings data fell noticeably. Pending salesf followed,” while also arguing the pattern is familiar: “2023 um when mortgage rates went from 7.27 all the way down to 5.99… But then rates went up to 7%. That was it,” a threshold effect echoed by the Mortgage Bankers Association’s reported 19% plunge in purchase applications as the 30-year rate neared 7%.