Nvidia’s $500b AI financing push draws bubble fears
The gist
Nvidia is turning AI chip infrastructure into a $500 billion Wall Street-backed asset class—but its high-stakes financial engineering is stoking fears of an AI bubble and market shakeout.
What to know
- Nvidia has mobilized over $500 billion in AI infrastructure financing alongside Apollo, BlackRock, and Goldman Sachs, transforming GPUs into a securitized, revenue-generating asset.
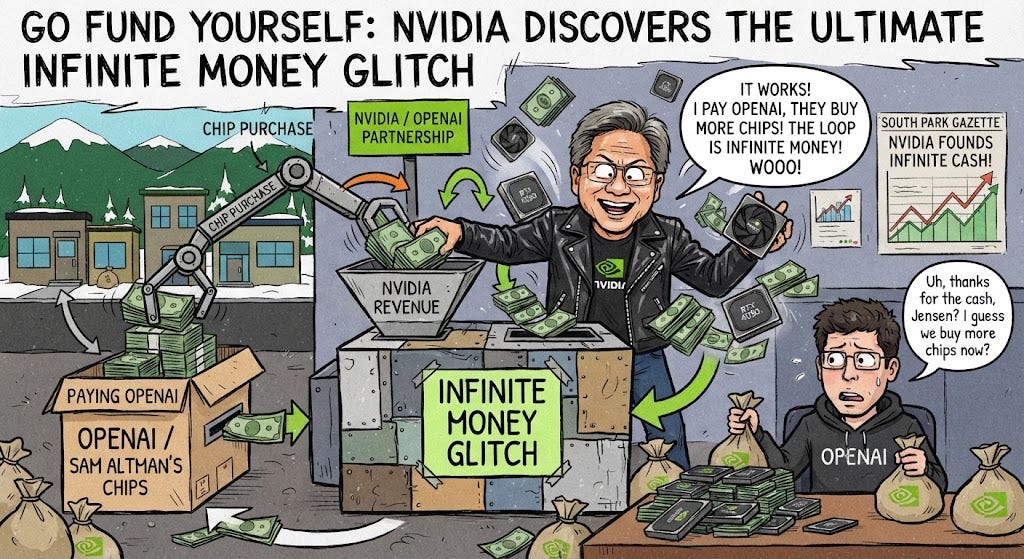
- Acting as both chip supplier and financier, Nvidia is underwriting massive deals—like a $105 billion credit guarantee for OpenAI’s Ohio data center—while investing $53 billion in AI startups and infrastructure.
- Market volatility and bubble warnings are rising as Nvidia’s circular financing model inflates revenues and exposes investors to complex risks reminiscent of late-90s telecom busts.
Wall Street Meets Silicon
Nvidia’s financial engineering turns GPUs into tradable, revenue-backed assets, unlocking institutional capital and reshaping AI infrastructure into a standardized investment class.
Nvidia has pioneered a groundbreaking financial innovation by securitizing AI compute infrastructure, partnering with Wall Street giants such as Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs, and KKR to mobilize over $500 billion in third-party capital. This initiative transforms AI compute from rapidly depreciating IT equipment into a revenue-generating, fungible asset class with residual value, supported by continuous software improvements like CUDA that extend hardware utility across workloads and customers. By creating independent financing platforms and leveraging its superior telemetry to set smart residual value guarantees—covering up to 25% of qualifying transactions—Nvidia effectively lowers financing costs and enables institutional investors to treat GPUs akin to aircraft or telecom infrastructure assets, thereby significantly raising the ceiling on AI infrastructure spending.
The financial structuring underpinning Nvidia’s AI infrastructure financing incorporates innovative elements such as circular vendor financing, residual value guarantees, and revenue-sharing models that create a self-reinforcing ecosystem where Nvidia acts simultaneously as chip supplier, financier, and investor. For example, Nvidia provides capital to startups like Neo Cloud, which then allocate a substantial portion of that funding back to purchasing Nvidia chips, generating a novel revenue and financing loop that supports compute fungibility and demand creation. This approach, combined with Nvidia’s development of open ecosystems like the 800 VDC power distribution architecture and the DSX platform blueprint, facilitates scalable AI factory deployments and vendor diversity, further solidifying AI compute as a financeable, investable infrastructure asset class.
By redefining AI compute infrastructure as a standardized, multi-layered asset class—bundling enforceable revenue streams, power contracts, site access, hardware warranties, and operating rights—Nvidia and its financial partners create repeatable financing channels familiar with Nvidia’s technology and deployment standards. This structure enables AI labs, cloud operators, and enterprises with limited balance sheets to access capital markets similarly to traditional infrastructure sectors like energy and telecommunications. Nvidia’s role extends beyond chip manufacturing into shaping the financial architecture of AI, effectively acting as a 'central bank' of AI compute by orchestrating capital flow, underwriting risks, and providing residual value support, which collectively enhance investor confidence and drive higher valuations in this nascent asset class.

Bubble Risks and Bottlenecks
Nvidia’s circular financing model raises chip prices and echoes past vendor-financed bubbles, while rapid tech shifts threaten to strand billions in GPU-backed assets.
Nvidia's $500 billion AI infrastructure financing initiative is poised to tighten AI chip supply and drive up enterprise costs in the near term, with analysts like Mark Tauschek projecting a 15%-20% price increase. This financing model prioritizes long-term financial commitments over immediate purchasing power, creating a queue for chip capacity that may disadvantage enterprises needing rapid access. While additional fabrication capacity may alleviate constraints by 2028, companies reacting to current demand pressures will face higher prices and scarcity.
The systemic risks embedded in Nvidia's financing strategy echo historical vendor financing bubbles, notably the late 1990s telecom sector, where aggressive vendor-backed loans led to massive bad debts and bankruptcies. By securitizing GPU cash flows and mobilizing over $500 billion in third-party capital through partners like Apollo, BlackRock, and KKR, Nvidia has created a complex web of circular financing where it acts simultaneously as vendor, financier, investor, and guarantor. This circularity inflates revenue figures based on vendor-backed credit rather than independent demand, raising concerns about a potential AI infrastructure bubble fueled by credit expansion.
A critical vulnerability lies in the risk of stranded GPU assets due to rapid technological shifts and evolving AI architectures. Jensen Huang himself acknowledged that if new AI architectures supplant GPUs, securitized GPU assets could become obsolete overnight, reminiscent of the 'dark fiber' glut after the dotcom crash. Although Nvidia offers residual value guarantees covering up to $125 billion to protect lenders, this creates concentrated risk on Nvidia's balance sheet, especially as major AI players like OpenAI and Anthropic diversify away from CUDA-dependent chips, potentially squeezing Nvidia's profits and destabilizing the financing ecosystem.
The financing ecosystem's complexity—featuring neoclouds, long-term contracts, GPU-backed special purpose vehicles, and emerging GPU rental futures—forms a highly leveraged and interconnected 'tinderbox' where a single disruption could cascade into widespread instability. Nvidia's scaling back of guarantees for projects like the OpenAI Ohio data center from $250 billion to under $120 billion signals growing caution amid profitability concerns and market vulnerabilities. As Nvidia's risk profile shifts from chip sales to the sustainability of its AI investments, the intertwined financial health of Nvidia and its customers amplifies systemic risk, with failures potentially triggering tightening credit conditions and significant market losses.

Nvidia’s Closed-Loop Empire
By fusing chip supply, financing, and direct investment, Nvidia creates a self-reinforcing ecosystem that blurs the lines between vendor, landlord, and infrastructure partner.
Nvidia has strategically transformed from a pure chip supplier into a major financier and infrastructure partner within the AI ecosystem, directly investing approximately $53 billion across 170 AI startups and collaborating with leading financial institutions such as Apollo, BlackRock, and Goldman Sachs to mobilize over $500 billion in AI infrastructure financing. This evolution positions Nvidia not only as a hardware vendor but also as a guarantor and anchor tenant in massive AI data center projects, exemplified by its $105 billion credit guarantee and $1.5 billion equity investment in SB Energy’s Ohio AI campus, where it secures critical resources like land and power.
By integrating chip supply with infrastructure financing and development, Nvidia creates a closed-loop ecosystem where its investments in AI startups and infrastructure developers generate demand for its GPUs, which in turn fuels further revenue growth and financial capacity to underwrite more projects. This feedback loop is evident in partnerships with companies like CoreWeave and Nebius, which rely exclusively on Nvidia hardware, and in Nvidia’s role as both landlord and utility financier, as seen in its $2 billion stake in energy infrastructure developer Lancium, effectively blurring the line between vendor and joint venture partner.
Nvidia’s innovative financial structuring aims to reframe AI compute infrastructure as a durable, income-generating asset class attractive to long-term institutional investors such as pension funds and insurers seeking steady, infrastructure-like cash flows. Through strategic alliances with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs, and KKR, Nvidia is orchestrating financing platforms to mobilize over $500 billion in third-party capital, pledging to back up to 25 percent of deals with its own capital, thereby reinforcing its control over AI compute ecosystem growth and shaping demand on a global scale.
While Nvidia’s expanding role as financier and infrastructure partner strengthens its ecosystem dominance, it introduces strategic ambiguity and investor scrutiny regarding whether its massive financial commitments are driven by visionary foresight or necessity to ensure project viability. The recalibration of its Ohio data center commitment from $250 billion to below $120 billion underscores the scale and complexity of underwriting AI infrastructure at sovereign budget levels, highlighting Nvidia’s unique position as both the supplier of AI’s 'picks and shovels' and the guarantor of the AI gold rush’s physical foundation.
Investor Jitters and Transparency
Despite massive Wall Street backing, Nvidia’s complex guarantees and circular revenue loops fuel market volatility and skepticism over the true durability of AI infrastructure bets.
Nvidia’s $500 billion AI infrastructure financing initiative significantly broadens retail and institutional investor exposure to AI compute assets by mobilizing third-party capital through partnerships with major Wall Street firms such as JPMorgan Chase, Goldman Sachs, and Apollo Global Management. This symbiotic relationship leverages financial expertise and Nvidia’s technological leadership to influence market dynamics, while reactions from other tech players like CoreWeave and Supermicro will further shape investor sentiment in the broader AI and tech sectors.
Despite the bullish outlook and Nvidia’s framing of AI compute as a long-lived, revenue-generating infrastructure asset akin to electricity or the internet, market skepticism persists. Investor concerns about circular financing—where Nvidia helps its AI partners raise debt that in turn boosts Nvidia’s revenue—have led to volatile stock reactions, including a 4.5% intraday drop following initial reports of a $250 billion OpenAI guarantee and a 2.9% decline erasing nearly $60 billion in market cap on the financing announcement day. These dynamics underscore ongoing uncertainty about the sustainability and valuation of AI infrastructure investments.
Nvidia’s $105 billion guarantee for OpenAI’s Ohio data center deal, substantially lower than earlier estimates, exemplifies the company’s risk-limiting financing structure that supports lease and power payments while guaranteeing infrastructure value only upon lease commencement and tenant default. This contingent obligation clarifies Nvidia’s supply commitments and revenue timing, helping to alleviate investor anxiety by distinguishing between future supply commitments—now reported at $279 billion—and legally binding customer orders, thereby providing a more transparent outlook on revenue streams projected to reach $1 trillion by the end of 2027.
Regulatory easing by the SEC, which excludes certain data center debt from asset-backed security definitions, has facilitated Nvidia’s ability to mobilize over $500 billion in third-party AI infrastructure financing, expanding investor access to this emerging asset class. However, elevated market pricing for data center bonds, such as QTS’s recent $3.9 billion five-year bond priced near 7.63%, reflects cautious investor sentiment. Nvidia argues that its financing model catalyzes data center build-outs that might not otherwise occur, thereby stabilizing chip pricing and availability through secured supply chain commitments and supporting its long-term revenue outlook.