Private credit’s $2 trillion shadow spurs global crackdown after fraud scandal exposes systemic faultlines
The gist
A $2 trillion shadow market is rattling global regulators as a major fraud scandal exposes how private credit’s explosive, opaque growth could threaten the entire financial system.
What to know
- European and U.S. regulators—including the ECB, SEC, and Federal Reserve—are ramping up probes into private credit’s risks after ties to banks, insurers, and pension funds hit historic highs.
- Opaque loan valuations, liquidity constraints, and redemption gates mean investors may face delays or losses if panic withdrawals hit, with nearly $20 billion in redemptions looming.
- The Tricolor Holdings fraud cost JPMorgan $170 million and triggered criminal charges, spotlighting gaping holes in collateral checks and risk controls across the private credit ecosystem.
Regulators Scramble for Control
Global watchdogs are racing to close data gaps and rein in a $2 trillion private credit market whose rapid growth and tangled links with banks and pensions threaten to outpace oversight.
The European Central Bank (ECB) and the European Systemic Risk Board have spotlighted private credit as a burgeoning financial stability risk, prompting considerations of a formal inquiry into the sector’s rapid expansion and interconnectedness with insurers, pension funds, and banks. As ECB supervisory vice-chair Frank Elderson emphasizes, this growing entanglement could amplify vulnerabilities during market stress, underscoring the urgency for enhanced oversight amid the sector’s increasing role in corporate financing and its shift away from traditional banking channels.
Across the Atlantic, U.S. regulators including the SEC, Treasury Department, and Federal Reserve have intensified enforcement and information-gathering efforts targeting private credit managers, reflecting concerns over transparency, valuation practices, and liquidity risks in complex fund structures such as interval funds and nontraded business development companies. Despite these challenges, regulatory initiatives paradoxically aim to expand private credit access—proposing to open the market to 401(k) retirement plans—thereby raising fresh questions about liquidity mismatches and redemption pressures, especially as investors sought to withdraw nearly $20 billion by early 2026 but received only about half.
The private credit sector’s explosive growth—surging more than tenfold since 2009 to an estimated $1.5 trillion to $2 trillion globally—has outpaced regulatory oversight, exposing significant challenges in cross-border coordination, data transparency, and real-time risk management. Authorities are grappling with opaque valuation methodologies, infrequent reporting, and complex indirect linkages between private credit funds and traditional financial institutions, which create layered leverage that complicates monitoring efforts. In response, global regulators are prioritizing enhanced information sharing and collaborative supervision to close data gaps and safeguard financial stability in this rapidly evolving market.

Opacity and Liquidity Risks Mount
Private credit’s secretive deals, self-reported valuations, and redemption gates are fueling systemic risk as retail investors face delayed withdrawals and deteriorating loan standards.
The private credit market's systemic risk is deeply rooted in its pervasive opacity and lack of comprehensive data transparency, which starkly contrasts with traditional credit sectors tracked by regulators like the Federal Reserve. Unlike credit cards or home loans, private credit deals are shrouded in confidentiality due to less stringent disclosure requirements, leaving investors and regulators unable to monitor early warning signs effectively. This opacity extends to loan valuations, which rely heavily on trust in private credit executives' self-reporting, creating a fragile foundation vulnerable to mispricing and hidden distress.
Liquidity constraints imposed by redemption gates in private credit funds exacerbate systemic vulnerabilities by limiting investor access to capital during periods of stress. As Apollo’s president explained, investors can redeem only about 5% of assets quarterly before gates close, meaning that when many seek withdrawals simultaneously, most face delays, intensifying redemption pressures. This mismatch between the illiquid nature of underlying loans and the liquidity expectations of increasingly retail-heavy investor bases—now comprising up to 40% of assets—undermines the market’s match funding premise and fuels investor anxiety, potentially triggering contagion effects as redemption requests ebb and flow.
The private credit sector’s deteriorating underwriting standards and concentrated lender groups amplify refinancing risks that could precipitate broader financial instability. By 2025, underwriting was described as the worst in 25 years, with sectors like software and AI-driven companies facing accelerated repricing pressures that challenge loan survivability. This creates a fault line where valuation opacity and refinancing difficulties converge, potentially triggering contagion without a classic wave of defaults. The growing interconnectedness with banks—whose commitments to private credit vehicles surged from $8 billion in 2013 to $95 billion in 2024—further raises the stakes, as stress transmission channels through credit lines and leverage could magnify systemic risk despite currently contained exposures.
Market sentiment and investor behavior are increasingly driving systemic risk in private credit, evidenced by Moody’s negative outlook on US Business Development Companies (BDCs) amid rising leverage and redemption pressures. Public proxies like listed BDCs trading at their deepest discounts to net asset value in over five years highlight valuation challenges, while fundraising declines—such as a 45% year-on-year drop in private credit funds targeting wealthy individuals—signal tightening liquidity. This dynamic underscores the necessity for investors to adopt a long-term perspective focused on rigorous manager selection and underwriting quality to navigate the sector’s opaque and structurally vulnerable landscape.
Tricolor Scandal Exposes Systemic Flaws
Major banks were blindsided as Tricolor’s repeated collateral pledges and executive fraud revealed deep weaknesses in audit controls and risk checks across the private credit ecosystem.
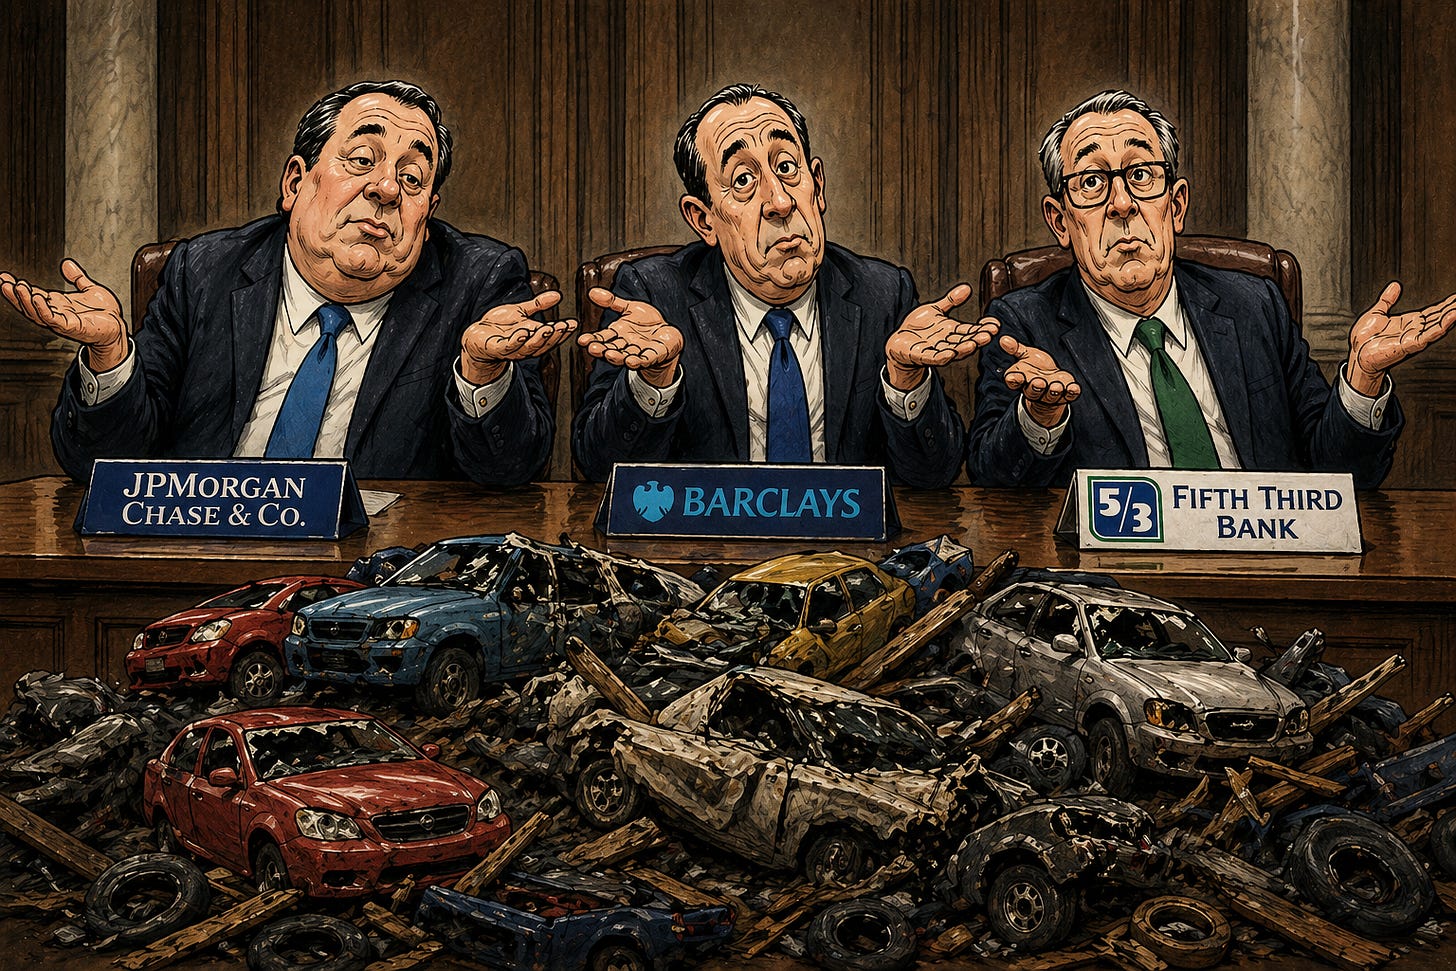
The Tricolor Holdings scandal starkly exposes critical oversight failures within major banks such as JPMorgan Chase, Barclays, and Fifth Third Bank, which financed and marketed securities backed by Tricolor’s loans despite glaring audit red flags. Investors allege that Tricolor repeatedly pledged the same collateral to multiple lenders and even collateralized loans already in default, revealing systemic weaknesses in collateral verification and risk assessment processes that allowed such deceptive practices to flourish unchecked.
The fallout from Tricolor has been severe, with CEO Daniel Chu and other top executives formally charged with fraud, highlighting the potential for sophisticated deception in private credit deals that banks failed to detect. JPMorgan Chase CEO Jamie Dimon publicly acknowledged the bank’s failures, calling the episode “not our finest moment” after absorbing a $170 million loss, underscoring both the reputational damage and financial risks tied to inadequate due diligence and oversight in this rapidly expanding sector.
In their defense, the implicated banks claim they were blindsided by Tricolor’s collapse, raising profound questions about the effectiveness of existing audit and verification frameworks in private credit financing. As a judge weighs these defenses, the case spotlights how current regulatory and internal controls may be insufficient to detect or prevent fraud, signaling an urgent need for more robust scrutiny and transparency mechanisms to safeguard investors and maintain market integrity.