Private credit’s liquidity squeeze: retail redemption riptide meets institutional staying power
The gist
Private credit’s explosive growth has exposed a widening rift between retail investors desperate for liquidity and steadfast institutions riding out the storm.
What to know
- Private credit assets rocketed from $108 billion in 2007 to over $2 trillion in 2023, with giants like Apollo and Ares leading the charge.
- Quarterly liquidity promises in semi-liquid funds have triggered a retail redemption rush, forcing fund managers to gate withdrawals and mark down loans.
- While over 90% of institutional investors are staying put, retail outflows highlight a fundamental mismatch in liquidity expectations that’s shaking up the market.
Banks Out, Giants In
Private credit firms seized the lending void left by post-crisis banking reforms, scaling up with bespoke loans and legacy inefficiencies that now strain liquidity.
The private credit market's rapid expansion traces back to the post-2008 financial crisis regulatory overhaul, which imposed stricter capital and risk requirements on big banks, curtailing their lending to less-established borrowers and creating a vacuum that private credit funds eagerly filled. Firms like Ares Management, Blackstone, Apollo Global Management, and Blue Owl Capital capitalized on this opportunity by offering tailored, often floating-rate loans with covenants directly to companies, effectively stepping into the role traditional banks abandoned.
From a modest $108 billion in assets under management in 2007, private credit ballooned nearly twentyfold to an estimated $2 to $2.4 trillion by 2023, fueled by capital inflows from pension funds, insurers, and high-net-worth investors seeking alternatives to bank lending. This surge enabled major players like Apollo—managing over $1 trillion with 80% in credit—Ares with $422 billion, Blackstone’s BCRED fund at $79 billion, and Blue Owl at $160 billion to underwrite increasingly larger loans, extending beyond middle-market companies to include big public firms and even Big Tech, which traditionally relied on public bond markets.
Despite its growth and innovation in loan structuring, the private credit industry has largely inherited legacy banking frictions such as multi-day settlement windows, manual reconciliation via agent banks, and the entrenched '2 and 20' fee model, which complicate operational efficiency. Moreover, the semi-liquid and perpetual fund structures that dominate private credit create a fundamental liquidity mismatch: while loans are illiquid and often long-term, fund redemptions settle quarterly or over several days, leading to challenges when investors seek rapid exits, as seen in redemption pressures on Blue Owl and Blackstone funds.
Liquidity Promises Under Fire
Quarterly redemption windows in semi-liquid funds have exposed a critical gap between investor expectations and the true illiquidity of private credit assets, forcing managers to ration exits and mark down loans.
By early 2026, the rapid expansion of private credit funds promising quarterly liquidity exposed a fundamental liquidity mismatch, as simultaneous redemption demands overwhelmed fund capacities. Moody’s Marc Pinto emphasized this as a liquidity crisis rather than a credit crisis, underscoring the tension between investor expectations for regular liquidity and the inherently illiquid nature of private credit assets. This mismatch has forced funds like Blackstone to mark down loans such as Medallia, revealing valuation complexities triggered by forced asset sales during redemption waves.
The introduction of semi-liquid private credit funds targeting retail investors intensified liquidity tensions by blending investor bases with divergent liquidity needs. As Luke Sarsfield of Ridgepost Capital noted, many retail investors misunderstand the 'semi' in semi-liquid, expecting more immediate liquidity than these funds can sustainably offer. Redemption limits, typically capped at 5% per quarter, have been widely adopted to prevent fire sales at discounted prices, protecting long-term institutional investors who often prefer to remain invested during market stress, while retail investors seek quicker exits.
Despite headline-grabbing redemption pressures, industry data reveals that redemptions are concentrated among a small number of large, sophisticated investors rather than broad retail runs. Blackstone and Blue Owl Capital report that over 90% of investors do not redeem, and redemption requests often do not roll forward automatically, requiring resubmission in later windows—effectively rationing liquidity and benefiting those best versed in fund mechanics. This collective liquidity option functions well until redemption demand spikes, at which point gating and prorated redemptions activate, as seen with Blackstone and Oaktree exceeding typical caps but only fulfilling about half of redemption requests.
The rapid retail inflow into evergreen, semi-liquid private credit vehicles has created a structural tension between liquidity promises and the illiquid reality of underlying assets, leading to investor surprise and redemption waves once complexities become apparent. As one analyst put it, many rushed in without fully grasping the liquidity terms, resulting in gating mechanisms and denied withdrawals despite clear disclosures. This mismatch is compounded by valuation challenges tied to internally determined NAVs, creating conflicts of interest and fueling calls for independent third-party valuation to enhance transparency and accountability in these evolving fund structures.

Retail-Institutional Divide Widens
Institutional investors are holding firm while retail investors rush for the exits, intensifying liquidity mismatches and prompting a shift toward private equity and venture capital.
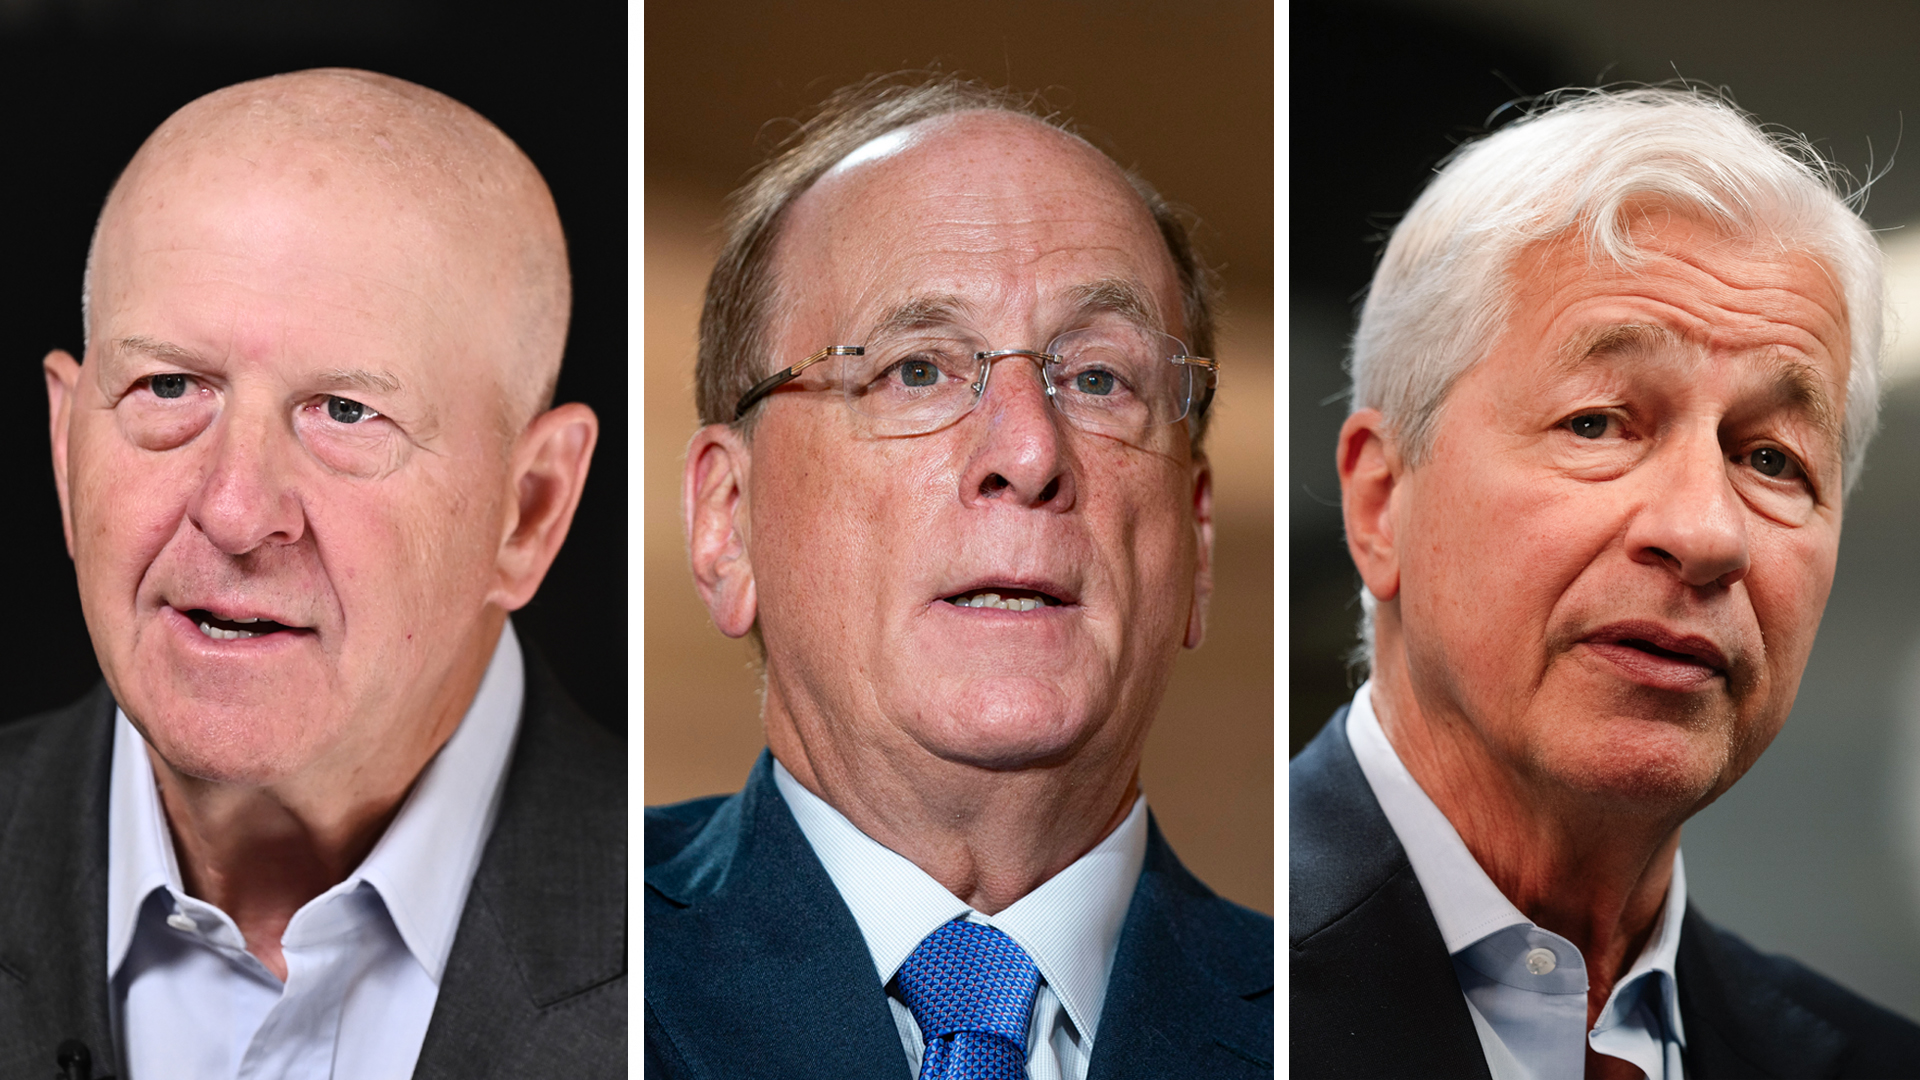
Investor behavior in private credit markets has increasingly diverged between institutional and retail participants. While institutional investors, such as those represented by BlackRock’s Larry Fink and Arcmont’s Anthony Fobel, have maintained or even increased allocations—attracted by wider credit spreads and normalized default rates—retail investors have exhibited heightened redemption activity driven by liquidity concerns and sector-specific risks like potential software defaults linked to AI advances. This divide is underscored by BlackRock’s HLEND fund experiencing redemption requests exceeding 9%, contrasting with over 95% of institutional investors refraining from withdrawals, highlighting a fundamental tension in liquidity needs within mixed investor bases.
The structural design of private credit funds, particularly semi-liquid and evergreen BDCs, has amplified investor tensions as redemption limits—typically capped at around 5% per quarter—seek to prevent forced asset sales at discounted prices. However, many retail investors, often less familiar with these liquidity constraints despite clear disclosures, have rushed to redeem upon realizing the semi-liquid nature of their investments, fueling redemption surges and market anxiety. This dynamic creates a complex balancing act for managers who must reconcile the divergent expectations and behaviors of retail versus institutional investors, as noted by market participants and highlighted by the redemption patterns in funds like BlackRock’s HLEND and Apollo’s US private credit vehicles.
Amid rising concerns over private credit exposures—especially related to software company loans and valuation uncertainties—financial advisors and investors have increasingly shifted their preferences toward private equity and venture capital. Morningstar data reveals that assets in venture capital semiliquid funds nearly tripled in 2025 and continued strong growth into early 2026, fueled by enthusiasm for high-profile companies like SpaceX and OpenAI. This reallocation reflects a broader market sentiment change, with advisors seeking diversification and yield through alternative strategies perceived as offering more favorable risk profiles, thereby driving private credit net assets down by about $1 billion in Q1 2026 while private equity and venture capital funds attracted significant inflows.
Despite media-driven narratives of distress, redemption pressures in private credit remain manageable and concentrated among a small subset of large retail investors, with institutional demand continuing to provide stable capital support. Firms like Ares Management and Blue Owl Capital emphasize that over 90% of investors have not tendered redemptions, and that the sector’s fundamentals remain robust without a significant uptick in defaults, especially among larger borrowers. This nuanced investor behavior underscores the importance of manager selection and credit quality monitoring, while also highlighting a structural mismatch between private credit’s illiquid product design and retail investor expectations, reinforcing the asset class’s alignment primarily with long-term institutional capital.
Resilience, Transparency, and Tech
Fund managers are touting strong fundamentals and adopting blockchain-powered daily settlements to counter redemption fears and operational bottlenecks.
By mid-2026, fund managers like Kevin T. Gannon of Stanger and executives at Ares Management, including co-president Blair Jacobson, actively countered negative narratives about private credit liquidity and stress. They emphasized the structural resilience of funds, record liquidity delivery without gating redemptions, and strong portfolio fundamentals such as low non-accrual rates and steady growth across thousands of companies. Jacobson further argued that higher floating interest rates could enhance returns without triggering widespread credit issues, while a slowdown in capital inflows might promote more conservative underwriting, stabilizing the market amid evolving economic conditions.
In response to investor concerns about valuation opacity and liquidity frictions, major alternative asset managers have increased transparency and broadened their product offerings beyond private credit to include infrastructure, real estate, and private equity. For instance, Ares raised $5 billion in Q1 2026, with $3 billion allocated to U.S. direct lending funds, leveraging diversification to attract a wider investor base and alleviate liquidity pressures. This strategic expansion reflects a deliberate effort to mitigate risks inherent in private credit and adapt to shifting advisor preferences.
Operational innovation has emerged as a critical frontier for addressing legacy inefficiencies in private credit markets, with blockchain technology leading the charge. Apollo’s launch of ACRED in January 2026, which tokenizes a portion of its diversified credit fund across six blockchains to enable daily redemption settlements, exemplifies this shift from traditional quarterly, paper-based processes. This pioneering approach not only enhances liquidity but also signals growing industry recognition that technological solutions can alleviate longstanding operational bottlenecks and investor concerns.
The evolving semi-liquid private credit fund structures have exposed inherent conflicts of interest in NAV valuation processes, where managers wield significant influence over valuations that directly affect their fees and investor transactions. This tension arises because valuation frameworks, originally designed for closed-end institutional funds, are now applied to perpetual vehicles with continuous capital flows and redemptions, transforming valuations into economic and transactional focal points. Industry advocates call for enhanced transparency and accountability through independent third-party valuation firms to incorporate public market signals and reduce investor suspicion, aiming to realign incentives and improve trust in fund valuations.
Institutions Double Down
Despite retail redemptions, institutional allocations to private credit keep accelerating, even as advisors pivot toward tech-driven private equity and venture capital.
Institutional investors have increasingly accelerated their allocations to private credit, drawn by wider credit spreads and attractive risk-adjusted returns, as highlighted by BlackRock chairman Larry Fink and Goldman Sachs CEO David Solomon. Despite retail-focused private credit vehicles like BDCs facing redemption pressures exceeding 5%, institutional demand remains robust, with BlackRock's private credit base being predominantly institutional (85-90%) and Goldman reporting $10.2 billion in allocations through April 2026. This divergence underscores a deepening institutional-retail divide within the private credit market.
While private credit fundamentals remain strong with low default rates and resilient portfolios, as noted by Arcmont CEO Anthony Fobel, recent redemption pressures in semi-liquid private credit funds primarily reflect investor discomfort with illiquidity rather than deteriorating credit quality. Fobel projects the private credit market could expand from $1.8 trillion to €4 trillion by 2030, driven by sustained institutional demand, yet the structural mismatch between product liquidity and investor expectations continues to challenge the sector’s retail appeal.
A notable shift in asset allocation is underway as financial advisors and investors pivot away from private credit toward private equity and venture capital to diversify portfolios amid concerns over credit quality and software sector exposure. Morningstar reports that semiliquid fund assets have more than doubled since 2022, nearing $600 billion by March 2026, with private equity assets growing 12.5% to $90.8 billion and venture capital assets nearly tripling in 2025 and rising another 33.7% in early 2026. This shift is fueled by enthusiasm for high-profile companies like SpaceX, Anthropic, and OpenAI, reflecting evolving investor preferences toward technology-driven growth opportunities.
Despite the growth in semiliquid fund assets, liquidity and fee pressures are mounting, with average fees around 3% and redemption limits—typically capped at 5%—being tested by hard-to-sell private holdings. Leading asset managers such as Blackstone, Cliffwater, Blue Owl, Ares, KKR, and Apollo collectively manage nearly $270 billion in this space, yet Morningstar’s cautious outlook highlights that only 4 of 19 rated semiliquid funds earned Bronze or Silver Medalist Ratings, suggesting few are positioned to outperform peers after fees. This underscores the challenges facing private credit’s maturation within semiliquid structures amid evolving market dynamics.