Retirement income playbook: dividends, super, or annuities?
The gist
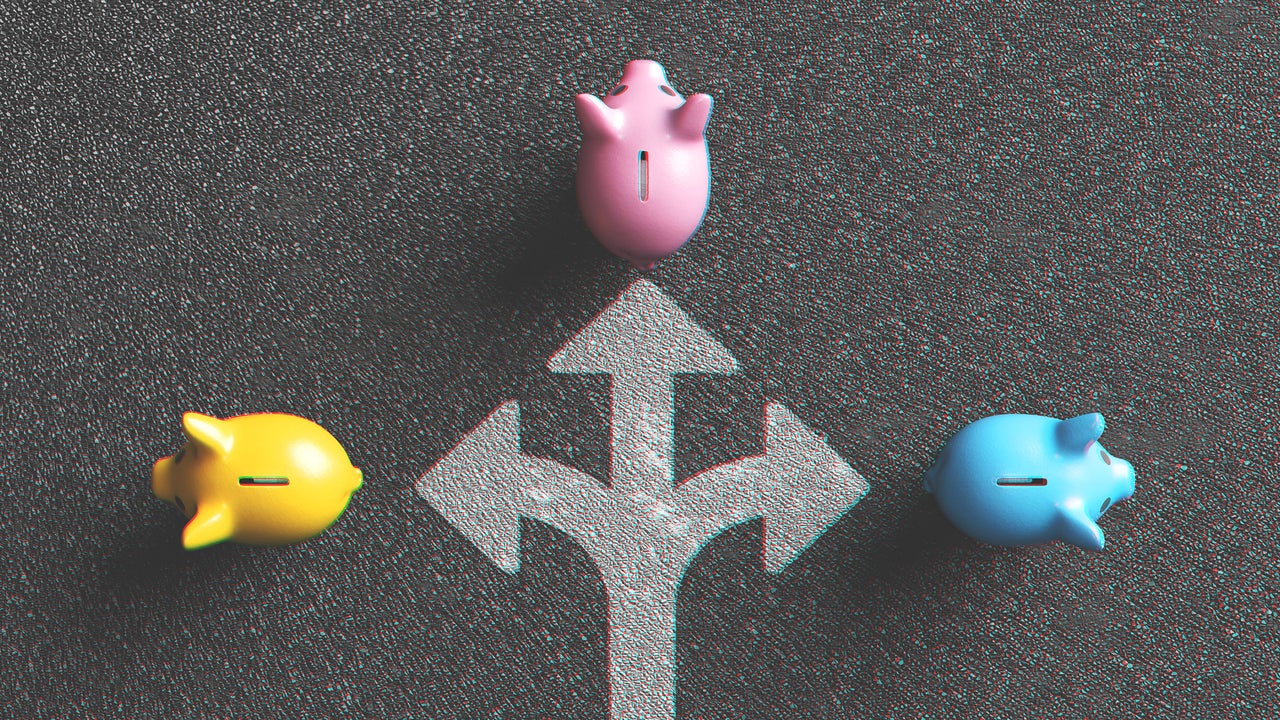
Retirees face a high-stakes showdown between dividend shares, superannuation, and annuities as they hunt for dependable, inflation-proof monthly income.
What to know
- Building a $1–$1.2 million ASX dividend portfolio targeting 5% yield can generate about $5,000 a month—if you dodge dividend cuts and diversify with names like HomeCo, Harvey Norman, and VHY.
- Superannuation turbocharges retirement income with 0% tax in pension phase and juicy franking credits from stocks like Fortescue, Westpac, and Telstra, slashing the capital needed.
- Annuities—especially fixed indexed types with lifetime guarantees—create an income floor that outlasts market swings, with a $930,000 annuity paying roughly $5,650 monthly for life.
Building a Bulletproof Dividend Portfolio
Diversifying across blue-chip stocks and growth-focused ETFs balances yield and risk, while franking credits and dividend growth are critical to sustaining real income in retirement.
Generating a reliable retirement income of around $5,000 per month from ASX dividend shares typically requires a substantial portfolio valued between $1 million and $1.2 million, assuming a balanced dividend yield target of approximately 5%. This yield strikes a prudent balance, offering meaningful income without resorting to high-yield stocks that may carry elevated risk of dividend cuts. Building such a portfolio involves diversifying across higher-yielding shares like HomeCo Daily Needs REIT and Harvey Norman Holdings, alongside dividend-focused ETFs such as Vanguard Australian Shares High Yield ETF (VHY), to manage risk and capture income growth potential.
Dividend growth emerges as a critical factor in preserving purchasing power over time, especially given inflationary pressures that can erode fixed income streams. Combining stocks with solid current yields and those exhibiting consistent dividend growth—such as Suncorp’s forecasted dividend increase to $1.09 by 2030—creates a more resilient income portfolio. This approach is complemented by including companies with frequent dividend payments like Amcor, which offers quarterly payouts, thereby smoothing cash flow for retirees.
Tax efficiency and franking credits significantly influence the net income retirees receive from ASX dividends. Fully franked dividends from major banks like Commonwealth Bank and miners such as BHP Group can substantially offset tax liabilities, sometimes even generating refunds, particularly when invested through superannuation where tax rates are lower or zero in the pension phase. This tax advantage reduces the capital required to achieve income goals, making stocks with high franking credits, like Telstra with its 6.1% grossed-up yield, particularly valuable components of a retirement income portfolio.
Constructing a durable ASX dividend portfolio demands a long-term, disciplined investment strategy centered on diversification across sectors such as telecommunications (Telstra), infrastructure (APA Group, Transurban), consumer staples (Woolworths, Coles), and real assets (Rural Funds Group). This diversification mitigates sector-specific risks and market volatility, while consistent reinvestment and compounding over decades can grow modest monthly contributions into multi-million-dollar portfolios capable of generating targeted passive incomes. As noted, the journey to a $1 million-plus portfolio is best viewed as a long-term destination rather than an immediate starting point.
Super’s Tax Power Unleashed
Superannuation’s zero tax in pension phase, combined with franking credits, dramatically boosts net income and slashes the capital needed for a comfortable retirement.
Superannuation stands out as a highly tax-efficient vehicle for generating sustainable passive income in retirement, primarily because earnings inside super are taxed at just 15% during accumulation and can drop to 0% in the pension phase. This tax advantage is amplified by franking credits, which become cash refunds for retirees, effectively boosting dividend yields and allowing the same income to stretch further. For example, fully franked dividends from companies like Fortescue Ltd (6.3% yield) and Westpac Banking Corp (4.4% yield) can deliver enhanced after-tax returns within super, making it more appealing than investing outside where tax rates can reach one-third of income.
The portfolio size required to achieve targeted passive income through superannuation is heavily influenced by the dividend yield of the investments chosen. To generate $7,500 monthly income, a 7% yield portfolio needs about $1.286 million, whereas a 3.5% yield demands roughly double at $2.6 million. Similarly, aiming for $11,000 monthly income at a 6% yield requires around $2.2 million, but this figure nearly doubles at a 3% yield. These calculations underscore the critical balance between yield and portfolio size, with higher yields reducing capital needs but often introducing greater risk.
Within superannuation, investors targeting mid-to-high dividend yields should consider a diversified mix of ASX-listed shares, REITs, and LICs known for reliable and often fully franked dividends. Defensive blue chips like Telstra Group Ltd (yielding 4-5.5%), Australian Foundation Investment Co Ltd, and REITs such as Charter Hall Long WALE REIT offer stable income streams, while higher-yielding names like Future Generation Global Ltd and WAM Active Ltd (with a grossed-up yield of 12.3%) provide opportunities for enhanced returns. This diversification across sectors and yield profiles helps balance income generation with risk mitigation.
Strategic portfolio construction within superannuation must also account for tax nuances beyond headline yields, including the impact of franking credits and Medicare IRMAA surcharges. While franking credits significantly enhance effective yields—turning a 5% fully franked dividend into a 7.14% effective yield for zero-tax retirees—qualified dividends still count toward Modified Adjusted Gross Income, affecting Medicare surcharges. Therefore, placing dividend-paying assets like business development companies and Treasury ETFs in tax-advantaged super accounts, while holding others in taxable accounts, optimizes both tax efficiency and income sustainability.

Annuities: The Income Safety Net
Fixed indexed annuities and mortality credits create a guaranteed income floor for life, letting retirees spend confidently without fear of outliving their savings.
Evaluating annuities effectively begins with a comprehensive assessment of retirement income needs that extend beyond basic expenses to include lifestyle desires such as social activities and memberships, as Tamako advises. For those inclined to a DIY approach, online tools offer practical means to estimate future annuity income and understand the cost of guaranteed income across different time horizons, helping retirees grasp how annuities can fit their broader financial picture.
Fixed indexed annuities (FIAs) with guaranteed lifetime withdrawal benefits (GLWB) have emerged as pivotal instruments in retirement income planning by protecting principal and growth from market downturns while ensuring income for life, regardless of account value. This protection addresses longevity risk by complementing Social Security and market assets, creating a diversified income strategy that requires intentional early planning to adapt to evolving market conditions and personal goals.
The unique feature of mortality credits allows insurance companies to pool longevity risk, enabling annuities to pay guaranteed lifetime income based on average life expectancy, which enhances retirees' confidence to spend at higher levels without fear of outliving their resources. Innovations like living benefit riders have increased annuity appeal by offering income guarantees while preserving some control over funds, addressing concerns about the irreversible nature of traditional simple income annuities.
In the wake of the 2022 simultaneous decline in stocks and bonds, experts like Brad Pistol and Dr. Wade Pfau advocate for integrating annuities—especially fixed index annuities—as a vital third asset class alongside stocks to stabilize retirement income. These annuities not only serve as bond alternatives with principal protection and tax deferral benefits but also offer competitive after-tax yields, reshaping the efficient frontier of retirement portfolios from a stocks-and-bonds mix to a stocks-and-annuities blend tailored to individual income gaps and risk tolerance.

Securing Retirement Against Life’s Curveballs
Modern annuities, Social Security timing, and innovative income products help retirees manage late-life risks and market shocks, redefining the old 60/40 playbook.
Retirees face a complex balancing act between securing sufficient income yield and preserving capital amid significant late-life risks such as rising healthcare costs, inflation, and cognitive decline. Modern annuity products, especially those bundled with long-term care coverage and designed for fee-only planners, have re-emerged as valuable tools in this environment, offering guaranteed income floors that can hedge against sequence of returns risk and longevity uncertainty. This shift is underscored by innovations like fiduciary-managed funds incorporating pension-like risk-sharing mechanisms, which, following regulatory changes in 2025, now enable lifetime income solutions within defined contribution plans, addressing the previously empty late-life financial toolkit.
Delaying Social Security benefits until age 70 can significantly enhance guaranteed lifetime income, increasing monthly payments by 8% annually past full retirement age and potentially adding $250,000 or more in lifetime benefits. Despite this, many retirees claim benefits early, inadvertently locking in smaller lifetime income and increasing reliance on volatile portfolio withdrawals. Advisors are thus urged to focus equally on the second half of retirement, proactively combining income sources—such as Social Security, pensions, annuities, and dividend portfolios—to build a resilient income floor that can endure market downturns and health-related expenses.
The 2022 simultaneous double-digit losses in both stocks and bonds shattered the conventional wisdom of the traditional 60/40 portfolio, revealing that bonds are not always a safe haven for capital preservation. This market shock has accelerated interest in a third asset class—protected income products like fixed indexed annuities—that blend growth potential with principal protection and tax deferral benefits. Experts like Wade Pfau advocate for a personalized allocation between stocks and annuities, tailored to individual income gaps after accounting for Social Security and pensions, to optimize retirement income by maximizing returns for an accepted risk level while safeguarding the income floor.
Retirees face a fundamental trade-off between higher immediate income from annuities, which blend interest with principal return but leave no capital for heirs, and dividend portfolios that offer lower but potentially growing income while preserving capital. For example, a $930,000 annuity at a 7.3% payout yields about $5,650 monthly for life, whereas a dividend portfolio yields slightly less but maintains the underlying shares. This dichotomy suggests a balanced strategy splitting funds between annuities for fixed expenses and dividend stocks for growth, while carefully managing risks such as dividend cuts—as seen with AT&T’s 2022 reduction—and tax implications like IRMAA surcharges, which depend more on account placement than investment selection.
Blending Strategies for Lasting Security
Combining super, dividends, and annuities—each with unique strengths—offers a resilient, tax-smart approach to retirement income that adapts to changing needs and markets.
Combining super, dividends, and annuities—each with unique strengths—offers a resilient, tax-smart approach to retirement income that adapts to changing needs and markets.