Walmart’s NFC u-turn: why tap-to-pay finally won
The gist
Walmart has finally caved to tap-to-pay—rolling out Apple Pay and Google Pay nationwide after a decade of resistance, rewriting the rules of retail checkout.
What to know
- Starting August 24, 2026, Walmart will accept major NFC mobile wallets like Apple Pay and Google Pay at select stores, with nationwide coverage promised by year-end.
- Walmart broke from its long-standing refusal after negotiating lower debit routing and credit fees with Apple and Google, making contactless adoption financially viable.
- This U-turn comes as digital wallets surge—now accounting for nearly 12% of in-store payments—and 21% of shoppers threaten to walk if their favorite mobile wallets aren’t accepted.
Walmart Joins the NFC Majority
Walmart’s long-awaited embrace of NFC payments not only closes a major gap in U.S. retail but signals a new era of flexible, multi-option checkouts where contactless, card, and QR payments coexist.
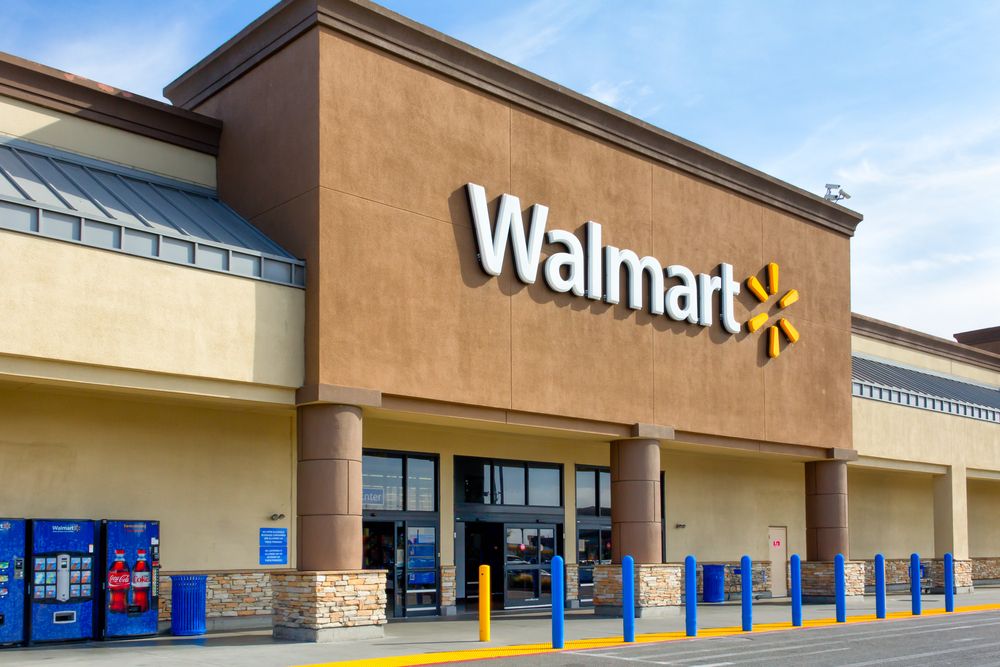
In a landmark move ending a decade-long refusal, Walmart began accepting major NFC-based mobile wallets like Apple Pay and Google Pay at select Walmart and Sam’s Club locations starting August 24, 2026, with plans to expand nationwide by the end of the year and to fuel stations by mid-2027. This strategic shift aligns Walmart with over 85% of U.S. retailers who already support NFC payments, reflecting a response to growing consumer demand for more convenient and flexible checkout options, as emphasized by executives from both Walmart and Google.
Walmart’s NFC rollout embraces a broad ecosystem of contactless payments beyond just Apple Pay and Google Pay, including contactless credit and debit cards, and integrates Walmart, Sam’s Club, and OnePay cards into digital wallets to enhance payment flexibility. Despite this expansion, Walmart maintains a multi-option checkout experience by continuing to support traditional payment methods such as cash, cards, and its proprietary QR code-based Walmart Pay app, illustrating a coexistence strategy where interoperable NFC payments complement rather than replace existing systems.
The rollout of NFC acceptance at Walmart not only closes one of the most prominent gaps in U.S. retail contactless payment adoption but also signals a broader industry trend where digital wallets are rapidly gaining ground—accounting for nearly 11.8% of in-store payments in 2025, almost matching cash at 12.1%. Moreover, Walmart’s integration of NFC payments is part of a wider checkout evolution that incorporates offers, loyalty programs, and smart transaction capabilities, positioning the retailer at the forefront of seamless, wallet-based commerce.
The phased rollout appears to have begun in Arkansas, with the last states expected to activate NFC acceptance by October 12, 2026, although Walmart has not officially confirmed this timeline. This measured deployment underscores Walmart’s careful approach to integrating tap-to-pay technology across its vast network, ensuring operational readiness while responding to the competitive pressure to modernize payment acceptance in one of the world’s largest retail environments.


Mobile Wallets Redefine Checkout
Explosive growth in mobile wallet use and rising shopper expectations have forced even the most resistant retailers like Walmart to prioritize seamless, tap-to-pay options or risk losing customers.
By 2025, consumer adoption of mobile wallets surged dramatically, with digital wallets accounting for 11.8% of in-store payments—nearly matching cash at 12.1%—reflecting a rapid shift in payment preferences. This trend is mirrored in the broader retail landscape, where 93% of merchants express readiness to adopt smart checkout technologies that integrate payment and promotional capabilities, underscoring a market-wide push toward seamless, contactless transactions.
Walmart’s long-standing resistance to tap-to-pay, driven by efforts to avoid credit card fees through proprietary solutions like Walmart Pay and the ill-fated CurrentC, has given way under mounting consumer pressure. Between 2021 and 2025, the share of U.S. consumers using mobile payments at registers more than doubled, with 70% of these transactions being tap-to-pay, compelling Walmart to finally embrace Apple Pay, Google Pay, and NFC technology by the end of 2026.
Consumer demand for convenience and speed is reshaping checkout expectations, as evidenced by 21% of shoppers abandoning carts when retailers lack popular mobile wallet options like Apple Pay or Google Wallet. This behavior, coupled with the widespread adoption of subscription services such as Amazon Prime and Walmart+—used by 85% of shoppers for faster or free delivery—highlights how seamless payment integration is critical to reducing friction and enhancing the overall shopping experience.
Evolving consumer expectations around returns and budgeting further pressure retailers to streamline checkout processes; nearly 70% of shoppers avoid retailers without free returns, and one-third—predominantly Gen Z—find online shopping complicates budgeting. These trends emphasize the importance for Walmart to not only expand interoperable payment options but also to create a frictionless, transparent shopping environment that aligns with modern consumer priorities.
Data, Fees, and the NFC Pivot
Walmart’s historic NFC resistance was rooted in fee avoidance and data control, but surging Apple Pay dominance and consumer frustration forced a strategic shift—balancing cost savings with customer loyalty.
Walmart’s decade-long refusal to accept NFC-based mobile wallets like Apple Pay and Google Pay was primarily driven by financial and strategic motives centered on minimizing interchange fees and maintaining control over transaction data. By disabling NFC hardware in its point-of-sale terminals, Walmart funneled customers into its proprietary Walmart Pay app, which allowed the retailer to avoid the average 2.36% credit card interchange fees and retain rich purchase data for marketing and loyalty purposes. However, as Apple Pay captured 92% of the U.S. mobile payment market and contactless payments surged, Walmart faced mounting consumer pressure and dissatisfaction, prompting a strategic recalibration.
By 2026, Walmart negotiated favorable debit transaction routing and credit interchange fee arrangements with Apple Pay and Google Pay, enabling a cost-effective embrace of widely accepted digital wallets nationwide. This shift not only reduces Walmart’s payment processing costs by routing debit transactions through unaffiliated networks under Durbin Amendment caps but also addresses consumer demand for faster, more convenient checkout experiences. Walmart framed the rollout as a customer-centric move to offer 'another familiar and convenient way to pay' while balancing cost management and operational efficiency.
Despite adopting interoperable NFC payments, Walmart strategically maintains control over customer loyalty and data through its fintech initiatives, such as the OnePay card and Walmart Pay app. By integrating its OnePay super-app into Apple Wallet, Walmart leverages Apple’s vast distribution network to steer shoppers toward its branded financial products, even as tokenization inherent in NFC payments limits Walmart’s access to granular purchase data. This hybrid approach mirrors international retailers like Carrefour, demonstrating that embracing open payment standards need not sacrifice proprietary digital ecosystems that foster customer engagement and loyalty.
Walmart’s previous resistance to NFC payments was also linked to its involvement with merchant-controlled alternatives like CurrentC, reflecting a broader strategy to avoid mainstream interchange fees and preserve transaction data control. The 2026 decision to enable NFC tap-to-pay across its 4,600 stores signals a pragmatic acceptance of interoperable payment infrastructure as complementary—not alternative—to its proprietary QR-code-based workflows. This dual system reduces checkout friction and costs while retaining QR codes for loyalty identification and app-based services, striking a balance between innovation, cost efficiency, and customer experience.
OnePay: Walmart’s Fintech Ambition
By embedding OnePay cards into Apple Pay and Google Pay, Walmart is turning NFC acceptance into a launchpad for its own fintech ecosystem—blending secure payments with branded financial products.
Walmart is strategically embedding its OnePay financial products within popular mobile wallets, notably through expanded Apple Pay support that enables more U.S. cardholders to make secure, contactless purchases. This integration leverages Apple Pay's robust security features, such as device-specific account numbers and biometric authentication, allowing Walmart to simplify payments while maintaining stringent data protection standards.
The OnePay CashRewards Card’s compatibility with Apple Wallet at select Walmart stores exemplifies Walmart’s broader fintech ecosystem strategy, which includes partnerships with Ribbit Capital and Synchrony. By enabling multiple card types—like the upcoming Builder Card—to be added to Apple Wallet and Google Pay, Walmart is creating a seamless mobile wallet experience that complements its recent nationwide rollout of contactless payment acceptance.
Walmart’s acceptance of Apple Pay and Google Pay through OnePay is more than a payment upgrade; it is a deliberate move to build a fintech super-app that integrates Walmart Pay’s QR code system with major mobile wallets. This multi-platform approach not only broadens customer payment options but also aims to reduce interchange fees and funnel hundreds of millions of shoppers toward Walmart-branded banking products via Apple’s distribution channels.
While embracing NFC tokenization means Walmart relinquishes some granular purchase data control to card networks, it retains critical shopper relationships and its rewards program within the OnePay app embedded in Apple Wallet. This balance allows Walmart to maintain strategic marketing advantages and customer engagement, ensuring its fintech ecosystem remains tightly integrated even as it adapts to evolving payment technologies.
The New Retail Battleground: Data
As Walmart trades some payment data for NFC convenience, the real competition shifts to who owns the customer relationship and loyalty, with AI-driven personalization and fintech ecosystems becoming the next frontiers.
By mid-2026, Walmart’s strategic acceptance of Apple Pay and other NFC payments marked a pivotal shift from its earlier resistance rooted in preserving granular purchase data and avoiding interchange fees. This change was driven by mounting consumer demand for contactless payments—highlighted by a viral 2025 social media backlash—and Walmart’s successful negotiation of favorable debit routing under the Durbin Amendment, enabling cost-effective NFC adoption while still funneling shoppers into its OnePay fintech super-app integrated within Apple Wallet.
Walmart’s embrace of NFC payments represents a nuanced tradeoff in data control: while tokenization and card network involvement reduce Walmart’s direct access to detailed transaction data, integrating OnePay cards into Apple Wallet ensures the retailer maintains the critical shopper relationship and loyalty program visibility. This approach aligns with broader retail trends where proprietary data and fintech ecosystems are essential levers, even as retailers adopt ubiquitous payment technologies to meet evolving consumer expectations.
The competitive landscape is shifting from controlling the payment transaction itself to owning the intelligence and customer relationship surrounding it. Walmart’s loosening grip on the payment interface reflects a strategic focus on building a broader ecosystem that incentivizes shopper engagement through membership benefits and services beyond checkout. Meanwhile, Amazon’s aggressive investment in AI infrastructure underscores a retail arms race where personalization, discovery, and agentic commerce—powered by AI—are becoming the true battlegrounds for competitive advantage.