Churchill downs’ casino pivot fuels record quarter, divides Wall Street
The gist
Churchill Downs’ bold casino sell-off has Wall Street torn, as record profits and big payouts clash with fresh doubts about the company’s new horse racing focus.
What to know
- In July 2026, Churchill Downs announced plans to sell nine regional casinos and shift capital to horse racing, historical racing, and TwinSpires.
- Q3 2026 delivered record $700M revenue, 10% adjusted EBITDA growth, a $750M buyback, and a 7% dividend hike.
- Analysts are split: some cheer the capital returns, while others warn sector headwinds could make the turnaround fragile.
Strategic Overhaul, Not Just Downsizing
Churchill Downs’ casino sales mark a deliberate bet on racing and digital wagering, signaling a high-stakes shift away from traditional gaming amid industry headwinds.
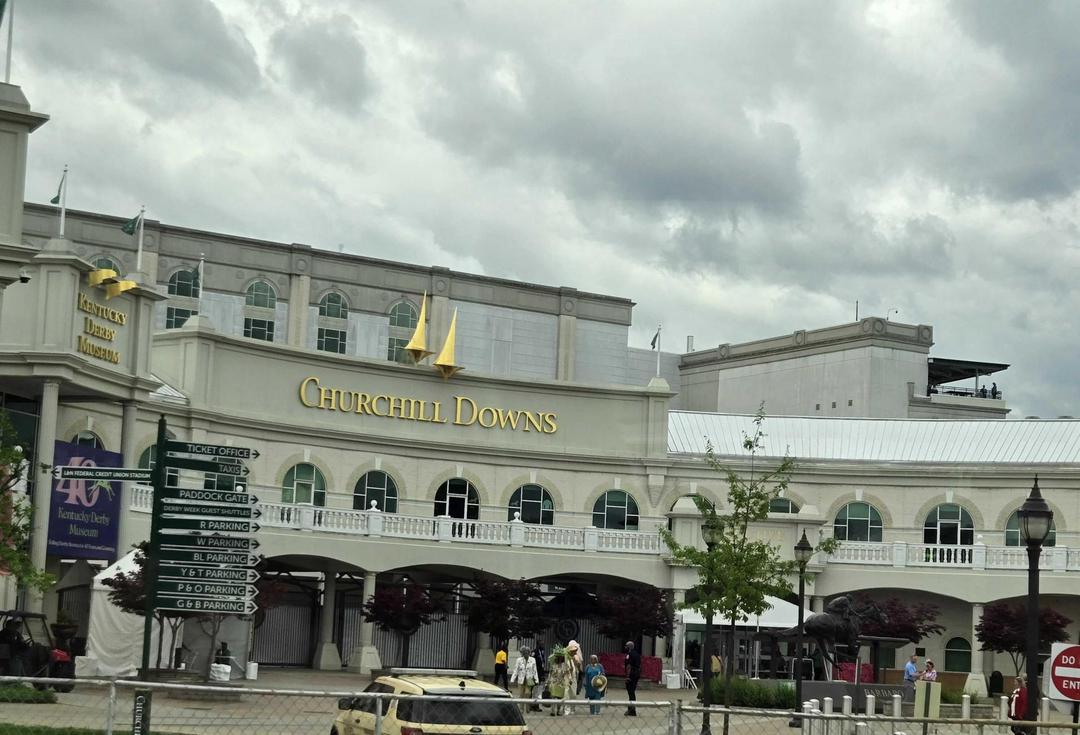
Churchill Downs set the pivot in motion in July 2026, when it initiated a restructuring by targeting the sale of non-core regional casino assets to lower leverage and redirect capital toward its racing and digital wagering businesses. The company said its strategic review would explore the sale of nine regional gaming properties so it could refocus capital on racing, historical horse racing and TwinSpires, a move that framed the shift as an active portfolio redesign rather than a routine pruning of assets.
That message was clear enough to shape the market narrative immediately: Bisnow National summed up the turn with the headline, “Churchill Downs to Sell 9 Casinos, Including Sioux City Hard Rock, Refocuses on Horse Racing.” But the need to emphasize leverage reduction and capital redeployment also underscored why investor reaction stayed cautious, because the company was not just selling properties but trying to prove that a narrower strategy built around horse racing and digital wagering could better withstand broader gaming-sector pressure.
Profits Power Shareholder Rewards
A record-breaking quarter enabled Churchill Downs to boost buybacks and dividends, reframing its pivot as a confident, earnings-driven transformation rather than a defensive retreat.
Churchill Downs’ late-October quarter gave investors a fresh reason to focus on the company’s pivot because the strategy was suddenly backed by a clean, visible earnings beat and an immediate shareholder payoff. In late October 2026, Churchill Downs’ Q3 results and capital-return actions provided investors a new reason to concentrate on the company’s strategic pivot. StockStory captured that reset in a single headline — “Churchill Downs Shares Jump 9% on Record Q3 Revenue, $750 M Buyback and Dividend Hike” — explicitly tying the market reaction not just to operations but to capital return, and showing how the quarter reframed the story around execution rather than only strategic intent.
That mattered because the operating print itself was strong enough to make the capital actions look earned rather than defensive. Brew Markets said Churchill Downs “just posted a record quarter,” with “record revenue of $700 million” and “adjusted EBITDA… up 10%,” while also noting that CFO Bill Dahl said “the dividend is going up to 7%, the 16th straight annual increase,” alongside a plan “to pay down debt, buy back stock and invest in the Derby track” — a combination that reinforced the pivot with both record profitability and a $750 million repurchase.
Racing Bets Get Capital Boost
Divesting casinos is funding a focused push into horse racing and historical wagering, with debt restructuring designed to free up cash for Derby upgrades and future growth.
Churchill Downs’ sale program is being presented as a balance-sheet and capital-allocation reset, not a retreat from wagering. Eagle Point Capital said management chose to sell most of its regional casinos so proceeds could repay debt, return capital, and sharpen focus on the faster-growing horse-racing business, while that racing focus still includes wagering products such as historical racing machines, which are “basically a slot machine” whose outcomes are tied to past horse races rather than random-number generation, underscoring that the company is reallocating capital toward racing-adjacent betting rather than abandoning gaming activity.
The financing moves reinforce that interpretation because they are described as changing funding flexibility for future projects, not changing the underlying investment agenda. Simply Wall Street wrote, “The most relevant development linked to this refinancing is the plan to redeem the 5.50% Senior Notes due 2027 using the revolving credit facility,” and “That decision concentrates Churchill Downs’ funding even more in” variable-rate bank debt; the same analysis said, “The question is whether extended maturities to 2031 and the new US$500m Term Loan B due 2033 give Churchill Downs enough breathing room to keep backing Derby upgrades, HRM rollouts and potential property sales without” debt service crowding out reinvestment.
Wall Street Divided on Longevity
Analysts remain split as Churchill Downs’ bold pivot faces skepticism over sector volatility, with even bullish forecasts hinging on tough market conditions and shifting consumer trends.
The split over Churchill Downs’ pivot looks less like a verdict than a proxy for a broader debate across wagering stocks: some investors reward capital discipline and preserved guidance, while others see every restructuring move through the lens of weakening demand and unstable economics. That tension is visible in online betting, where DraftKings and Flutter entered Q2 with shares down 32% and 51% year to date, respectively, amid what Analysis described as skepticism about established operators’ growth and profitability as prediction markets emerge as both opportunity and threat.
The cautious camp has hard numbers behind it, which helps explain why Churchill’s own turnaround case still meets resistance despite financial engineering that bulls call value-creating. JPMorgan modeled DraftKings Q2 adjusted EBITDA at $120 million versus a $188 million Street view, Bank of America matched that $120 million and cut its full-year estimate to $625 million from $700 million, while Deutsche Bank put quarterly EBITDA at $140 million, down from $246 million, alongside same-store sportsbook handle down about 2% year over year and iCasino GGR growth of just 1.9%.
Even the more constructive readings come with conditions, which is why buybacks and refinancing do not automatically settle the argument. Deutsche Bank said the low end of DraftKings’ $700 million to $900 million full-year EBITDA guidance depends heavily on Q4 performance and a roughly 12% structural hold rate, while Analysis said DraftKings emerged with guidance intact and analysts broadly relieved even as Flutter shares fell more than 13% after a second guidance cut and a CEO surprise, then reduced U.S. adjusted EBITDA guidance by 22% to $760 million because of another $270 million of customer investment.