CME’s legal gambit: duffy battles CFTC to keep crypto perpetual futures in regulatory check
The gist
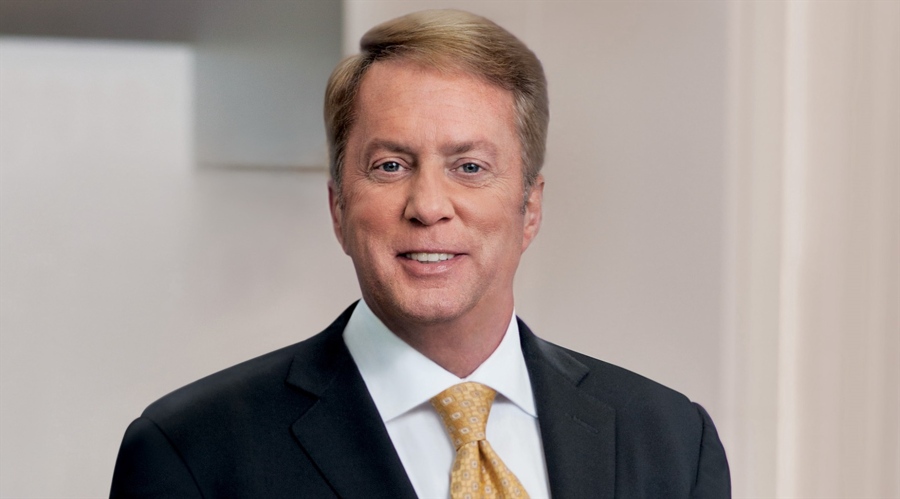
CME Group, led by outgoing CEO Terry Duffy, is launching a legal blitz against the CFTC to force stricter regulation on crypto perpetual futures and protect its $20 billion derivatives turf.
What to know
- CME claims perpetual futures like Kalshi's BTCPERP are swaps under Dodd-Frank, demanding five-day margin periods and dealer registration—far stricter than the two-day future rules.
- The CFTC's green light for these products opens the door to higher leverage and competitor platforms, threatening CME’s market dominance and potentially pushing more trading offshore.
- Kalshi insists its products align with CFTC futures rules, while the regulator scrambles to adapt oversight for 24/7 crypto derivatives as Duffy makes his final—and fiercest—stand.
Regulatory Turf War Unfolds
CME's legal offensive against the CFTC spotlights a high-stakes battle over how crypto perpetual futures are classified—one that could redefine compliance burdens, reshape leverage limits, and determine who controls the $20 billion U.S. derivatives market.
CME Group, under outgoing CEO Terry Duffy, has launched a high-stakes legal challenge against the CFTC's May 29th approval of crypto perpetual futures products such as Kalshi's BTCPERP, arguing these instruments are swaps rather than futures. Duffy emphasizes that perpetual futures, characterized by their open-ended nature and periodic funding rates, functionally align with swaps under the Dodd-Frank Act, which mandates stricter regulations including mandatory clearing, dealer registration, and enhanced margin requirements. He asserts, "Under Dodd Frank, it clearly defines what a swap is, of what a future is. And when there's two parties exchanging payments to each other, that is defined as a swap," framing the CFTC's approval as "rushed and legally flawed" for circumventing the required full review of these novel products.
At the heart of the dispute lies a fundamental regulatory classification battle with significant implications for margin requirements and jurisdictional control. The Dodd-Frank framework, born from the 2009 G20 summit, distinguishes swaps and futures primarily through margin periods—swaps require a five-day margin period of risk versus two days for futures—impacting leverage and risk management. CME contends that classifying crypto perpetual futures as swaps would impose heavier compliance burdens, including routing trades through CME's infrastructure due to its exclusive benchmark licensing agreements, effectively preserving its $20 billion franchise and limiting market entrants like Kalshi, Coinbase, and Kraken. This turf fight is less about safety concerns and more about market control in an evolving crypto derivatives landscape.
The legal challenge also underscores the ambiguity and complexity embedded in the regulatory classification of crypto derivatives, with Congress itself acknowledging in a Dodd-Frank footnote that it deferred clear guidance on instruments like perpetual futures. This uncertainty opens the door for strategic legal maneuvering in a post-Chevron deference era, where courts may scrutinize agency decisions more rigorously. Analysts like Austin Campbell caution that while CME holds a strong legal position—supported by TD Cowen's assessment—the outcome could reshape onshore leverage constraints and potentially push trading activity offshore if stricter swap regulations are enforced, thereby influencing the future trajectory of U.S. crypto derivatives markets.
Onshore vs. Offshore Showdown
The clash over perpetual futures is fracturing the market, with U.S. exchanges facing tough regulatory hurdles while offshore platforms lure traders with higher leverage and fewer restrictions, setting up a fierce competition across regulatory borders.
CME Group's legal challenge against the CFTC's approval of crypto perpetual futures is a strategic move to preserve its regulatory moat by enforcing swap classification and stricter margin requirements, effectively limiting onshore participation and potentially pushing these products offshore. As CEO Terry Duffy emphasized, these instruments require 'five day margin' and swap dealer registration, which contrasts sharply with blockchain-enabled near real-time collateralization innovations that could lower margin demands and broaden market access. Meanwhile, other futures exchanges like Eurox and ICE are forging partnerships with crypto platforms such as Kraken and OKEx, signaling a fragmented and evolving competitive landscape where CME is aggressively defending its turf amid rising crypto derivatives innovation.
The emergence of crypto perpetual futures like Kalshi's BTCPERP introduces a disruptive product structure fundamentally different from traditional futures, challenging established exchanges such as CME, ICE, and CBOE by threatening their market dominance. These incumbents benefit from entrenched liquidity network effects, collateral efficiencies, and robust back-office clearing relationships, creating high barriers to entry for new competitors. However, the novel perpetual contracts, which rely on a 'funding rate' rather than physical delivery, could reshape market models and regulatory frameworks, intensifying competitive pressures as reflected in recent investor caution and analyst price-target cuts, notably TD Cowen's reduction of ICE's target despite strong earnings.
A bifurcated market is emerging between onshore and offshore crypto perpetual futures platforms, with the massive U.S. retail market offering significant growth potential for onshore players due to freer marketing and broader audience reach. Yet, stringent U.S. regulatory constraints, including lower leverage limits—typically around 10x compared to offshore offerings of up to 100x—may drive retail traders toward offshore platforms like Hyperliquid and Binance, which already dominate that space. This dynamic suggests a commoditized and fiercely competitive onshore environment with multiple licensees vying for market share, while offshore platforms consolidate dominance, creating distinct winners on each side of the regulatory divide.
The ongoing legal battle between CME and the CFTC encapsulates a broader tension in the financial ecosystem: traditional exchanges are actively seeking to limit crypto entrants to protect incumbency, whereas crypto firms push for regulatory acceptance to compete fairly. This dynamic mirrors the inverse of Coinbase's lawsuit against the SEC, highlighting how established players like CME are leveraging regulatory frameworks defensively to maintain market control. Critics warn that such defensive postures risk stifling U.S. financial innovation and leadership by constraining crypto market participation, potentially ceding global fintech dominance to less restrictive jurisdictions.

Kalshi’s Compliance Counterpunch
Kalshi asserts its crypto perpetual futures meet CFTC standards, while regulators grapple with adapting oversight for 24/7 derivatives in an era where traditional rules and trading hours no longer apply.
Kalshi staunchly defends its crypto perpetual futures by highlighting that its risk models and leverage levels align closely with those of established CFTC-regulated futures on major U.S. exchanges like CME. John Wang emphasized that their products operate within the same regulatory framework, countering critiques that these instruments pose unique risks to retail investors, thereby positioning Kalshi as a compliant innovator in the evolving derivatives landscape.
The CFTC’s regulatory approach to perpetual futures is in flux, as evidenced by its May 2026 approval of bitcoin perpetual futures followed by a June request for public comment on applying similar structures to energy markets. This inquiry underscores the complexities regulators face in adapting perpetual futures to fundamentally different underlying assets, such as bitcoin’s continuous global spot market versus crude oil’s limited trading windows, raising practical questions about funding rates, margin calls, and market integrity during off-hours.
This regulatory engagement reflects a broader industry trend toward 24/7 trading models, with CME Group launching round-the-clock crypto futures trading and LMAX introducing continuous gold perpetual futures. These developments illustrate how market participants are pushing the boundaries of traditional trading hours, compelling regulators to reconsider frameworks that historically assumed limited trading windows and highlighting the tension between innovation and risk management.
The CFTC is vigorously defending its exclusive jurisdiction over prediction markets amid mounting state-level legal challenges, underscoring the importance of these markets for societal risk hedging and market integrity. Chairman Mike Selig’s firm stance—'We will see you in court'—signals readiness for prolonged legal battles, while the agency simultaneously advances formal rulemaking and public consultations to clarify oversight. Meanwhile, industry players like Cboe are innovating within regulated spaces by launching products such as 'Cboe Predicts,' binary options that mimic prediction markets but operate under established securities regulations.
Duffy’s Last Stand at CME
Terry Duffy’s aggressive legal and regulatory maneuvers aim to entrench CME’s dominance, leveraging tighter rules and exclusive infrastructure to keep disruptive crypto rivals at bay as he exits the stage.
Under the combative and strategic leadership of outgoing CEO Terry Duffy, CME Group is aggressively defending its market dominance amid the disruptive rise of crypto perpetual futures. Duffy, who has overseen CME’s transformation into a derivatives powerhouse with margins expanding from 34% to 66% and a market cap soaring 8,000% since its IPO, is spearheading a comprehensive legal challenge against the CFTC’s approval of products like Kalshi's BTCPERP. He argues these instruments are swaps requiring stricter Dodd-Frank regulation, reflecting CME’s broader effort to shape regulatory classifications that protect its established market share and infrastructure.
Duffy’s leadership style—marked by a readiness to engage in high-stakes battles—underscores CME’s intent to preserve a regulatory moat around its business as it faces emerging challengers like Kalshi. By advocating for increased margin requirements and lower leverage, he aims to make crypto perpetuals less appealing to onshore participants, thereby limiting offshore competition and safeguarding CME’s core derivatives franchise. This strategic positioning highlights CME’s commitment to traditional principles such as capital efficiency and user protections, resisting innovations that could disrupt its dominance even as Duffy prepares to step down.
Navigating a rapidly evolving regulatory and technological landscape, Duffy has positioned CME to confront new market entrants and regulatory uncertainty with a blend of legal rigor and strategic foresight. His framing of the CFTC’s approval process as rushed and legally flawed—asserting that 'perpetuals are effectively swaps'—reflects a calculated effort to influence the regulatory environment in CME’s favor. This approach not only aims to limit competition from innovative platforms like Kalshi’s prediction market but also ensures that CME’s exclusive benchmark licensing agreements and clearing infrastructure remain central to the crypto derivatives ecosystem.