Cramer dumps AI favorites for safer bets
The gist
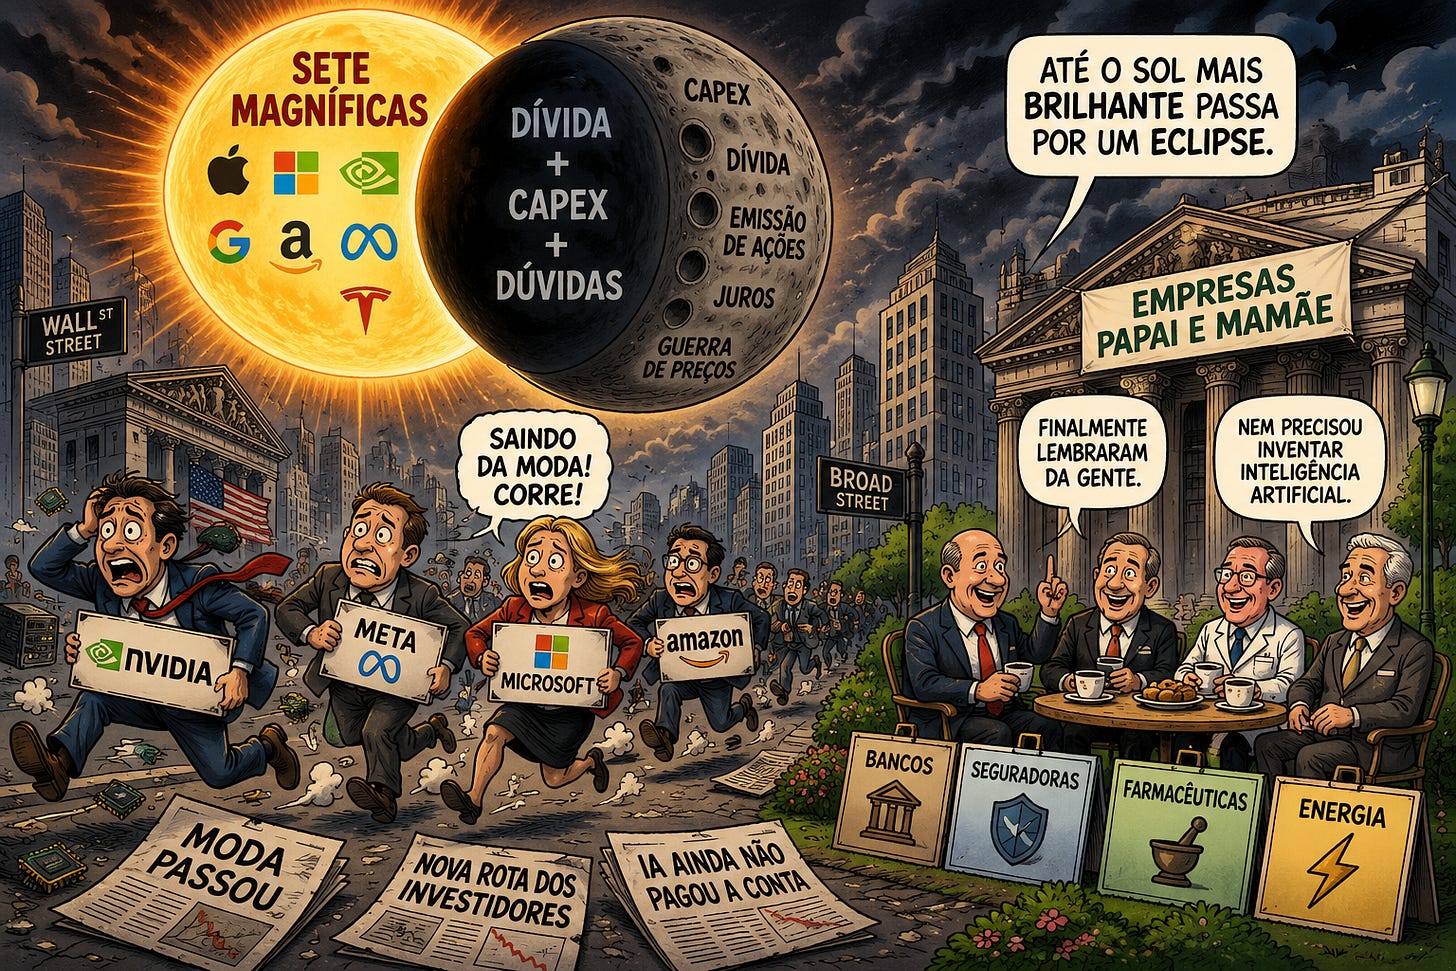
Wall Street is ditching AI high-flyers as Jim Cramer and investors pile into defensive sectors like financials and healthcare, driving a major market rotation.
What to know
- Cramer is unloading AI momentum stocks for picks like Eli Lilly, Energy Transfer, and J.B. Hunt, betting on stability as tech giants stumble.
- Financials are surging—Jefferies jumped 5.3%, Goldman Sachs and Morgan Stanley crushed earnings by 48.8% and 23.1%, fueling XLF ETF to all-time highs.
- Rising financing costs for AI projects and a 36% plunge in AI infrastructure stocks are pushing investors toward stable, income-generating sectors.
Cramer's Strategic Sector Shift
Jim Cramer is doubling down on durable, theme-driven stocks in healthcare, energy, and financials, while selectively backing resilient tech like Dell to balance caution with tactical opportunity.
Jim Cramer's tactical stock recommendations reflect a deliberate pivot away from the high-flying AI momentum stocks toward more defensive and resilient sectors such as healthcare, energy, and financials. Highlighting companies like Eli Lilly, Energy Transfer, and J.B. Hunt Transport Services, Cramer is capitalizing on the market rotation by focusing on sectors that stand to benefit from shifting investor sentiment and economic conditions. This approach aligns with his broader thematic investing strategy, which emphasizes durable trends that allow investors to confidently add to positions during pullbacks.
While the market broadly rotates away from AI stocks, Cramer singles out Dell Technologies as a standout tech name that remains well-positioned due to its AI-driven product growth and technical resilience, describing it as 'forming a sturdy base.' This nuanced stance illustrates his tactical flexibility, balancing caution on momentum stocks with selective exposure to tech leaders that underpin the AI infrastructure theme.
Cramer's portfolio adjustments underscore his commitment to thematic investing, as evidenced by his Charitable Trust's holdings in companies across his five key themes—ranging from Capital One and American Express in consumer spending to cybersecurity giants CrowdStrike and Palo Alto Networks, and financial powerhouses Goldman Sachs and Morgan Stanley. This diversified yet theme-driven positioning reflects his strategy to build portfolios with the 'wind at their backs,' enabling investors to navigate volatility with confidence.

Defensive Sectors Take the Lead
A broad market rotation is underway as investors pour into financials, utilities, and energy, signaling a shift from speculative tech to stable, income-generating sectors amid rising economic uncertainty.
The market is undergoing a pronounced rotation away from AI-driven tech and momentum stocks toward more defensive and value-oriented sectors such as financials, healthcare, energy, and industrials. This shift is underscored by sector-wide rallies, exemplified by Jefferies Financial Group’s 5.3% jump amid a broader financials surge, and Goldman Sachs and Morgan Stanley crushing earnings estimates by 48.8% and 23.1% respectively, pushing the financial sector ETF XLF to all-time highs. Meanwhile, energy stocks have gained strength due to geopolitical tensions, further supporting this rotation as investors seek stability and income over speculative growth.
This rotation reflects a healthy market correction rather than a panic or bear market, driven by stretched valuations in AI stocks, natural profit-taking, and a growing investor appetite for diversification away from a handful of mega-cap tech giants. The pullback in chip and AI infrastructure stocks has been significant—Sandisk, for example, plunged nearly 50% from 2300 to 1300—while defensive sectors like healthcare are hitting or nearing new 52-week highs. As one analyst noted, the market is moving toward "a more balanced and stable market where performance is less dependent on five titles," signaling a broadening of leadership and improved market breadth.
Rising economic uncertainty, fueled by inflation fears, higher 10-year Treasury yields, and geopolitical tensions, is driving investors toward lower-beta, defensive sectors such as utilities, materials, precious metals, and housing financials. On days when the broader market was flat or down, utilities surged 2.2%, materials and mining gained nearly 2%, and gold and silver prices reignited, illustrating a flight to safety. This macro backdrop reinforces the rotation as institutional investors reallocate capital from volatile tech names to sectors offering more predictable income streams and resilience amid uncertainty.
The shift away from AI and momentum stocks is also reflected in broader market metrics, with the equal-weighted S&P 500 outperforming the Nasdaq 100, which is nearing a 10% correction. The 25 best-performing Russell 1000 stocks in the first half of the year—mostly semiconductors and AI infrastructure—have fallen over 36% recently, while the prior laggards gained 14%, signaling a clear reversal in leadership without major corporate news. Additionally, rising financing costs for AI-related projects, such as Meta’s $12.5 billion bond issuance at 7.5% interest, are pressuring these companies, contributing to the rotation as investors reassess growth prospects amid higher capital costs.


Market Breadth Breaks Out
As mega-cap tech dominance fades, small-caps and equal-weighted indexes surge to multi-decade highs, reflecting a healthier, more diversified rally even as AI and semiconductor stocks tumble on financing pressures.
Investor sentiment is undergoing a notable shift away from the concentrated dominance of the 'Magnificent 7' tech giants, such as NVIDIA and Micron Technology, whose outsized influence has historically propelled S&P 500 earnings growth. While these companies still lead, the broader market is seeing stronger contributions from defensive sectors like energy—with Chevron and Exxon Mobil among the top Q2 2026 earnings contributors—highlighting growing concerns over valuation concentration and prompting investors to diversify. Excluding tech heavyweights, the S&P 500’s blended earnings growth rate would drop from 24.7% to 16.8%, underscoring the market’s reliance on a few names and fueling rotation into more stable sectors.
This rotation away from AI mega-caps toward defensive sectors such as financials, healthcare, and consumer staples is driven by a confluence of valuation pressures, profit-taking, and a structural need for diversification to mitigate portfolio risk. Since 2024, the top 10 S&P 500 stocks accounted for nearly 59% of gains, but recent capital flows have broadened, with technology declining 2.6% while financials and communication sectors rose over 2%, reflecting investors’ appetite for earnings visibility amid high interest rates. As one analysis put it, 'ce n’est pas l’abandon de l’IA... leur pause ressemble à une consolidation, pas à un krach,' indicating this is a rebalancing rather than a repudiation of AI leadership.
Market breadth is improving markedly, signaling a healthier and more inclusive rally as small-cap stocks hit their best half-year performance since 1991 and the equal-weighted S&P 500 reached an all-time high, outperforming the Nasdaq 100 which faces correction risks. This broadening is accompanied by a sharp decline—over 36% in a month—in semiconductor and AI infrastructure stocks that led gains earlier in the year, reflecting investor caution amid rising financing costs. For instance, Meta’s $12.5 billion bond issuance at a 7.5% rate, nearly three points above the 10-year Treasury, exemplifies the higher capital costs dampening enthusiasm for high-growth tech projects.
Adding to the rotation dynamics, 2026 is poised to mark a reversal in the long-standing trend of share buybacks with net equity issuance expected to rise, increasing stock supply and exerting downward pressure on prices. This shift undermines a key support mechanism for high-growth tech stocks, further encouraging investors to pivot toward traditional, defensive sectors like banks, insurers, and pharmaceuticals that offer more predictable income streams. As these 'mom-and-pop' stocks gain favor, the market is recalibrating toward stability and sustainable earnings growth amid evolving economic and geopolitical uncertainties.