David jones collapse: legacy retail model meets digital reality
The gist
David Jones’ 188-year run ended in dramatic collapse as its old-school department store model crumbled under the weight of missed digital bets and stubborn lease burdens.
What to know
- David Jones shut its web store way back in 2003, leaving it exposed as ecommerce boomed and retail shifted online.
- After Woolworths Holdings bought the chain for A$2.1 billion in 2014, massive store leases and legacy costs dragged profits down while new digital rivals surged.
- By late 2026, falling revenue, a $4.4m loss, and a scramble for $10 million in emergency funding signaled insolvency and forced David Jones into administration.
Legacy Weaknesses Exposed
David Jones’ digital missteps and inherited store liabilities set the stage for a collapse that was years in the making, not a sudden shock.
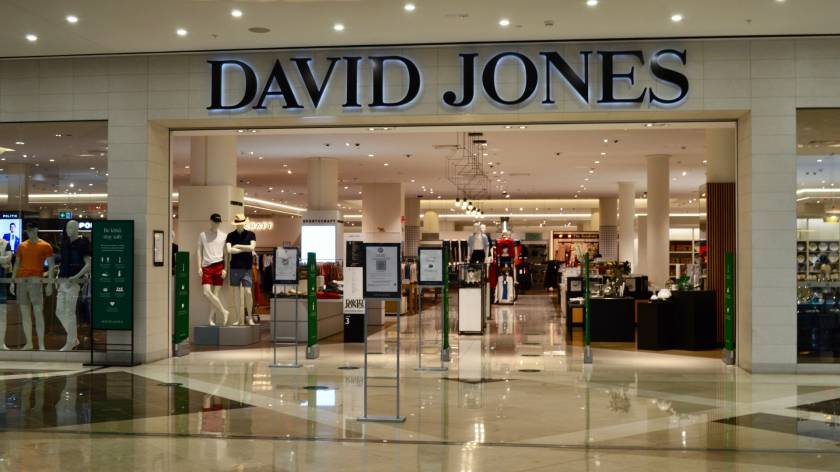
The collapse that became unmistakable between June and November 2026 had much deeper roots in David Jones’ legacy structure. In 2003, David Jones closed its web store, leaving the retailer without an established digital sales channel as online retail grew, and that long-running digital gap left it poorly positioned for the market shifts that later exposed its fragility; the burden was compounded after Woolworths Holdings acquired David Jones in 2014 for approximately A$2.1 billion (R21.4 billion), inheriting its physical-store estate, lease obligations, and the costs associated with transitioning to digital retail.
By November, those accumulated weaknesses had crystallised into an unmistakable endgame, with SmartCompany framing the company’s failure as the culmination of years of legacy retail stagnation rather than a sudden shock. “This week we saw David Jones enter voluntary administration for the first time in its 188 years,” SmartCompany wrote, placing that milestone within a June-to-November 2026 sequence in which other legacy retailers also failed, a pattern that underscored how David Jones’ escalating losses, emergency funding efforts and final administration together marked the moment its long decline became collapse.
Store Costs Sink Survival
Mounting lease and staffing expenses left David Jones unable to pivot as nimble online rivals siphoned customers and liquidity vanished.
The timing of David Jones’ collapse reflects more than a bad trading patch: it shows how a legacy department-store model had become structurally exposed as ecommerce and direct-to-consumer brands redirected spending away from physical retail. As the August 2026 analysis put it, online sellers could go “straight to customers” with “no need for a retail shop, no middleman,” while traditional chains were left carrying rent, staffing and utility costs that once absorbed “huge chunks of revenue,” turning digital disruption into a direct threat to store viability.
That structural disadvantage mattered because old retailers were not just losing sales; they were trying to modernize while still burdened by the “massive overhead of physical stores and staff,” limiting how quickly they could adapt online. By late October, the strain had become a liquidity problem severe enough that SmartCompany’s headline read, “David Jones Secures $10 Million Emergency Funding from Hilco Ahead of Christmas Sales Crisis,” with Hilco providing “$10 Million Emergency Funding” to David Jones — a sign that the legacy model’s weakening economics had tipped into insolvency territory.

Losses Driven by Lease Woes
Revenue declines and costly lease write-downs directly eroded David Jones’ financial stability, forcing last-ditch funding just to keep shelves stocked.
The financial strain was not abstract; it showed up plainly in David Jones’ numbers. As NZ Herald Business & Technology reported in June, the headline itself captured the deterioration: “David Jones NZ revenue falls 11% as lease write-down drives $4.4m loss,” a formulation that matters because it ties weakening sales directly to a reported loss rather than to a softer narrative of challenging conditions, and shows the company’s distress was already measurable in both top-line decline and bottom-line damage. The pressure was severe enough that, just over a week ago, it was revealed that David Jones had secured $10 million in emergency funding to buy stock ahead of its crucial pre-Christmas sales, reinforcing how immediate and concrete its liquidity needs had become.
That loss was also explicitly linked to balance-sheet pressure, not just weaker trading. NZ Herald Business & Technology stated the loss was driven by a “lease write-down,” underscoring how store-related obligations were actively eroding results, while SmartCompany later described David Jones as being “put into administration over unpaid rent at some of its 38 Australian and New Zealand stores, as well as long-term financial woes,” evidence that the company’s finances had deteriorated enough to raise serious doubts about its ability to continue operating normally.