Gulf oil producers expand bypass routes
The gist
Gulf states are racing to sidestep the Strait of Hormuz, pouring billions into new export routes and risk strategies as regional threats make energy flows more precarious than ever.
What to know
- The UAE’s ADNOC is investing $6.2 billion to expand gas production and build an LNG export plant at Fujairah, while laying new rail lines to ports outside the Hormuz chokepoint.
- Saudi Arabia is boosting its Petroline pipeline capacity and pioneering a SAR 700 million state-backed war risk insurance pool to shield oil shipments from escalating attacks.
- Middle Eastern producers now rely on covert shipping tactics and alternative ports, as dual chokepoint disruptions have forced oil to reroute around Africa, adding weeks and spiking insurance costs.
Pipelines, Ports, and Arctic Gambits
Gulf states are racing to diversify oil and gas export routes—by rail, pipeline, and even Arctic shipping corridors—exposing the complex interplay between infrastructure capacity and mounting security threats.
The UAE's ADNOC is spearheading a comprehensive infrastructure expansion to bypass the Strait of Hormuz, investing $6.2 billion in gas field developments like Umm Shaif and Ghasha to boost production by 6.8 billion cubic feet per day, aiming for gas self-sufficiency by 2030. Complementing this, ADNOC is constructing a new LNG export plant at Fujairah, strategically positioned outside the chokepoint, while rerouting fertiliser exports via road and rail to ports such as Fujairah and Sohar through new rail lines like Etihad Rail and Hafeet Rail, thereby diversifying logistics and reducing maritime vulnerability.
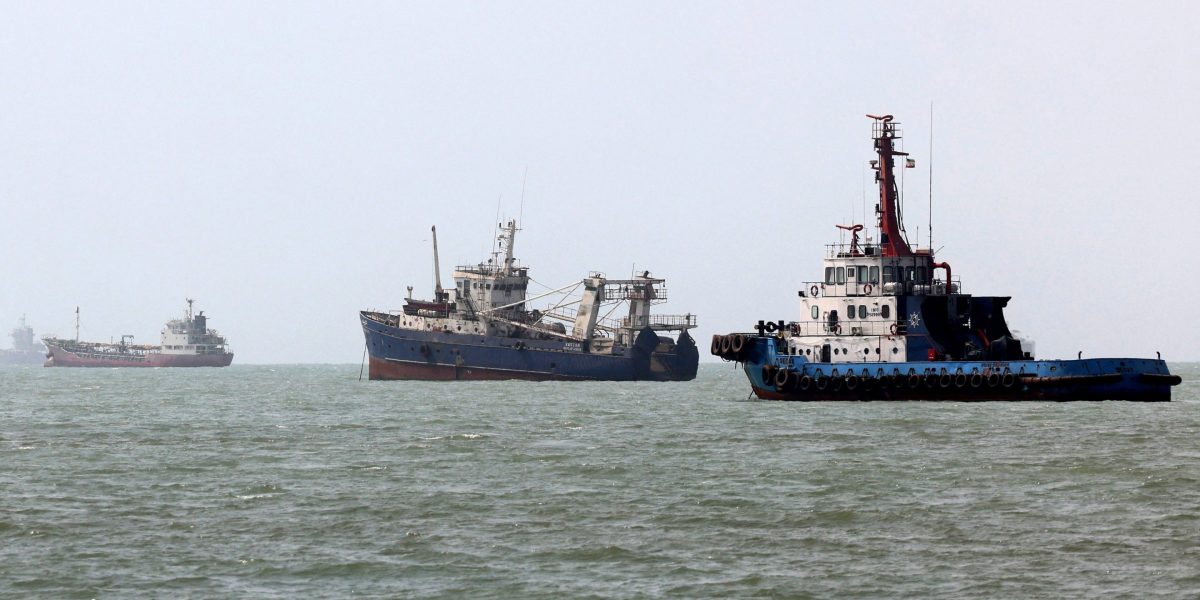
Fujairah has solidified its role as a pivotal oil export hub, facilitating 4 to 5 million barrels per day through ship-to-ship transfers that circumvent the Strait of Hormuz, enabling Kuwait, Iraq, UAE, and Saudi Arabia to maintain crude flows despite regional conflicts. Meanwhile, Saudi Arabia’s Petroline pipeline, stretching 1,200 kilometers to Yanbu with a nominal capacity of up to 7 million barrels per day, faces port and logistical constraints that limit its full potential, underscoring the complex interplay between pipeline capacity, port infrastructure, and security threats such as Houthi drone attacks that collectively challenge export reliability.
Beyond the Middle East, emerging Arctic and Eurasian corridors are reshaping global export routes, with China planning weekly transits through the Northwest Passage to halve shipping times between Asia and Europe, despite initial icebreaker limitations. Concurrently, overland routes like the International North South Transport Corridor connect northern Europe to the Arabian Sea via Russia, Azerbaijan, and Iran, offering strategic alternatives to maritime chokepoints like the Strait of Hormuz and the Suez Canal, reflecting a broader shift toward pipelines and land-based conveyance to mitigate geopolitical risks inherent in traditional sea lanes.
Saudi Arabia is actively enhancing export resilience by considering a Petroline expansion of up to 2 million barrels per day, reinforcing its Vision 2030 ambitions to become a global logistics hub through integrated investments in ports and industrial zones. This expansion is less about volume and more about strategic flexibility, allowing diversification away from vulnerable maritime chokepoints. Complementing these efforts, Gulf operators are investing in African port infrastructure to build redundancy and exploring state-backed war and political risk insurance pools, such as the SAR 700 million scheme supported by Saudi Export-Import Bank, to sustain trade flows amid escalating security threats in chokepoints like the Red Sea.

Iran Tightens Chokepoint Grip
Tehran’s drive for formal control over Hormuz and its calculated use of regional proxies are reshaping power dynamics and escalating the risk calculus for every vessel passing through Middle Eastern waters.
Iran's strategic ambition to assert formal control over the Strait of Hormuz marks a pivotal shift in regional power dynamics, as Tehran seeks to regulate maritime traffic through this critical chokepoint. Despite repeated negotiation attempts to establish safe passage agreements, talks have stalled amid ongoing attacks, underscoring persistent instability and a medium-term reduction in shipping volumes that signal a departure from pre-war norms. As Iran’s parliament speaker Mohammad Baqer Qalibaf declared, the strait’s management will not revert to its former status, solidifying Tehran’s intent to maintain leverage over global energy flows.
Fujairah has emerged as the next geopolitical flashpoint following the Strait of Hormuz and Bab el-Mandeb, with both the US and Iran recognizing its strategic importance in global oil markets. Iran’s calculated restraint from direct attacks on Fujairah’s port and tankers, despite its significant crude throughput of approximately 6 million barrels per day, reflects a deliberate escalation strategy that leverages multiple chokepoints through its 'axis of resistance'—including Houthi proxies in Yemen and Hezbollah in the Mediterranean—to exert economic pressure without provoking full-scale conflict. This multi-pronged approach intensifies regional tensions and complicates efforts to secure reliable export routes.
The Houthis’ naval blockade and targeted attacks on Saudi shipping in the Red Sea represent a strategic escalation that directly threatens Saudi Arabia’s export infrastructure and the security of vital maritime routes. Acting as Iranian proxies, the Houthis have shifted focus from broader regional targets to concentrating pressure on Saudi assets, enforcing selective blockades based on vessel ownership and crew nationality, which forces costly rerouting and heightens operational uncertainty. Despite sustained US, Israeli, and UK air campaigns damaging Houthi infrastructure, their capabilities remain intact, perpetuating instability and complicating efforts to reopen secure shipping lanes.
The persistent geopolitical deadlock over Middle East maritime security is compounded by global powers’ hesitance to propose viable solutions, with European and Chinese diplomatic efforts stymied by US political calculations under the Trump administration. This impasse exacerbates the volatility of key chokepoints like the Strait of Hormuz and Bab el-Mandeb, driving Gulf states to rely heavily on bypass routes and ship-to-ship transfers—such as the UAE’s Fujairah hub handling 4 to 5 million barrels per day—to maintain crude exports. Consequently, elevated security risks, operational restrictions, and increased insurance premiums are fracturing global oil transit reliability and inflating costs across international shipping networks.
Covert Shipping and Skyrocketing Costs
Producers are risking lives and adopting clandestine tactics to keep oil flowing as insurance premiums surge and traditional fallback routes vanish, revealing the fragility of global supply chains under sustained attack.
In response to escalating attacks on vessels transiting the Strait of Hormuz, Middle Eastern oil producers including Abu Dhabi National Oil Co. have adopted covert shipping strategies that involve turning off AIS transponders during nighttime passages to evade Iranian drone threats. This clandestine shuttle trade, which involves ferrying oil undetected through the strait to the Gulf of Oman for offloading, has been pivotal in maintaining robust oil flows of 8 to 9 million barrels per day despite the conflict, effectively stabilizing Brent crude prices between $80 and $90 a barrel. However, these covert operations have come at a human cost, with 23 Adnoc vessels attacked resulting in casualties, underscoring the high stakes producers are willing to bear to meet global energy demand.
The surge in war risk insurance premiums—from a pre-war 0.25% of hull value to as high as 10% for Hormuz transits—reflects the heightened security risks and has significantly impacted shipping cost structures. To mitigate these challenges, Saudi Arabia is pioneering a state-backed war and political risk insurance pool, potentially covering up to SAR 700 million per event and backed by the Saudi Export-Import Bank and reinsurers like Saudi Re and Riyadh Re. This innovative approach aims to provide broader coverage for the increasingly blurred lines between war, terrorism, and political violence risks, offering shipowners more certainty and helping sustain trade flows amid intensifying Houthi attacks.
Market resilience is further tested by simultaneous disruptions at both the Strait of Hormuz and the Red Sea chokepoints, which have eliminated traditional fallback routes and forced a costly rerouting of cargo around the Cape of Good Hope. This detour adds approximately three weeks to transit times and overwhelms port infrastructure, leading to cargo insurance rates soaring from 0.6% to over 2% plus war risk premiums. These compounded disruptions expose the limitations of conventional dual-sourcing strategies that fail to map physical chokepoints, highlighting the necessity for integrated, end-to-end supply chain visibility that accounts for persistent geopolitical and climate-driven risks rather than isolated events.
By shifting the insurance and physical risk burden from commercial shippers to governments and producers through covert transit tactics supported by the US Navy, Middle Eastern oil exporters have effectively maintained steady oil traffic volumes and mitigated some insurance costs. This strategic risk management underscores a calculated approach where producers absorb heightened dangers to ensure market stability, while commercial shippers benefit from reduced exposure. Yet, the clandestine nature of these operations complicates tracking and risk assessment, posing ongoing challenges for traders and insurers attempting to accurately gauge volumes and hazards in this opaque environment.