Intermodal rail surges as shippers lock in cost savings
The gist
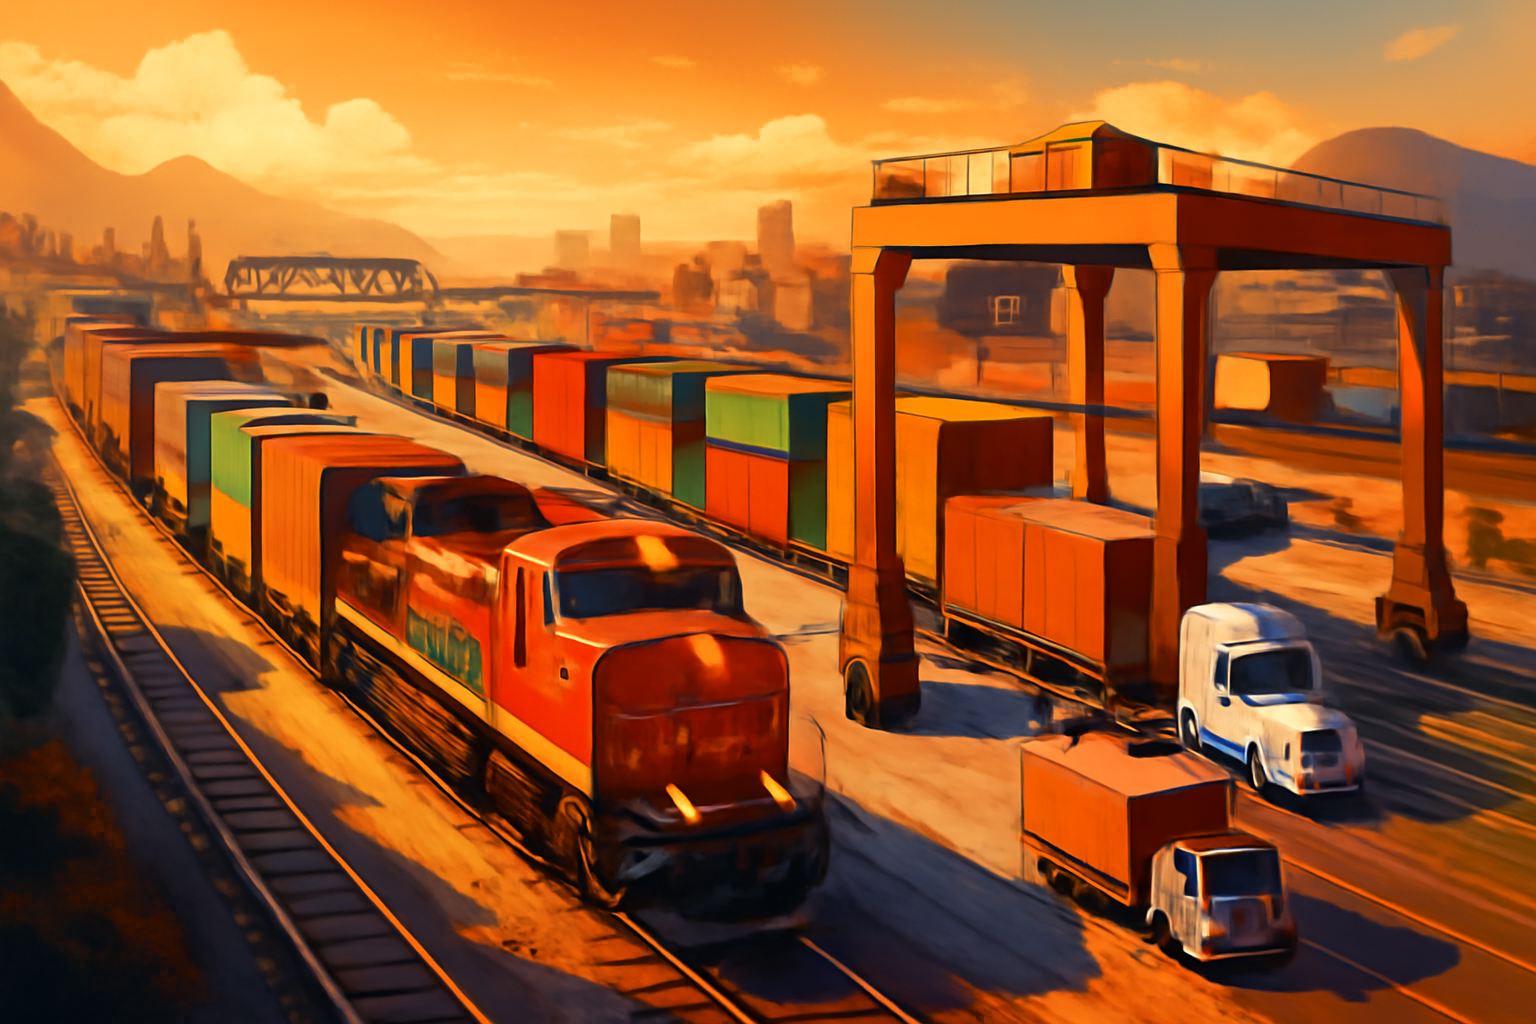
Intermodal rail is stealing the spotlight in 2026 as shippers lock in up to 44% cost savings and outmaneuver trucking headwinds.
What to know
- Domestic intermodal freight volumes surged 10-11% year-over-year in early 2026, fueled by tight trucking capacity and spiking fuel costs.
- Shippers are making intermodal a permanent supply chain staple, leveraging slower rail for better inventory management and huge savings—up to 44% on lanes like Atlanta to Chicago.
- The East Coast leads the charge with a 16% quarterly and 31% two-year volume jump, while both coasts and Mexico’s expanding networks are supercharging North American rail.
Permanent Shift to Rail
Shippers are embedding intermodal into their long-term logistics by reconfiguring inventory and supply chain strategies, cementing rail as a mainstay even after initial cost pressures subside.
The sustained growth in intermodal freight volumes is largely driven by a deliberate and gradual reconfiguration of supply chains, as shippers take months to fully integrate and adapt to intermodal solutions. This transition is not instantaneous; as noted in analyses from mid-2026, the lag between fuel price spikes and intermodal volume increases can be around two months, reflecting the complexity of adjusting freight flows and inventory strategies. For example, early 2026 saw shippers initially delay shifting due to softer truck market conditions, but by March, tightening truckload capacity and rising fuel costs catalyzed a significant modal shift toward intermodal transport.
Once shippers experience the benefits of intermodal freight—such as cost savings and reliable capacity—they rarely revert to previous truckload models, effectively cementing intermodal as a permanent fixture in their logistics mix. This is underscored by industry observations that familiarity breeds retention: 'Once you've experienced your model, you don't typically go back,' reflecting a broader trend where supply chain reconfiguration leads to lasting modal shifts. The discovery process, coupled with tighter trucking capacity, encourages shippers to prioritize intermodal as a dependable alternative, reinforcing its market share gains.
Shippers’ inventory management strategies have also evolved to support intermodal adoption, deliberately slowing delivery timelines to avoid excess warehouse stock and instead 'showing it in transit.' This approach aligns with retailers rebuilding inventories ahead of anticipated demand, leveraging longer transit times and slower rail options as a cost-effective solution. As ports experience strong import volumes, the flexibility afforded by intermodal rail allows shippers to balance inventory levels with supply chain responsiveness, further embedding intermodal within their operational playbooks.

Trucking Crunch Drives Rail Surge
Regulatory headwinds and soaring fuel costs have made intermodal rail the go-to for shippers seeking stability, with cost gaps and capacity constraints accelerating a lasting modal shift away from trucking.
Trucking capacity constraints, driven by regulatory challenges and rising fuel prices influenced by geopolitical factors such as the Strait of Hormuz, have significantly tightened the availability of drivers and increased operational costs. This has pushed shippers to increasingly rely on intermodal rail, which offers a more stable cost structure and better fuel surcharge management, allowing railroads to spread costs more effectively. As a result, domestic intermodal volumes surged by around 10-11% year-over-year, reflecting a supply-driven modal shift rather than pure demand growth, with carriers like JB Hunt and Hub Group reporting the ability to handle 15-20% more volume without new equipment investments.
The widening cost gap between truckload and intermodal transport is a critical driver of the modal shift, with trucking rates rising by over 17% year-over-year compared to a mere 0.3% increase in rail freight rates. Shippers are capitalizing on intermodal’s substantial savings, which can reach up to 30% on transcontinental lanes such as Los Angeles outbound and even 44% on traditionally challenging shorter hauls like Atlanta to Chicago. This cost advantage is amplified by intermodal’s slower fuel surcharge increases, making rail a more attractive option amid volatile fuel markets and elevated truckload contract rates that have surged by as much as 60% on some lanes.
Beyond cost savings, shippers are strategically using intermodal as a moving warehouse by intentionally slowing shipments to benefit from discounts and manage inventory more efficiently, especially during freight recessions or periods of supply chain reconfiguration. This approach, combined with adjusted scheduling to accommodate longer transit times, has lowered barriers to modal shift despite intermodal’s slower transit compared to trucking. Even as fuel prices have softened recently, many shippers remain committed to intermodal due to its reliable service levels and the persistent tightness in trucking capacity, suggesting a durable change in freight transportation preferences.
While intermodal’s growth is robust, the sector faces its own capacity and infrastructure constraints, particularly in drayage and terminal operations, which could lead to rate increases and pose risks for shippers heavily reliant on rail. Nonetheless, the sustained high volumes—reaching record levels in the first half of 2026—and the expectation of continued trucking capacity tightening indicate that intermodal will remain a preferred alternative for long-haul lanes anchored by major cities. Industry leaders foresee that this modal shift will temper traditional trucking demand surges, especially in peak seasons, as freight is pre-positioned on rail to hedge against ongoing truckload shortages.
East Coast Powers Rail Boom
The East Coast’s explosive intermodal growth is redefining freight flows nationwide, while both coasts and Mexico fuel a continent-wide race for rail market dominance.
By mid-2026, the East Coast has emerged as the powerhouse behind domestic intermodal volume growth, with a remarkable 16% year-over-year increase in the quarter and a 31% rise over two years, as highlighted by J.B. Hunt’s management who see "massive opportunities" for further conversion in this region. This surge is driven by shifting freight patterns where the traditional coastal-to-inland flows are giving way to more center-of-country movements, amplified by tightening trucking capacity that enhances railroad efficiency and fuels substantial year-over-year gains in intermodal volumes.
Despite the East Coast’s dominance in intermodal growth, West Coast activity remains robust, exemplified by the Port of Los Angeles recording its third-best month ever in TEUs handled, signaling sustained strength in transpacific and coastal freight flows. This regional dynamic underscores a competitive landscape where both coasts contribute to rail intermodal’s expanding footprint, even as the East Coast leads in domestic volume gains.
Fuel price increases and a tightening truck driver supply have made rail intermodal increasingly attractive across North America, propelling a 10.9% surge in U.S. intermodal volumes that outpaces overall rail traffic growth of 7.2%. This trend reflects a broader market shift where cost advantages are outweighing concerns over slowing rail speeds, enabling intermodal to capture market share from truckload transport and sustain strong, broad-based demand beyond traditional seasonal peaks.
Mexico’s expanding intermodal network is a critical yet often overlooked factor reshaping the North American freight landscape, complementing U.S. and Canadian rail traffic growth and reinforcing the continent-wide evolution toward intermodal transport. This regional expansion not only supports overall rail traffic trends but also intensifies competitive pressures, as cross-border freight flows increasingly leverage rail’s cost and capacity advantages.