MicroStrategy’s bitcoin sell-off rattles crypto markets, exposes dividend dilemma
The gist
MicroStrategy’s sudden Bitcoin sell-off has jolted crypto markets, exposing deep cracks in its high-stakes, debt-fueled dividend machine.
What to know
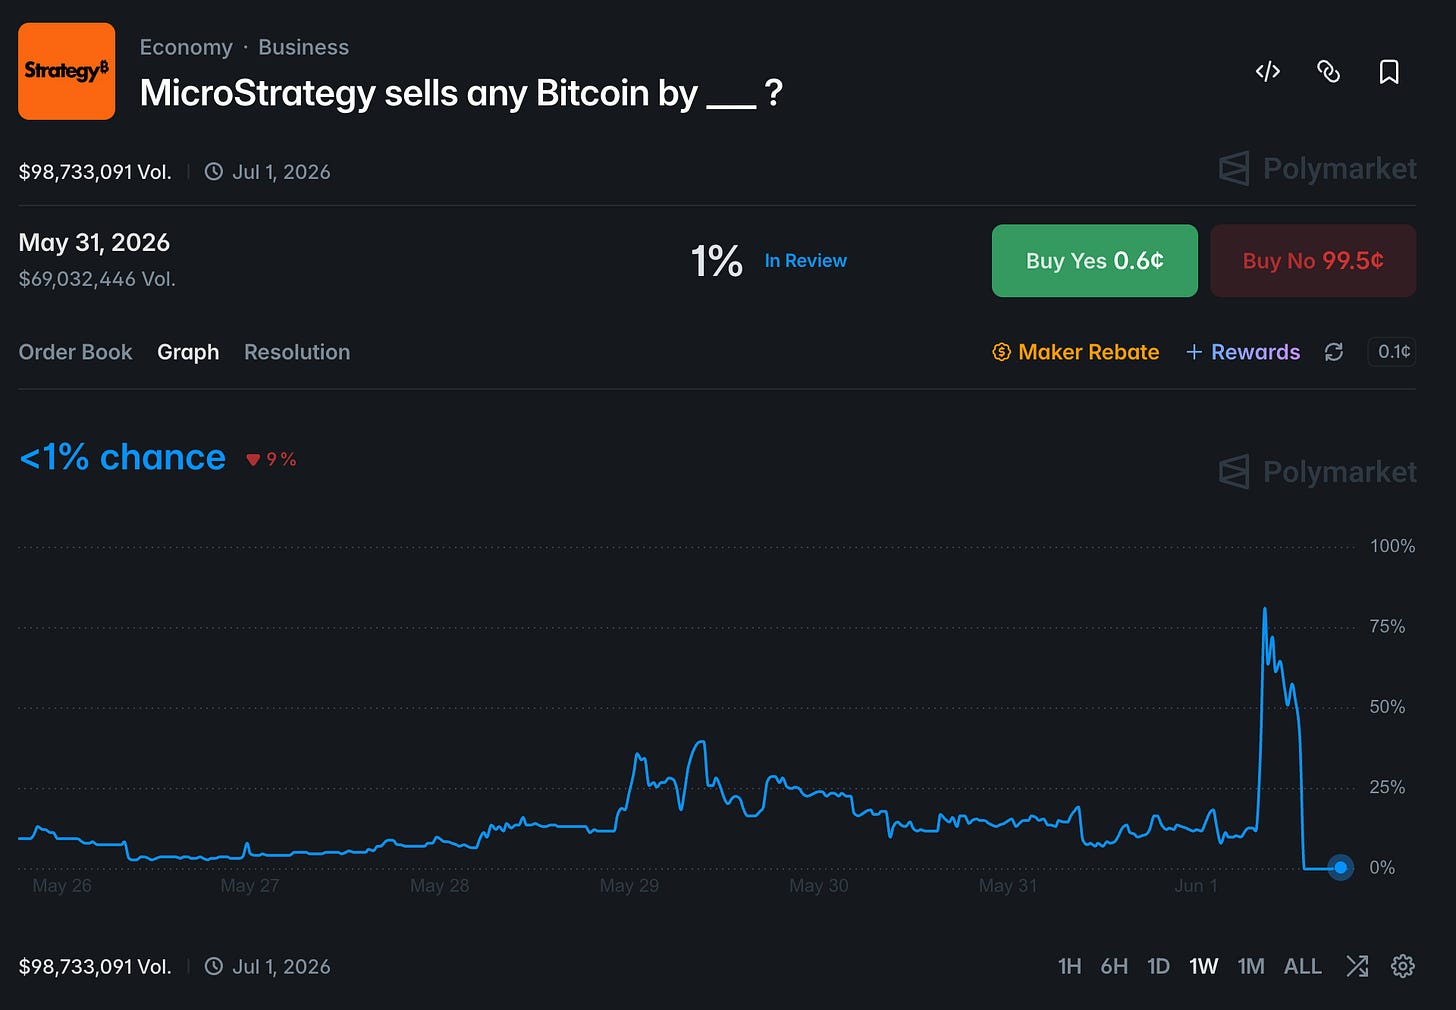
- Michael Saylor's MicroStrategy sold 32 BTC (≈$2.5M) in late May 2026, breaking its 'never sell' pledge to fund $1.7B in annual preferred dividends and fend off short-sellers.
- MSTR stock is struggling to maintain its $100 peg as Bitcoin tanks over 70%, with cash reserves covering less than six months of dividend payouts.
- The move sparked a 10% Bitcoin price drop and over $1B in market value loss, underscoring how leveraged corporate strategies are amplifying crypto’s volatility and systemic risk.
MicroStrategy Breaks Its Own Rules
Michael Saylor’s pivot from a strict 'never sell' Bitcoin policy to selective sales reveals a tactical playbook balancing dividend demands, market psychology, and regulatory scrutiny—redefining the company as an active allocator, not just a Bitcoin vault.
MicroStrategy, under Michael Saylor's leadership, has notably shifted from its long-standing 'never sell' Bitcoin policy to a more dynamic approach, actively selling small amounts of Bitcoin to fund preferred dividends and strategically 'inoculate the market' against negative speculation. This pivot was exemplified by the sale of 32 Bitcoin worth approximately $2.5 million between May 26 and May 31, 2026, marking the first sale since December 2022 and signaling a nuanced capital allocation strategy that balances dividend obligations with market messaging and potential tax considerations.
The Bitcoin sale serves multiple strategic purposes beyond mere dividend funding, including countering short-seller narratives that MicroStrategy would need to issue equity to meet dividend payments, thereby reinforcing the company's financial health and stability. As Saylor remarked, this move was intended to 'rip [the short sellers'] wings off,' demonstrating that the company remains robust despite mounting pressures, while also aligning with regulatory compliance under strict SEC oversight that now governs all public communications related to these transactions.
This strategic shift reflects a fundamental redefinition of MicroStrategy’s identity from a permanent Bitcoin holder to a state-contingent allocator, where Bitcoin holdings are treated as a reservoir that can be drained when accretive to shareholders. Despite the sale, the company maintains a substantial Bitcoin treasury of over 840,000 coins and employs a multifaceted funding approach—including issuing $128.3 million in common stock through an ATM program—highlighting that Bitcoin sales are one of several financial levers rather than a sign of distress.
However, this shift has sparked debate about the sustainability and risks of MicroStrategy’s dividend funding model, which relies heavily on maintaining investor confidence amid significant cash reserve depletion from debt retirements and large Bitcoin purchases. Analysts like Ryan Yoon of Tiger Research warn that the move 'shatters the core thesis' underpinning the company’s equity narrative, exposing structural vulnerabilities in its leverage-heavy Bitcoin strategy, especially as the preferred stock price hovers below the critical $100 peg needed to efficiently raise capital for further Bitcoin accumulation.
Dividend Pressure Fuels Risk Spiral
Mounting dividend obligations and a plunging Bitcoin price have left MicroStrategy’s shareholders exposed to liquidity crunches and forced asset sales, threatening a feedback loop of declining stock and crypto values.
MicroStrategy's shareholder risks have intensified as the company's stock price (MSTR) remains tightly coupled with Bitcoin's volatile price movements and the timing of dividend payouts. Despite efforts to maintain an 11.5% dividend yield to support a $100 stock peg, MSTR has struggled to hold this level, trading near $98.65 with only days before the ex-dividend date, limiting CEO Michael Saylor's ability to raise funds through share sales. This precarious balancing act underscores the financial pressure on the company as it attempts to sustain dividend obligations amid a plunging Bitcoin market.
The leveraged Bitcoin acquisition strategy employed by MicroStrategy has exposed shareholders to significant financial vulnerabilities, especially as Bitcoin prices have plunged over 70% from their 52-week highs. The company's preferred shares (STRC), trading below their $100 par value at around $96.90, threaten MicroStrategy's capacity to issue new shares to fund Bitcoin purchases and meet dividend obligations. With cash reserves dwindling to approximately $871 million—covering only about six months of the estimated $1.7 billion annual preferred dividend payments—the company faces mounting liquidity pressures that could force further Bitcoin or stock sales, potentially accelerating stock value declines.
Michael Saylor's recent sale of 32 Bitcoin for $2.5 million, despite his prior public commitment never to sell, signals potential financial stress and has shaken investor confidence, exacerbating shareholder risks. Critics have described MicroStrategy's heavy leverage and debt-fueled Bitcoin purchases as 'very dangerous' and even 'Ponzi-esque,' warning that the need to sell Bitcoin to meet yield obligations could create a vicious cycle pressuring both the stock and Bitcoin prices. This shift in strategy highlights the structural financial pressures inherent in MicroStrategy's approach, where dividend obligations and market volatility intertwine to threaten company stability.
The structural financial pressures from MicroStrategy’s dividend obligations on preferred shares and its leveraged Bitcoin holdings create a scenario where the common stock (MSTR) faces a real risk of collapsing to near zero, especially if Bitcoin prices fall below critical thresholds such as $26,100. While fears of insolvency have sparked panic in the market, some analyses suggest these are driven more by sentiment than immediate liquidity crises, given the company's substantial Bitcoin treasury valued in the tens of billions. Nonetheless, the unsustainable nature of increasing dividends to maintain arbitrary share price targets, combined with the company's shrinking cash reserves and heavy debt load, underscores the deep and multifaceted risks facing shareholders amid ongoing market volatility.

Corporate Moves Shake Crypto’s Core
MicroStrategy’s symbolic Bitcoin sale shattered market confidence, exposing the fragility of financialized crypto structures and amplifying systemic risk as leveraged strategies unwind under pressure.
MicroStrategy’s pivot from its long-held 'never sell' Bitcoin stance to liquidating 32 BTC at around $77,000 marked a seismic shift that shattered market confidence and amplified volatility. This move, though small relative to its holdings, triggered a 10% Bitcoin price drop and over a billion dollars wiped from BTC value, underscoring how symbolic actions by major corporate holders can unsettle markets that had been pricing in relentless accumulation. As markets grapple with the end of this accumulation phase, concerns mount over the systemic risks posed when dominant treasury strategies like MicroStrategy’s and BitMine’s eventually confront their limits.
The institutionalization of Bitcoin has morphed the asset from a pure bearer instrument into a complex issuer structure laden with liabilities, introducing layers of issuer, funding, wrapper, index, and credit risks. These financialized structures depend heavily on favorable funding conditions to sustain demand; when these falter, demand rapidly flips to supply, exacerbating price swings and market stress. Exchange-traded wrappers and swap desks have compounded this fragility by stacking claims upon claims, creating a delicate market architecture vulnerable to shocks and ETF outflows, as evidenced by the largest weekly Bitcoin ETF outflows of 2026 totaling $1.4 billion.
MicroStrategy’s leveraged Bitcoin carry trade—funded through debt and equity issuance to acquire more Bitcoin—has begun to unravel as the premium between its share price and Bitcoin holdings narrows, forcing the company to sell Bitcoin to meet debt and dividend obligations. This strategy, reminiscent of a mortgage REIT model but complicated by Michael Saylor’s evangelical commitment to never selling Bitcoin, heightens financial complexity and risk. The unwinding of such leveraged positions, combined with dividend pressures, not only threatens MicroStrategy’s stability but also amplifies broader market volatility and systemic risk within the crypto ecosystem.
The broader crypto market’s volatility is further intensified by reckless leverage gambits from heavyweights like Michael Saylor and Tom Lee, which have fueled wild price swings and sparked fears of a major downturn amid Bitcoin’s recent plunge. The excessive leverage accumulated during the late May rally triggered over 272,000 forced liquidations, acting as a volatility amplifier. Concurrently, institutional de-risking by major players such as Jane Street and Goldman Sachs—manifested in over $4.2 billion in Bitcoin ETF outflows over three weeks amid geopolitical tensions and rising bond yields—has compounded market instability, highlighting how intertwined leverage and institutional flows drive systemic vulnerabilities.