Stablecoin yield fight turns into a full-blown battle over bank deposits, Fed access and the next payments rail
The gist
Stablecoin yield has escaped crypto’s sandbox and turned into a fight over bank deposits, Fed access, and who gets to control the next payments rail.
What to know
- Banks say yield-bearing stablecoins could spark deposit flight on a headline scale of $6.6 trillion, forcing them to hold more liquidity and potentially cut lending.
- Regulators worry stablecoins could behave like shadow banks in a run: holders can redeem instantly, but reserve assets like Treasuries settle slowly, creating pressure on Treasury markets and bank reserves.
- Trump’s backing of Coinbase and yield-bearing tokens has intensified the battle, while Washington weighs bank-crypto talks, skinny master accounts, and the Clarity Act as the real competition shifts to instant-settlement rails.
Deposits Meet Liquidity Stress
**Yield-bearing stablecoins are turning deposit competition into a balance-sheet problem, forcing banks to hold more liquidity, absorb reserve swings, and potentially pull back on lending before any classic run even starts.**
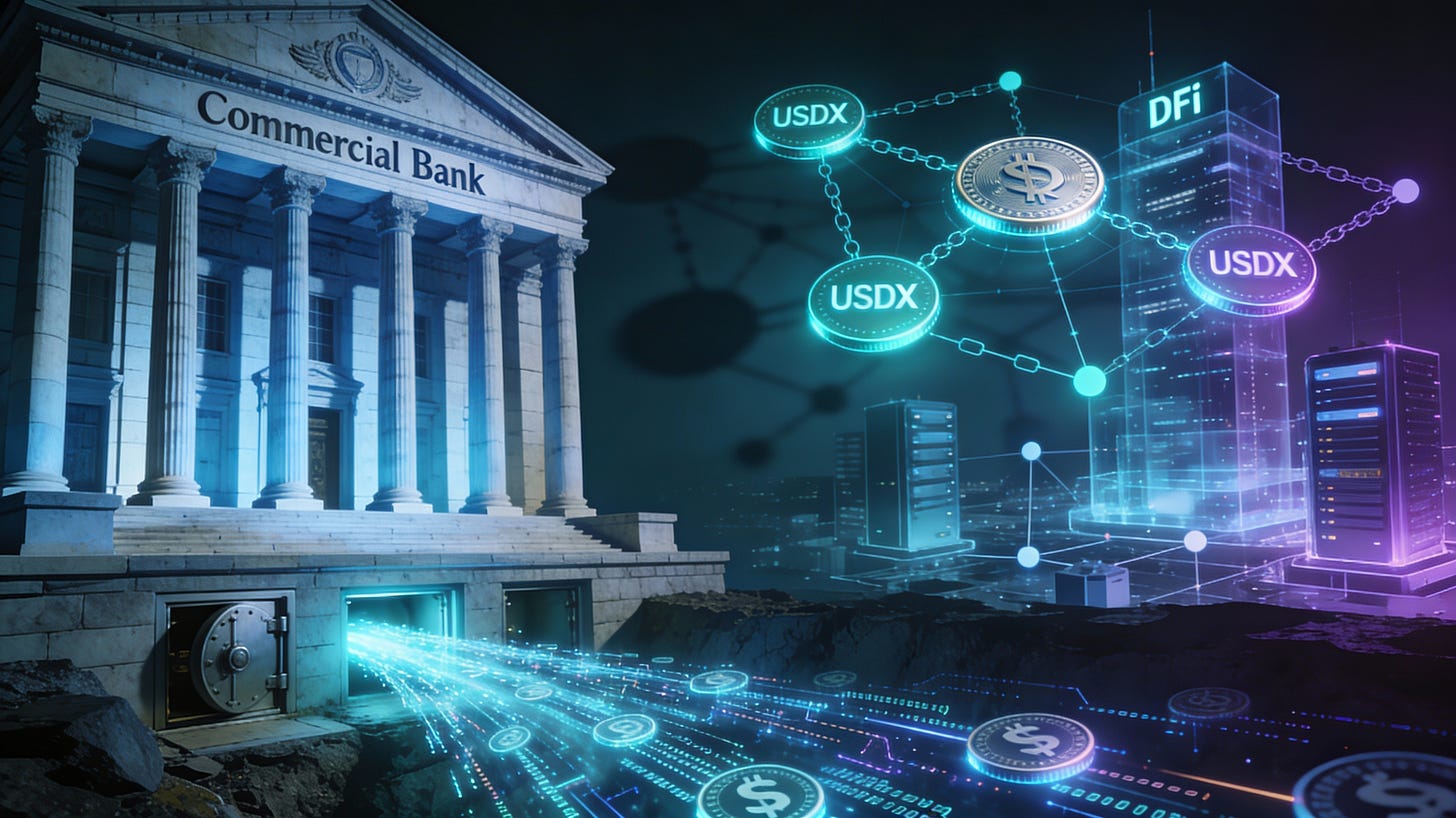
The banking industry’s alarm over stablecoins has shifted from abstract deposit competition to a concrete liquidity warning: if yield-bearing tokens can pay holders around 5% while banks offer almost nothing, deposits can migrate fast enough to force banks to raise reserves and curb lending. That is the logic behind the headline-grabbing $6.6 trillion deposit-flight fear, and it echoes the New York Fed’s framing that stablecoins are not just a funding threat but a reserves problem—one that can show up in Fedwire spikes, intraday reserve swings, and lower loan growth at banks servicing crypto flows. In other words, the worry is not simply that money leaves banks; it is that the plumbing of that exit makes banks hold more liquidity against a faster-moving liability base, weakening credit creation even before a full-blown run appears.
The run-risk case gets sharper once stablecoins are treated as a shadow banking system with no lender of last resort. By early 2026, the market had swollen to roughly $308 billion, yet the GENIUS Act explicitly bars issuers from Federal Reserve credit facilities, leaving them to rely on reserves that may be safe on paper but hard to liquidate in a panic: Treasury bills settle T+1, dealer balance sheets are constrained, and 24/7 blockchain redemptions can outrun a five-day-a-week market. That mismatch is why analysts describe the regime as a liquidity trap rather than a credit problem—when holders can redeem instantly but reserve assets cannot be sold just as quickly, the result is a self-reinforcing dash for cash.
The deeper systemic concern is that stablecoin stress would not stay inside crypto; it would spill into the Treasury market and back into banks that intermediate the reserve assets. BIS and NBER-style findings suggest outflows hit Treasury bill yields harder than inflows help them, while the New York Fed’s work links stablecoin issuance and redemption to wholesale payment surges and reserve volatility at partner banks—evidence that the ecosystem already transmits liquidity shocks through the banking system. Add the 2023 USDC-SVB episode, when Circle’s peg broke to $0.87 after Silicon Valley Bank held part of its reserves, and the policy debate starts to look less like a niche crypto squabble and more like a question of whether a large stablecoin run could force public backstops for the short-term funding markets that underpin the dollar itself.
Crypto Becomes a Political Fight
**What looked like a technical payments debate is now a Washington power struggle over who can pay yield, control deposits, and shape the rules for bank-crypto competition.**
What had been a wonky fight over payments plumbing has turned into a full-on political brawl. Trump’s public embrace of Coinbase in the stablecoin-yield showdown — while warning Congress to move fast on market structure or risk pushing the industry overseas — has given crypto firms a White House megaphone just as banks are escalating their own alarm over a potential $6.6 trillion deposit-flight threat. Jamie Dimon’s line that firms wanting to pay yield on stablecoin balances should "just become banks" captures the new fault line: this is no longer about abstract innovation, but about who gets to hold deposits, pay interest, and control the rails of money.
Banks are now lobbying as if stablecoins are a direct assault on their core franchise, not a side issue. Industry voices are framing opposition to the Clarity Act, skinny master accounts, and broader fintech competition as a defense of deposit-taking and lending — "we are deposit taking institutions who lend to the average American" — while the political calculus is splitting between megabanks, whose complaints are increasingly discounted, and community banks, whose concerns may land harder on Capitol Hill. That divide matters because it gives lawmakers cover to slow or reshape the bill even as regional banks argue they could actually win from the shift if they can offer more innovative products.
The regulatory response is becoming more explicit, but not more settled. Washington is now brokering direct talks between senior bank and crypto staff on stablecoin yield, while the Fed signals rules on skinny master accounts could arrive later this year and the OCC’s silence leaves a glaring gap in prudential standards. At the same time, the Clarity Act remains stuck in the weeds — with CBDC language likely to be stripped out, self-custody and AML/KYC fights adding new friction, and even crypto allies split over whether the framework is worth taking — underscoring that the policy battle has moved from rulemaking into a broader contest over what kind of financial system the U.S. wants to build.
The Rail Wars Go Direct
**Direct Fed access, skinny master accounts, and tokenized deposits are pushing the real battle beyond stablecoins themselves: the winner will be the network that can clear, settle, and hold liquidity fastest under stress.**
The next payments rail is no longer a crypto side quest; it is becoming a fight over who gets to plug directly into the plumbing of money. Kraken’s direct Fedwire access as the first digital asset bank in the U.S. to connect to the Fed, alongside the idea of a "Skinny Master account" that offers payments-only access without reserves, discount-window support, or overdraft privileges, shows how sovereign rails can be selectively opened to private actors. That matters because it changes the old "choke point" dynamic: if a firm can settle directly with the Fed, it is harder to cut off, and the real competition shifts from who can issue a token to who can clear and settle on the most trusted network.
Stablecoins are pushing that contest into the open by promising not just faster transfers but a wholesale rewrite of settlement economics. The CFO-facing pitch is blunt: legacy SWIFT leaves money "trapped in transit" for 3 to 5 days, exposing firms to 1.5% to 7.5% FX volatility, while stablecoin rails can neutralize liability in under 3 seconds, collapse routing, compliance, execution, and monitoring into one programmatic event, and even park idle capital in tokenized RWAs yielding around 5%. In other words, the fight is no longer about whether payments can be digitized; it is about whether the new rail can also control liquidity, yield, and capital deployment.
That is why banks and central banks are racing to build their own versions of the same thing before stablecoins define the market for them. In the U.S., the debate now includes CBDCs and bank-issued tokenized deposits, with JPM Coin-style products and bank deposit tokens on chains like Coinbase’s Base offering 24/7 settlement without correspondent banks, while still keeping redemption inside the regulated banking system. The logic is simple: in stress, par redemption, bank supervision, and access to central bank facilities may matter more than the smart contract itself, which is exactly why stablecoins’ institutional niche could shrink if enough banks make deposit tokens feel as fast as USDC without the issuer risk.
Europe and Asia are treating the same infrastructure race as a sovereignty problem, not just a fintech upgrade. The ECB’s Appia roadmap is building tokenized wholesale euro markets around central-bank settlement, with Pontes due in Q3 2026, DLT-issued securities already eligible as refinancing collateral, and a digital euro pilot following in 2027; meanwhile, Hong Kong is pushing banks to rethink business models through its DLT incubator and is set to license bank-linked stablecoin issuers like HSBC and a Standard Chartered-led venture under rules that require 1:1 HQLA reserves and T+1 par redemption. Across both regions, the message is the same: if the dollar stablecoin stack is going to dominate, it will have to run on rails that regulators, central banks, and incumbent banks can still control.