Sticker shock: new cars now a playground for the wealthy as average buyers shift gears
The gist
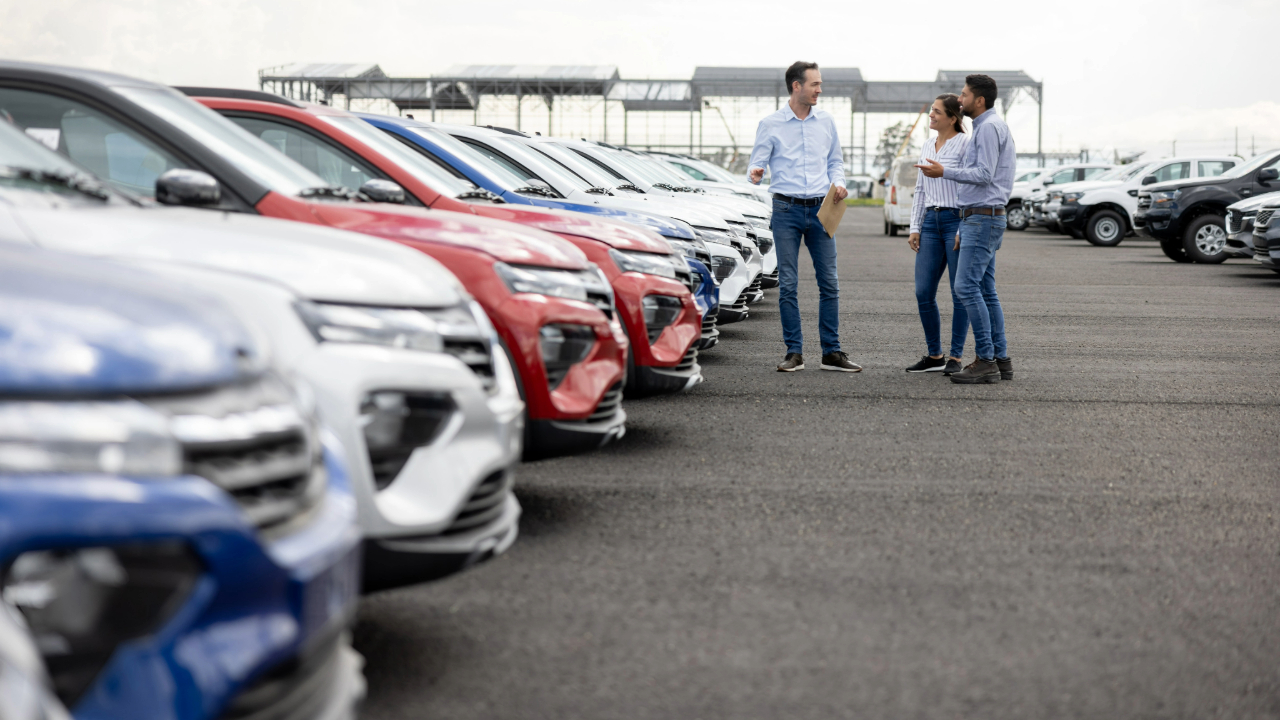
New cars have become a luxury playground for the wealthy, leaving average Americans stuck in the used lot as prices, payments, and ownership costs soar to record highs.
What to know
- By early 2026, buyers earning over $200,000 make up 29% of new car sales, while those under $100,000 have dropped to 37%.
- The average new car price is now $51,000, with monthly payments at a record $770 and loan terms stretching up to 96 months.
- With 2 million buyers priced out, used EV sales are up 26% and the average vehicle age has hit a record 13 years.
Luxury Divide Widens
As new cars morph into luxury goods, automakers increasingly cater to high earners while millions of average Americans are shut out of the showroom.
By early 2026, the U.S. new car market has become increasingly polarized along income lines, with affluent buyers earning over $200,000 accounting for 29% of new-car purchases, up from 18% in 2020, while those earning less than $100,000 have shrunk from 50% to 37%, according to Cox. This shift has effectively transformed new vehicles into luxury goods, as Mark Barrott of Plante Moran highlights, creating a K-shaped market where a third of Americans cannot afford new cars, and automakers now rely heavily on wealthy consumers to sustain sales.
The average MSRP for new vehicles has surged to around $51,000 by 2025, driven largely by the popularity of high-end trucks, SUVs, and large cars that can approach $80,000, pricing out many middle- and lower-income buyers and leading to the near disappearance of entry-level models. Ford CEO Jim Farley cautions that while these pricier vehicles boost profitability, they risk shrinking the overall market as over 20% of buyers now commit to monthly payments exceeding $1,000, signaling potential consumer pullback amid rising insurance and inflationary pressures.
Affordability challenges extend beyond sticker price, as lower-income consumers struggle not only with vehicle costs but also with escalating expenses for insurance, fuel, and maintenance. Insurance premiums have risen sharply due to costly repairs and advanced vehicle technology, compounding the burden amid soaring costs for essentials like rent, food, and energy. This dynamic has fragmented the market further, with higher-income groups dominating used vehicle purchases while lower-income consumers increasingly trade down or delay ownership, contributing to the record-high average vehicle age of 13 years on U.S. roads.
Despite the overall high and stable average transaction price hovering near $50,000, there is a notable consumer pivot toward more affordable segments such as subcompact and midsize SUVs, which saw sales increases of over 23% in mid-2026. Electric vehicles, while becoming somewhat more accessible due to declining prices and generous incentives averaging 13%, still maintain an average transaction price above $56,000, underscoring persistent stratification. Automakers’ disciplined incentive spending at about 7% of ATP reflects a strategic focus on profitability that may limit affordability gains for entry-level buyers, reinforcing the bifurcation between luxury and value-oriented market segments.



Loans Stretch, Risks Rise
Record-length car loans and soaring insurance costs are masking financial strain, with more buyers risking negative equity just to keep payments affordable.
By early 2026, escalating new vehicle prices and borrowing costs have pushed average new-car monthly payments to a record $770, with used-car payments averaging $560, according to Edmunds.com. This surge is compounded by a 55% increase in insurance and repair expenses since the pandemic, as reported by the National Automobile Dealers Association, creating a multifaceted affordability challenge for consumers. However, larger tax refunds averaging $3,521 have provided some cushioning, softening the financial blow amid these rising ownership costs.
Automakers and lenders have adapted to these affordability pressures by extending loan terms—commonly to 66 or 72 months, with some banks pushing up to 96 months—to keep monthly payments manageable. This strategy, while increasing the risk of negative equity (which has risen 35% to an average of $5,105 in used-car trade-ins), is defended by Capital One Auto President Sanjiv Yajnik, who argues that longer loans make sense when consumers hold vehicles longer to build equity and maximize use, challenging the notion that 'forever loans' necessarily cause financial strain.
Despite the rise in median monthly payments from $390 to $525, 80% of financed buyers maintain payments below 15% of their income, reflecting cautious consumer financing behavior amid high vehicle prices and interest rates. Nonetheless, dealerships face challenges as higher rates and longer loans lead to fewer customers financing vehicles and an uptick in cash deals. To counteract extended ownership cycles that delay trade-ins, dealers increasingly promote leasing—offering lower monthly payments by $200 to $300—to keep customers returning sooner and maintain turnover.
The growing stratification of the market is underscored by the soaring prices of top-trim family SUVs, which now exceed $100,000, with models like the Chevrolet Tahoe High Country and Cadillac Escalade pushing well past this threshold. Manufacturers have raised the price ceiling through tactics such as standardizing expensive engines on top trims, eliminating lower-cost trims, and charging luxury-brand prices for appearance packages, driving the average new vehicle transaction price close to $49,220. This pricing dynamic pressures loan-to-income ratios further and encourages consumers to stretch financing terms and monthly payments, with more than one in five buyers now paying $1,000 or more monthly.
Cash-First Car Culture
Squeezed by financing costs, more buyers—especially younger and financially savvy—are trading up slowly with cash, prioritizing savings over new car debt.
By early 2026, faced with new car prices nearing $50,000, lower- and middle-income consumers increasingly turned to used vehicles and lower-trim models as cost-saving strategies. Automakers and lenders adapted by extending loan terms, approving more subprime borrowers, and promoting certified used cars and entry-level trims to keep monthly payments manageable. This shift reflects a market stratification where affordability pressures push buyers toward older or less equipped vehicles, reshaping purchasing patterns and financing options.
Many consumers adopted cash purchasing strategies to avoid the pitfalls of financing and preserve emergency funds, as exemplified by Scott’s decision to sell a 2003 Toyota requiring $8,500 in repairs and instead buy a $6,000–$7,000 used car with cash. Financial advisors like Dave Ramsey emphasize ‘paying yourself’ by saving monthly car payment equivalents to build cash reserves for future vehicle upgrades, enabling stair-step improvements without incurring interest. This approach underscores a broader trend of prioritizing liquidity and wealth-building over depreciating assets.
Younger buyers, such as 19-year-old entrepreneur Sam, illustrate prudent budgeting by allocating separate funds for emergency savings and car purchases—$10,000 each—and leveraging future earnings to increase purchasing power without resorting to loans. Supported by financial literacy and parental guidance, Sam’s preference for buying a reliable $10,000 used car in cash rather than financing a $20,000 vehicle highlights the growing emphasis on delayed gratification and informed decision-making amid affordability challenges.
Despite the appeal of used cars, consumers face challenges as 2- to 3-year-old models often retain prices close to new vehicles, forcing buyers to consider older, higher-mileage cars to find meaningful savings. This dynamic, coupled with concerns about hidden maintenance costs, influences purchasing decisions and budgeting strategies, as seen in a family earning $130,000 who balances car investments to not exceed half their take-home pay while maintaining substantial emergency funds. Such trade-offs reflect the delicate balancing act consumers perform to maintain financial health while navigating a stratified auto market.
Used EVs Surge Ahead
Soaring gas prices and a flood of off-lease EVs are fueling a boom in used electric vehicle sales, making them a practical choice for cost-conscious drivers.
By early 2026, rising gasoline prices have notably shifted consumer interest toward used electric vehicles (EVs), with searches on Cars.com jumping 26% and used EV sales increasing to 93,500 in Q1, even as new EV purchases declined. This surge is partly driven by a growing inventory of used EVs from expiring 2023 leases, which is expected to foster more competitive pricing and improve accessibility for budget-conscious buyers.
The financial appeal of EVs is underscored by significant annual savings in operating and maintenance costs—estimated between $1,000 and $2,000 depending on electricity prices—which become even more compelling as gasoline prices surged from $3.41 to $4.14 per gallon in just one month. Drivers covering 25,000 miles annually could save over $3,000 by switching to EVs, turning what was once an ideological choice into a pragmatic economic decision, as one analysis aptly put it, 'When gas gets expensive, ideology takes a coffee break and operating costs start making the sales pitch.'
The volatility of fuel prices is reshaping consumer behavior from focusing on driving frequency to vehicle choice, with hybrids and EVs gaining traction as practical solutions to mitigate exposure to petrol price swings. Hybrids, in particular, offer a popular compromise by combining familiar petrol engines with improved fuel economy, especially appealing to those in regions with developing charging infrastructure, while EVs provide the added benefit of more predictable and generally lower long-term running costs, aiding households in managing budgets amid ongoing fuel market uncertainties.
This shift toward alternative powertrains is not confined to the U.S.; global markets like the Philippines are also experiencing increased interest in hybrids and EVs as fuel price fluctuations continue to influence daily transportation decisions. Despite infrastructure challenges, urban commuters in such regions are beginning to embrace these technologies, signaling a broader, worldwide trend where rising fuel costs are accelerating the adoption of cleaner, more economical vehicle options.
Affordability Squeezes the Market
Despite strong sales among the wealthy, millions are sidelined by high prices and shrinking discounts, forcing Americans to keep their aging vehicles longer than ever.
By mid-2026, the U.S. auto market demonstrated notable resilience despite persistent economic headwinds such as high fuel prices, inflation, and geopolitical tensions. Cox Automotive’s May forecast projected new-vehicle sales rising to a 16.1 million pace, buoyed largely by affluent buyers less affected by economic pressures, while Jeremy Robb highlighted that sustained economic and stock market stability remains critical to maintaining these positive sales trends amid volatility. This resilience is underscored by steady new car sales year-over-year, supported by wealth effects from the stock market, even as used car sales saw only slight declines from a strong previous year.
Automakers have strategically adapted to affordability pressures by expanding their electric and hybrid vehicle offerings, which have become key drivers of market stability. Jeremy Robb noted the increasing presence of EVs in the marketplace despite inflationary cost pressures, while hybrids have emerged as a cost-effective alternative amid rising gas prices, holding up demand in 2026. Kelley Blue Book data from June shows EV prices declining for the sixth consecutive month, aided by elevated incentives at 13%, well above the industry average, reflecting a deliberate shift in product mix and pricing strategies to attract budget-conscious buyers.
Despite this resilience, affordability challenges have effectively priced out approximately 2 million potential new vehicle buyers compared to five years ago, constraining overall market growth. Inventory shortages and record-high MSRP prices, particularly for popular models like the Toyota RAV4 and Ford F-150, have limited consumer options and suppressed typical seasonal discounts, as noted in July analyses. This scarcity, combined with a product mix skewed toward expensive large SUVs pushing average new car prices above $50,000, has led many consumers to hold onto older vehicles longer—the average vehicle age reaching a record 13 years—further dampening new vehicle turnover.
Looking ahead, while the market showed strong seasonal performance with a 16.5 million SAAR and a 7.6% year-over-year sales increase in June, industry forecasts predict a contraction in new vehicle sales in the latter half of 2026 due to ongoing economic uncertainty, affordability constraints, and supply issues. Automakers are responding by focusing on more affordable segments, with subcompact and midsize SUVs experiencing significant sales growth as consumers prioritize value and utility. Meanwhile, disciplined incentive spending—around 7% of average transaction price—reflects a balancing act between maintaining profitability and stimulating demand amid a challenging market environment.