UPS beats on earnings, but margin worries spook investors
The gist
UPS is beating estimates and shedding low-margin business, but shrinking profit margins and a murky recovery plan have Wall Street holding its breath.
What to know
- Q2 2026 adjusted EPS hit $1.76, revenues jumped 7.5% to $22.8B, but GAAP net income was slashed in half as margins shrank to 2.6%.
- UPS is aggressively automating—routing 68.5% of U.S. volume through robot-powered hubs, cutting 78,000 jobs, and targeting $3B in annual savings.
- Big investors are split: First Trust added $357M in UPS stock, but Modera trimmed its stake—mirroring market skepticism after lackluster margin guidance.
Profit Growth Masks Margin Pain
UPS’s revenue and EPS gains are overshadowed by a dramatic margin collapse and hefty restructuring charges, raising doubts about the long-term quality of its earnings.
UPS's Q2 2026 earnings demonstrated modest yet tangible growth, with adjusted EPS surpassing estimates at $1.76 against a consensus of $1.65 and revenues climbing 7.5% year-over-year to $22.8 billion. This performance was fueled by a strategic pivot away from low-margin Amazon volume, which, despite shedding $5 billion in annual revenue, enabled a 6.0% increase in the U.S. Domestic segment revenue, driven by a 9.3% rise in revenue per piece. However, this top-line growth came at a steep cost, as GAAP net income more than halved to $604 million and net margins compressed sharply from 6.0% to 2.6%, underscoring persistent profitability challenges amid ongoing restructuring charges and margin pressures.
The company’s aggressive cost control measures and transformation efforts, including workforce reductions of nearly 78,000 positions and 117 facility closures, have been central to its near-term earnings outlook. These initiatives contributed to $4.5 billion in expense reductions and a 28% decrease in cost per piece, supporting margin improvement in specialized segments like Supply Chain Solutions, which expanded operating margins from 8.0% to 10.2%. Yet, the heavy restructuring costs—reflected in $1.17 billion of pre-tax transformation charges—alongside margin compression, raise questions about the sustainability of profitability gains and the quality of earnings, especially given the reliance on adjusted operating profit figures that mask underlying GAAP results.
Looking ahead, UPS projects full-year adjusted EPS of $7.22 on revenues of $91.2 billion, implying a need for significant earnings acceleration in the second half of 2026. While the company targets approximately $3 billion in program cost savings for the year to sustain its leaner cost structure, the absence of explicit margin recovery drivers in guidance fuels skepticism about the durability of profitability improvements. Additionally, long-term forecasts anticipate revenue growth to nearly $98 billion and earnings of $6.8 billion by 2029, though some estimates remain more cautious, reflecting market concerns over competitive pressures and the risk of margin erosion despite UPS’s strategic investments and cost discipline.



Amazon Exit, Healthcare Play
By slashing Amazon volume and doubling down on healthcare and SMBs, UPS is trading scale for higher-margin business, betting its future on specialized logistics and automation.
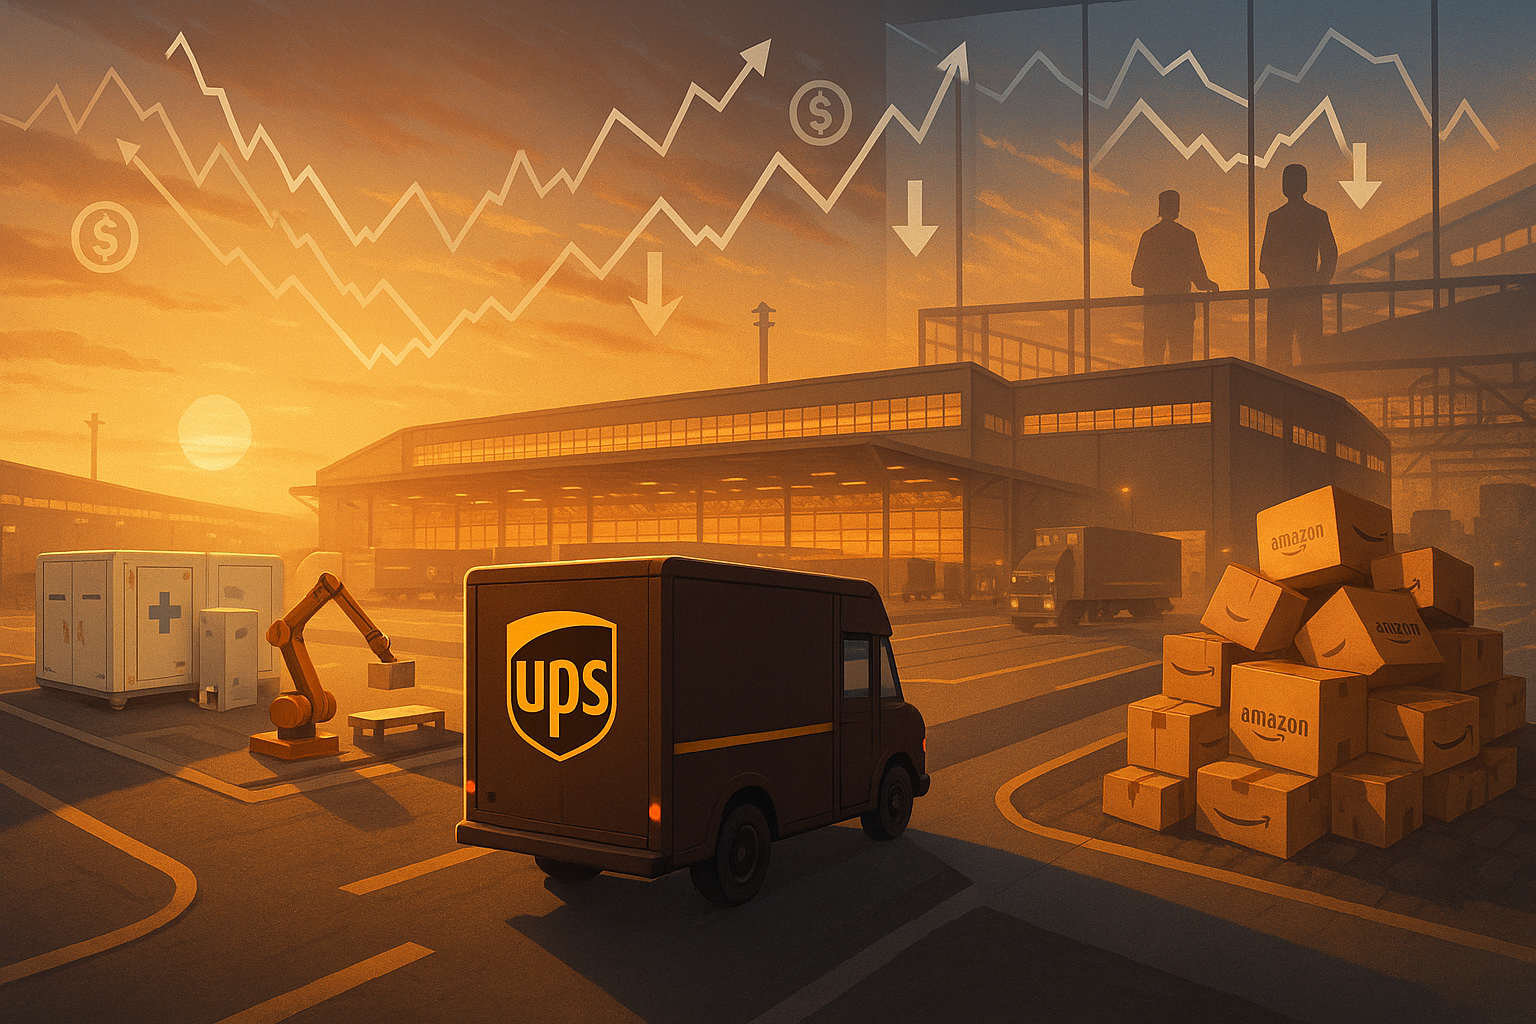
UPS is deliberately reducing its reliance on low-margin Amazon shipments, aiming to cut these volumes by over 50% by mid-2026, which translates to shedding approximately two million daily packages and about $5 billion in annual revenue. CEO Carol Tomé emphasizes that this 'glide down' is complete, allowing UPS to replace dilutive, low-margin e-commerce parcels with fewer but higher-margin shipments, particularly in healthcare and SMB sectors, which offer better unit profitability and have driven a 9.3% increase in revenue per piece despite overall volume declines.
Central to UPS’s strategic pivot is the 'Network of the Future' initiative, the largest network reconfiguration in company history, which focuses on funneling volume into highly automated hubs and embedding robotics, AI, and RFID sensing technology across its logistics chain. By Q2 2026, 68.5% of U.S. volume flowed through automated buildings, reducing cost per piece by 28%, while AI-powered digital twins and real-time data enable UPS to optimize operations holistically, accounting for variables like weather and labor, thereby enhancing service reliability and customer retention.
UPS is aggressively expanding its footprint in higher-margin verticals, notably healthcare logistics, where it has invested $48 million in temperature-controlled warehouses supporting 27 facilities worldwide. This sector, projected to reach nearly $40 billion by 2033 with an 8.3% CAGR, is growing faster than the 6% market average due to UPS’s unique ownership of all necessary assets for control and visibility in complex supply chains, insulating the company from commoditized parcel delivery pressures and driving Supply Chain Solutions segment margins from 8.0% to 10.2%.
UPS’s shift away from residential e-commerce volumes toward clustered business deliveries further enhances profitability by enabling more efficient route density and cost savings. Industry experts like Lisa Ellram highlight that business deliveries allow drivers to make multiple stops within industrial parks, contrasting with the scattered nature of residential deliveries, especially in rural areas. This transition aligns with a broader industry trend, as noted by Jason Miller, where carriers prioritize maximizing profit per shipment over sheer volume, a necessity driven by Amazon’s growing self-delivery network reducing third-party package volumes.

Automation Drives Leaner UPS
Massive automation and facility closures are reshaping UPS’s network, enabling sharp cost reductions and setting the stage for sustained margin improvement and shareholder returns.
UPS's strategic emphasis on cost controls and automation is reshaping its operational footprint to sustain profitability amid modest earnings growth. By the end of 2026, the company plans to shutter approximately 150 older, less automated facilities, focusing instead on higher-margin segments such as healthcare and small business deliveries, while deliberately scaling back low-margin e-commerce residential routes. This targeted facility consolidation and portfolio shift underscore UPS's commitment to operational efficiency and margin enhancement.
Automation investments are central to UPS’s drive for operational efficiency, with 68.5% of U.S. volume processed through automated buildings by Q2 2026, resulting in a 28% reduction in cost per piece compared to conventional facilities. Innovations like cost-effective RFID labeling have enhanced package tracking and data integration, enabling real-time operational insights that support tighter margin management and capacity planning. These technological upgrades position UPS to handle future growth with improved productivity and a leaner cost structure.
UPS’s aggressive cost-cutting initiatives have removed roughly $4.5 billion in expenses tied to lower-margin Amazon volume, contributing to a leaner, more profitable network. The company targets about $3 billion in program cost savings for 2026, a critical benchmark that will validate the durability of its operational efficiency efforts. Capital returns, including a quarterly dividend of $1.64 per share and ongoing share repurchases, are closely linked to UPS’s ability to sustain cash generation through these cost-reduction strategies.
Investor Split, Dividend Defended
Major shareholders are divided on UPS’s trajectory as management pledges to protect dividends despite market skepticism and a rocky margin outlook.
The recent institutional ownership shuffle at UPS underscores a nuanced investor sentiment, with Modera trimming its stake by $9 million while First Trust made a substantial $357 million purchase, signaling a divergence in confidence levels among major shareholders. This shift reflects contrasting assessments of UPS's strategic direction and financial resilience amid ongoing operational adjustments.
CEO Carol Tomé has been proactive in addressing shareholder concerns by emphasizing dividend protection as the company's foremost priority despite recent cash flow challenges, notably a one-time $1 billion cost linked to the driver choice buyout program. Tomé reassures that this significant expense is behind UPS and that full-year cash flow is projected to comfortably exceed dividend obligations, reinforcing the company’s commitment to returning value to investors.
Despite these reassurances, UPS shares experienced a knee-jerk decline following the earnings outlook, reflecting market skepticism about the sustainability of margin improvements and volume growth. While Tomé highlighted that the reduction of low-margin Amazon business is complete and the company is pivoting to higher-margin parcels, investors remain cautious, as evidenced by the stock’s tumble after underwhelming profit margin projections.