Yen intervention falters as rate gap fuels global jitters
The gist
Despite a rare $100 billion US-Japan intervention, the yen’s comeback fizzled as relentless rate gaps and global jitters kept the currency on the ropes.
What to know
- Japan and the US spent nearly $100 billion buying yen, but the currency only strengthened from 162 to 158—well short of the critical 155 mark.
- A stubborn 1% vs. 3.5–3.75% interest rate gap fuels massive yen carry trades, making stabilization efforts an uphill battle.
- Japan’s $1 trillion in US Treasuries means aggressive yen support could spike global yields and rattle markets, so Treasury sales were avoided—for now.
Coordinated Action, Limited Impact
Despite an unprecedented US-Japan intervention and nearly $100 billion spent, the yen’s brief rally exposed deep-rooted structural weaknesses that even global cooperation can’t quickly fix.
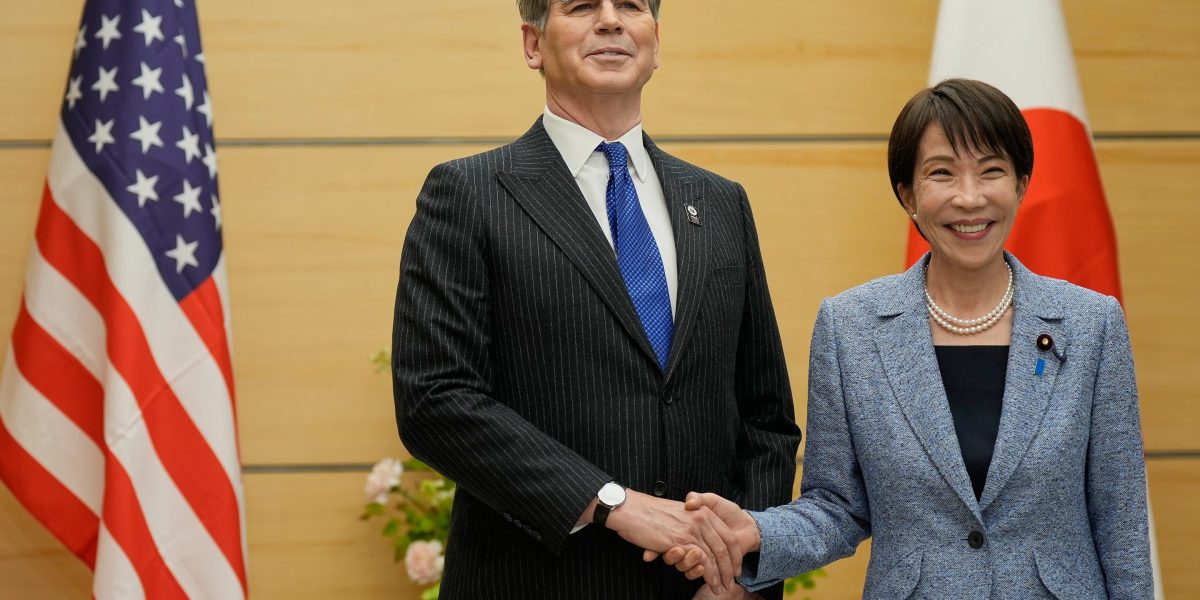
The rare US-Japan coordinated intervention to stabilize the yen marked a significant escalation in currency market cooperation, with the US Treasury supporting the yen for the first time since 1998 by purchasing yen alongside Japan’s massive intervention spending nearly $100 billion within 48 hours. Despite this unprecedented joint effort, the immediate impact was limited as the yen only strengthened from around 162 to 158, failing to break the critical 155 support level that authorities are determined to defend, reflecting the persistent structural challenges underpinning yen weakness.
The intervention’s mechanics revealed nuanced strategic choices: the US sold euros rather than dollars to buy yen, suggesting a potentially softer immediate commitment but also hinting at broader G7 coordination involving European policymakers. This move, coupled with Treasury Secretary Scott Bessent’s call for expanding liquidity facilities like the FIMA Repo Facility, signals readiness for further joint actions, though analysts caution that such interventions address symptoms rather than the root causes of yen weakness, notably the wide interest rate differential between Japan’s 1% and the US’s 3.5-3.75%.
Market reactions to the intervention were swift and volatile: hedge funds cut their yen short positions in response to the joint action, yet the yen’s gains proved fragile as half were quickly erased amid ongoing downward pressure from interest rate gaps and positioning. This volatility underscores concerns that without fundamental shifts, such as anticipated Bank of Japan rate hikes in the fall, the intervention may only temporarily stabilize the yen, while also raising alarms about potential spillovers into US Treasury markets if Japan resorts to selling its massive US bond holdings to fund yen support.

Japan’s Policy Trap
Decades of ultra-low rates and demographic stagnation have locked Japan into a cycle where currency interventions are undermined by persistent carry trades and the risk of destabilizing its own bond market.
Japan's persistent low interest rates, maintained near 1% by the Bank of Japan to combat decades of deflation and an aging population, have entrenched structural weaknesses that limit the effectiveness of currency interventions. Since 2012, these demographic challenges and weak domestic demand have pressured the yen downward, creating a policy dilemma where raising rates could stabilize the currency but risk fiscal and bond-market instability due to higher debt servicing costs.
The widening interest rate gap between Japan's 1% policy rate and the US Federal Reserve's 3.5%–3.75% range has fueled a decades-long yen carry trade, where investors borrow yen cheaply to invest in higher-yielding US Treasuries yielding near 4.75% to 5.28%. This dynamic not only sustains persistent yen weakness but also discreetly supports US deficit financing, making the yen's structural depreciation a critical factor beyond Japan's domestic economy.
Despite Japan's modest policy rate increase to 1%, the yen carry trade remains robust due to the still substantial interest rate differential, though the margin for error has narrowed amid increased market volatility and larger official interventions. This persistent gap incentivizes investors to offload yen in favor of higher-yielding dollar assets, as Helen Popper notes, 'When there are high interest rates in the US, people do not want to sit on assets denominated in yen that are earning low interest rates.'
Structural challenges extend beyond interest rates to include the enormous scale of yen-linked foreign-exchange derivatives—running into the trillions as reported by the Bank for International Settlements—and complex transmission channels between government and private investors. These factors obscure the speculative portion of the yen carry trade, complicating intervention efforts, which are most effective only when paired with credible policy shifts addressing fundamental interest rate differentials and capital flows.
Treasury Markets on Edge
Japan’s massive US Treasury holdings make the yen’s fate a global risk, as any forced bond sales to support the yen could send shockwaves through US yields and worldwide financial markets.
Japan’s status as the largest foreign holder of U.S. Treasuries—boasting over $1 trillion in holdings—places it at the epicenter of potential financial turbulence. As Ed Yardeni vividly describes, the global financial system resembles a “giant Jenga tower” with the yen as a critical load-bearing piece, meaning any significant yen instability risks triggering large-scale Japanese Treasury sales. Such sales would depress bond prices and elevate yields, thereby increasing U.S. government borrowing costs and exerting upward pressure on mortgage rates, corporate borrowing, and consumer credit, while also straining financial institutions holding long-duration bonds.
The coordinated U.S.-Japan intervention—characterized by the U.S. selling euros rather than dollars and Japan borrowing against rather than selling its Treasury holdings—reflects a strategic effort to stabilize the yen without directly destabilizing U.S. Treasury markets. However, this delicate balancing act underscores deeper geopolitical and fiscal challenges, including the widening interest rate differential between the Federal Reserve’s 3.5–3.75% range and the Bank of Japan’s 1% policy rate, which sustains carry trade incentives that complicate yen stabilization and risk spillovers into U.S. yields and global markets.
External shocks, particularly from Middle East energy tensions, exacerbate the fragility of this interconnected system by driving up oil prices, which worsen Japan’s trade balance and inflation, thereby complicating the Bank of Japan’s monetary policy and increasing stress in Japan’s government bond market. This dynamic feeds back into the U.S. economy by elevating inflation expectations, delaying Federal Reserve easing, pushing Treasury yields higher, and strengthening the dollar—factors that collectively reinforce downward pressure on the yen and deepen global financial market vulnerabilities.
Historical precedent and recent market signals reveal that yen interventions alone offer limited durable relief without complementary shifts in U.S. interest rates. Despite cooler U.S. inflation data and falling Fed rate expectations, the yen’s continued depreciation signals entrenched structural weaknesses that threaten to exacerbate risks to U.S. Treasury markets and global financial stability. As Robin Brooks warns, the failure of the yen to rally against a backdrop of falling U.S. rates is a “really worrying sign” that the tools to manage the intertwined debt and currency challenges may soon be exhausted.



Ripple Effects for Risk Assets
The joint currency intervention has fueled bullish momentum in gold and crypto, while looming Bank of Japan rate hikes threaten to disrupt global asset flows and intensify market volatility.
The recent US-Japan coordinated yen intervention underscores a cautious but clear willingness among central banks to backstop markets, signaling a near-term bottom for risk assets like cryptocurrencies and gold. Analysts such as Arthur Hayes highlight that this joint action, facilitated through the Federal Reserve’s currency swap and FIMA repo facilities, not only aims to stabilize the yen but also catalyzes bullish momentum in alternative assets, with gold rising 7.68% from recent lows and crypto markets poised for a rally despite lingering short-term volatility.
Future monetary policy coordination faces significant structural headwinds rooted in the yen carry trade, where persistently low Japanese rates encourage yen borrowing and selling, thereby weakening the currency and reinforcing downward pressure. As MacroXX explains, this carry trade acts as a transmission mechanism linking Japanese monetary policy to US financial conditions, influencing demand for Treasuries, credit, and equities. However, the narrowing interest rate differential—Japan’s policy rate at 1% versus the Federal Reserve’s 3.5%–3.75%—reduces the margin for error, making coordinated interventions more challenging amid increased market volatility and skepticism about sustained commitment.
The Bank of Japan’s prospective rate hikes represent a paradoxical but necessary step to regain control over long-term bond yields, which have surged to 30-year highs. Experts like Steven Major note that pushing short-term yields higher is essential to make Japanese bonds attractive enough to repatriate domestic investor funds from overseas equities and credit markets back into domestic bonds. This shift could exert downward pressure on global asset classes, adding complexity to future coordinated interventions and heightening tensions in markets such as France’s 30-year bond sector, which, while not crisis-triggering, reflects broader momentum challenges.
The unwinding of yen-funded positions poses systemic risks beyond currency markets, as leveraged investors may be forced to sell a broad array of assets—including US growth stocks and emerging-market bonds—to repay yen loans, amplifying market instability. The complexity is compounded by the trillions in yen-linked foreign-exchange derivatives, which obscure speculative flows and complicate intervention efficacy. While Federal Reserve facilities like the FIMA repo backstop can alleviate some pressure by reducing Japan’s need to offload Treasuries, they cannot prevent forced selling in equities triggered by yen volatility, underscoring the fragile and interconnected nature of future monetary policy coordination.